
The lowest-cost source of tax planning leads is referrals from CPAs, estate planning attorneys and financial advisors, followed by your own client list and business-owner workshops. Paid search and LinkedIn come next, and bought leads come last. Paid search has a published benchmark: LocaliQ’s 2026 search advertising benchmarks put the average Google Ads cost per lead at $93.69 for business services and $131.63 for attorneys and legal services. Before you see a dollar, divide those numbers by your consult and close rates. Below are the ranking with the math, a vetting checklist for lead vendors, a nurture sequence timed to the tax calendar, and the IRS, bar and TCPA rules that apply to each channel.
Tax planning, tax resolution or tax attorney: different leads, different sources
“Tax leads” covers three businesses that rarely share a buyer. Know which one you are before you spend, because a vendor’s “tax leads” are usually resolution leads, and a planning firm that buys them ends up talking to people who want an IRS debt settled this month.
| Tax planning firm | Tax resolution firm | Tax attorney | |
|---|---|---|---|
| What the buyer wants | Lower future tax through entity choice, timing, retirement and exit moves | Relief from an existing IRS or state balance, levy or lien | Representation in audits, appeals, Tax Court, criminal matters, complex structuring |
| Typical buyer | Business owners, high earners, pre-exit founders, real estate investors | Consumers and small businesses with a balance due | Businesses, high-net-worth individuals, referred taxpayers under examination |
| Urgency | Low until a deadline or taxable event | High (a notice just arrived) | High for controversy, low for planning |
| Best lead sources | CPA and advisor referrals, workshops, content, LinkedIn | Search, pay-per-call, lead vendors, direct mail | CPA referrals, search, Local Services Ads, bar and peer networks |
| Main marketing rules | Circular 230 section 10.30, IRC 7216 for client data, FTC Act | All of the left, plus heavy FTC and IRS scrutiny of “pennies on the dollar” claims | State bar advertising rules, plus Circular 230 when practicing before the IRS |
The rest of this page is written for planning firms first, with separate sections for tax attorneys and for anyone thinking about buying resolution leads.
The best tax planning lead sources, ranked by cost per signed engagement
This ranking is my judgment of how each channel usually performs for proactive planning work, ordered by what it typically costs to land a signed engagement (not a raw lead). Your numbers will differ, so the next section shows how to calculate your own.
| Rank | Source | Main cost | Speed | Why it ranks here | Measure |
|---|---|---|---|---|---|
| 1 | CPA, estate attorney and financial advisor referrals | Partner time (lunches, co-hosted events, case reviews) | Slow to build, then steady | The referrer has already pre-sold your expertise and often your fee range | Signed engagements per referral partner per year |
| 2 | Existing clients and past prospects | Staff time, email tool | Fast | They already trust you; the constraint is IRC 7216 consent if you use return data | Upgrade rate from compliance to planning |
| 3 | Business-owner workshops and webinars | Venue or webinar tool, promotion, prep | Medium | One talk reaches a room of qualified owners and shows how you think | Consults booked per event, cost per attendee |
| 4 | Google Ads on high-intent terms | Clicks (LocaliQ 2026: $5.87 avg CPC business services, $9.87 legal) | Fast | Fast and measurable, but you pay for every researcher and price shopper | Cost per booked consult, not cost per lead |
| 5 | LinkedIn (organic plus ads) | Time, or ad budget from $10 a day | Medium | Owners and executives are reachable by title and industry, but lead forms skew cold | Consults from LinkedIn, by audience |
| 6 | Bought leads and live transfers | Per lead or per call, priced on request | Fast | Mostly resolution intent; shared leads mean you race other firms; compliance exposure | Signed engagements per $1,000 spent |
If you only fix one thing, fix the referral channel. Most firms have three or four partners who send work by accident. Turning that into a system with a named list, a quarterly touch and a clear one-line description of who you help is covered in how accounting firms build referral relationships, and the same mechanics apply to planning firms courting CPAs who do not want to give planning advice themselves.
How to use your client list without breaking IRC 7216
If you prepare returns, your client list is the cheapest planning lead source you own, and the most regulated. Under Treas. Reg. 301.7216-2(n) a preparer may keep a list of client names, mailing addresses, email addresses, phone numbers, entity classification and return form number, and use it to solicit “additional tax return preparation services.” The same paragraph says the list “may not be used to solicit any service or product other than tax return preparation services” and may not be transferred to anyone else.
Anything beyond that needs signed consent under Treas. Reg. 301.7216-3. Three details catch firms out:
- You cannot ask for consent to an unrelated solicitation after you hand the client the completed return for signature. Ask in the engagement letter packet instead.
- For Form 1040 clients, Rev. Proc. 2013-14 prescribes the mandatory wording, starting “Federal law requires this consent form be provided to you,” on its own document (paper consents at least 8.5 by 11 inches with 12-point type), plus the TIGTA complaint statement.
- A consent with no stated duration expires one year after signature, so put the renewal in your annual engagement cycle.
The same Rev. Proc. notes that a knowing or reckless violation of section 7216 is a misdemeanor with up to one year in prison or a $1,000 fine, and section 6713 adds a civil penalty of $250 per disclosure or use, up to $10,000 a year. Whether a planning engagement counts as “additional tax return preparation services” is a question for your counsel; the conservative route is a signed consent to use that names tax planning and advisory services.
Cost per signed engagement: the math with real benchmarks
Cost per lead tells you almost nothing in this category. A $40 lead that never books is worse than a $400 referral that signs. Use cost per signed engagement, calculated like this:
Cost per signed engagement = cost per lead ÷ (lead-to-consult rate × consult-to-client rate)
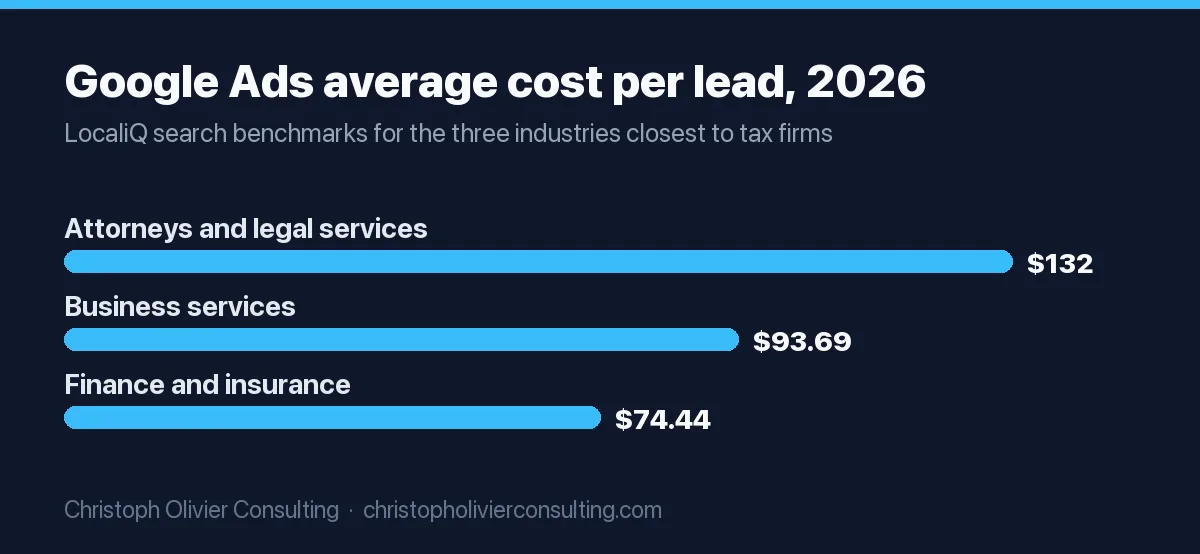
The only published, recent cost-per-lead figures that fit tax firms come from LocaliQ’s Google Ads benchmarks, last updated June 1, 2026 and drawn from its customers’ campaigns:
| LocaliQ industry (2026) | Avg CTR | Avg CPC | Avg conversion rate | Avg cost per lead | Closest fit |
|---|---|---|---|---|---|
| Attorneys and legal services | 5.87% | $9.87 | 5.55% | $131.63 | Tax attorneys |
| Business services | 6.10% | $5.87 | 4.85% | $93.69 | Planning firms selling to owners |
| Finance and insurance | 9.83% | $3.39 | 2.64% | $74.44 | Advisor-led tax planning |
LocaliQ does not publish a separate accounting or tax line, so treat these as the nearest proxies, not tax-specific figures.
Worked example (illustrative rates, replace with yours). A planning firm buys Google Ads leads at the business-services average of $93.69. Suppose 1 in 4 leads books a consult (25%) and 1 in 3 consults signs (33%). That is 0.25 × 0.33 = 0.0825, so each signed engagement costs $93.69 ÷ 0.0825 = about $1,136. A tax attorney at the legal average of $131.63 with the same rates pays about $1,596. If either firm’s first-year fee is several times that, the channel works; if not, fix conversion before adding budget.
Run the same worksheet for every channel each quarter:
- Total spend for the channel (ad spend, vendor invoices, event costs, plus staff hours at a fixed hourly rate).
- Leads, booked consults and signed engagements from that channel, pulled from your CRM, not from the ad platform.
- Cost per signed engagement = spend ÷ signed engagements.
- Payback = cost per signed engagement ÷ average monthly or annual fee for that client type.
- Cut or fix any channel whose cost per signed engagement is more than double your best channel for two quarters running.
For budget levels to plug into step 1, see how much tax planning firms should spend on marketing.
Google Ads and LinkedIn: what is specific to tax firms
On Google, bid on terms that describe a situation, not a service category: “S corp election accountant,” “tax planning before selling my business,” “tax strategist for real estate investors,” plus your city. Generic “tax help” pulls preparation and resolution traffic. Check one policy before you write copy: Google’s debt services policy allows debt settlement ads in the US only from approved nonprofit credit counseling agencies and requires certification. The policy page does not name tax debt, so resolution firms whose ads offer to settle a balance for less should read it before launch. Setup details are in Google Ads for tax planning firms.
On LinkedIn, LinkedIn’s own guidance sets the minimum at $10 a day ($100 lifetime for a new campaign) and suggests $25 a day for new advertisers. That is $750 a month at the suggested level, so test one audience (for example, owners of 10 to 50 employee companies in two industries) with one offer, such as a workshop invite, before scaling.
Lead generation for tax attorneys
Tax attorneys get most of their best matters from CPAs and enrolled agents who hit something beyond their scope: an examination going badly, a criminal referral risk, a Tax Court petition. Build that referral list first. Then add two paid channels that fit controversy work:
- Google Local Services Ads. Google says you pay only when a customer contacts you from the ad. Availability depends on category and location, so check at sign-up whether a tax law category is open in your market.
- Search ads on problem terms such as “IRS audit lawyer,” “tax court attorney” or “trust fund recovery penalty attorney,” budgeted against the $131.63 legal cost per lead above.
Paying for leads is allowed for lawyers under the ABA Model Rules, with conditions. The 2012 amendments to the comments on Rule 7.2, reported by the ABA Journal, permit paying for lead generation as long as the generator does not vouch for the lawyer’s credentials or abilities, does not create the impression the referral is unpaid, and does not claim it matched the lawyer after analyzing the person’s legal problem. States add their own layer. Florida, for example, requires most lawyer advertisements to be filed with the Bar for review at least 20 days before first dissemination under Rule 4-7.19. Check your own state’s rule text before running any vendor program or ad.
Tax attorneys who represent clients before the IRS are also practitioners under Circular 230, so the section 10.30 rules below apply to them as well.
Buying tax leads: what vendors sell and how to vet them
If you searched “buy tax lead generation,” here is what is on offer. Vendors sell four formats: shared web leads (one form fill sold to several firms), exclusive web leads, pay-per-call, and live transfers (a screened caller connected to your intake line, often billed after a minimum call length). Most filter by tax debt size and state. Prices are rarely published: SuperMoney’s tax leads page, for example, describes cost-per-lead delivery to your CRM and pay-per-call transfers, and asks you to contact sales for pricing. Get every price, filter and return rule in writing.
Two enforcement facts should shape how you buy. In June 2026 the FTC and Nevada settled with the operators of American Tax Service, alleging they impersonated government agencies including the IRS, claimed they could settle back taxes for “pennies on the dollar,” and upsold older consumers. The order imposes a $77.7 million judgment (mostly suspended), with over $8 million surrendered, and bans the individuals from debt relief services and nearly all outbound telemarketing. Separately, the IRS’s May 14, 2026 Tax Tip 2026-40 lists offer in compromise “mills” on its 2026 Dirty Dozen, describing them as schemes that “often overpromise results and charge high fees.”
Your exposure as a buyer is real. Circular 230 section 10.30(d) bars a practitioner from accepting assistance from anyone who, to the practitioner’s knowledge, obtains clients in a way the section forbids. If you know a vendor’s mailers look like IRS notices, buying its leads is a Circular 230 problem.
Tax lead vendor checklist (pass or fail)
| Check | Pass | Fail |
|---|---|---|
| Ad and mailer samples | Vendor sends every creative that generated your leads | “Proprietary,” or creative looks like an IRS or state notice |
| Claims in the creative | Describes options and a free review | “Pennies on the dollar,” “you qualify,” guaranteed results |
| Exclusivity | Written statement of exclusive vs shared, and to how many buyers | Vague “premium” or “high quality” wording |
| Consent records | Provides the consent language and timestamp for each lead, naming your firm | Generic “partners” consent or no record |
| Filters | Debt size, state, filing status and IRS vs state debt, in writing | Filters promised only on a call |
| Returns | Credits for wrong numbers, duplicates and out-of-filter leads within a stated window | No returns, or credits at vendor’s discretion |
| Pilot terms | Small test order, no long contract | Minimum monthly commitment before any test |
For a planning firm, my view is that bought leads are rarely worth it. The intent is wrong for planning, and the consent and compliance burden falls on you.
Lead magnets that fit tax planning prospects
A good tax planning lead magnet helps an owner see a decision they have not made yet. The compliance line from section 10.30 is simple: describe the analysis, never promise the result.
| Lead magnet | Best for | Compliant framing | Framing to avoid |
|---|---|---|---|
| Tax-savings estimator (inputs: entity, profit, owner pay, state) | S corp candidates, high-earning sole proprietors | “See which planning moves apply to your numbers, then review them with a CPA” | “Find out how much you’ll save,” or a dollar figure shown as a promise |
| Entity-structure checklist | New and growing owners | “12 questions to answer before you change your entity” | “The entity that cuts your taxes” |
| Pre-sale tax readiness scorecard | Owners 1 to 3 years from exit | “Score your readiness across 8 areas” | “Keep more of your sale price, guaranteed” |
| Year-end planning calendar | All planning prospects, sent in Q4 | “What to decide before December 31, by client type” | Deadlines without a source |
| Extension-season review offer | Owners on extension until October | “Book a 30-minute review while your return is still open” | “We’ll find you a refund” |
More formats, with examples, are in lead magnet ideas for tax planning firms.
A tax firm lead nurturing campaign you can copy
Most planning prospects are not ready the week they opt in. They become ready when a deadline or taxable event arrives. So a tax firm lead nurturing campaign has two layers: a short welcome sequence after opt-in, and seasonal emails that ride the tax calendar.
Layer 1: the first 21 days after opt-in
| Day | Channel | Subject or message | Body (short version) |
|---|---|---|---|
| 0 (within 5 minutes) | Your [checklist] is attached | Deliver the asset. One line on who you help (“owners of $1M to $10M service businesses”). One link to book a 20-minute fit call. | |
| 0 (only with SMS consent) | Text | “Hi [Name], it’s [Firm]. Your checklist is in your inbox. Reply here with questions. Reply STOP to opt out.” | Sent between 8 a.m. and 9 p.m. in the recipient’s time zone. |
| 2 | The question most owners skip | Pick the one checklist item prospects get wrong most and explain the decision, not the outcome. | |
| 5 | How a planning engagement works here | Your process step by step: data request, analysis, meeting, implementation calendar, fee structure. | |
| 9 | A planning review, start to finish | An anonymized, typical engagement walkthrough with no promised savings figure. Use only a real, consented example or a clearly labeled hypothetical. | |
| 14 | Is this for you? (and when it is not) | Who is a fit and who should use a preparer instead. Disqualifying builds trust. | |
| 21 | Should I keep sending these? | Plain-text note from the partner. Ask for a one-word reply: “now,” “later” or “no.” |
Layer 2: seasonal emails on the tax calendar
| Window | Prospect mindset | Send | Offer |
|---|---|---|---|
| October 16 to December 31 (year-end planning) | “Is there anything I should do before the year closes?” | Two to three emails: year-end decision checklist, a “last call for reviews” note in early December | Year-end planning review, limited slots |
| January to April 15 (tax season) | Busy, reactive, seeing last year’s bill | One email a month, short: “What your 2026 return tells you about 2027” | Waitlist for a post-season planning call |
| April 16 to October 15 (extension season) | Extended filers still have an open return; others are now receptive | Monthly email; for extended filers, a review offer before October 15 | Planning review while the return is still open |
| Any time: taxable event | Sale, inheritance, equity vesting, new entity | Trigger-based email when a CRM field or reply flags the event | Event-specific consult |
The October 15 date comes from the IRS’s automatic 6-month extension from the April 15 deadline for calendar-year individual filers. To build both layers in a CRM, with triggers and tags, see marketing automation for accounting firms.
Compliance checklist before you launch any channel
This is general marketing guidance, not legal advice. Confirm specifics with counsel or your ethics resource.
- No false, misleading or coercive claims about IRS matters. 31 CFR 10.30(a)(1) covers every public communication and private solicitation. Market the process, not a savings number.
- Use designations exactly. Enrolled agents may not call themselves “certified” or imply IRS employment. The rule supplies wording such as “enrolled to practice before the Internal Revenue Service.”
- Label cold outreach. Any lawful uninvited solicitation must say it is a solicitation and, where it applies, name the source of the information used to pick the recipient.
- Keep copies for 36 months. For direct mail and e-commerce communications, keep a copy and the recipient list for at least 36 months after last use. Stop contacting anyone who says they do not want to be solicited.
- Honor published fees. If you publish fees, you cannot charge more than those rates for at least 30 calendar days after publication.
- Client data: section 7216 consent before using return information to market anything beyond return preparation (see above).
- Texting: autodialed or prerecorded marketing calls and texts to wireless numbers need prior express written consent under 47 CFR 64.1200, and consent cannot be a condition of buying. Honor opt-outs by any reasonable means, including a “stop” reply, within 10 business days. No telephone solicitations before 8 a.m. or after 9 p.m. local time. The FCC replaced its delayed “revoke all” requirement with a new revocation rule that takes effect November 25, 2026 (91 FR 67214, published October 26, 2026), so plan for an opt-out on one marketing message stream to stop all of your marketing texts.
- Tax attorneys: your state’s advertising rule, including any pre-filing requirement, and the lead generation conditions in Rule 7.2.
If you want a second opinion on which of these channels to fund first for your practice, you can book a consultation and bring your last 12 months of lead and engagement numbers.
Frequently asked questions
What is the best tax planning lead generation channel?
For most planning firms it is referrals from CPAs, estate planning attorneys and financial advisors, because the referrer has already vouched for you. Your own client list and business-owner workshops come next. Google Ads is faster but costs more per signed engagement: LocaliQ's 2026 benchmarks put the average cost per lead at $93.69 for business services, before your consult and close rates.
How do tax attorneys generate leads?
Mainly through CPAs and enrolled agents who refer audits, appeals, Tax Court and criminal exposure matters, plus search ads on problem terms and Google Local Services Ads where a tax law category is open in your market. Paying a lead generator is allowed under ABA Model Rule 7.2 comments only if it does not vouch for you or claim it analyzed the client's problem. Check your state bar's rules.
Should I buy tax leads?
Planning firms rarely benefit, because most purchased tax leads carry resolution (IRS debt) intent. If you buy, get exclusivity, filters, consent records and return terms in writing, review every ad and mailer, and run a small pilot first. Circular 230 section 10.30(d) bars accepting help from anyone you know gets clients through misleading solicitations, and the FTC has acted against deceptive tax relief marketers.
What should a tax firm lead nurturing campaign include?
Two layers. First, a 21-day welcome sequence: deliver the lead magnet within minutes, then emails on a common mistake, your process, a typical engagement walkthrough, who is and is not a fit, and a final reply request. Second, seasonal emails for year-end planning (October to December), tax season (January to April 15) and extension season (through October 15), plus triggers for taxable events.
How much does a tax lead cost?
Published Google Ads benchmarks from LocaliQ (2026) show an average cost per lead of $131.63 for attorneys and legal services, $93.69 for business services and $74.44 for finance and insurance. Lead vendors rarely publish prices. What matters is cost per signed engagement: cost per lead divided by your lead-to-consult rate times your consult-to-client rate.
Can tax advisors use client tax return data for marketing?
Only within IRC 7216. A preparer may use a client list of names, contact details, entity type and form number to solicit additional tax return preparation services, but not other products, and may not transfer it. Other uses need a signed consent, with mandatory wording for Form 1040 clients under Rev. Proc. 2013-14, requested before the completed return is handed over for signature.
Can a tax firm text leads?
Yes, with prior express written consent for autodialed or prerecorded marketing texts under 47 CFR 64.1200, and consent cannot be a condition of buying your services. Honor STOP and other reasonable opt-outs within 10 business days, and avoid telephone solicitations before 8 a.m. or after 9 p.m. in the recipient's time zone. Some states add stricter rules, so check yours.
More marketing guides for tax planning firms
- How Much Should a Tax Planning Firm Spend on Marketing?
- How Tax Planning Firms Get Cited and Recommended by AI Search
- Marketing KPIs and Metrics a Tax Planning Firm Should Track
- CRM and Client Follow-Up for Tax Planning Firms
- How Tax Planning Firms Get More Online Reviews and Manage Reputation
- How a Tax Planning Firm Builds a Website That Converts Visitors Into Consultations