
Yes, in most cases a CPA firm can pay a referral fee, but only if the firm discloses the payment to the client in writing, and only where the state board allows it. The AICPA Code of Professional Conduct does not ban referral fees at all. It bans commissions when the firm also performs an audit, review, certain compilations or an examination of prospective financial information for that client, and it requires written disclosure of every referral fee paid or received. The big exception is California, where the Accountancy Act says a CPA “shall not” pay a fee or commission to obtain a client.
Below: the exact rule text with citations, a decision table for each way money can move, the five state rules verified for this article (California, Texas, New York, Florida, Illinois), the federal overlays (SEC independence, IRS Circular 230, the SEC Marketing Rule when an advisor is the one paying you), and a disclosure template you can adapt. This is a summary of published rules, not legal advice. Before you sign a referral agreement, confirm the current rule with your state board or counsel.
Short answer: Under AICPA ET 1.520.001, a CPA who pays a referral fee to obtain a client, or accepts one for referring a CPA’s services, must disclose it to the client, and since 2017 that disclosure must be in writing (ET 1.520.080). Commissions are prohibited for any client you audit, review or examine. California bans paying for client referrals outright, and New York and California require a client-signed disclosure in 12 point type.
What the AICPA rule actually says (ET 1.520.001)
Most pages on this topic still quote “Rule 503,” the pre-2014 numbering. The current rule is the Commissions and Referral Fees Rule at ET 1.520.001 in the AICPA Code of Professional Conduct (the edition hosted by the Minnesota Board of Accountancy, updated through July 2026). It has four paragraphs, and they treat commissions and referral fees differently:
- Prohibited commissions (.01). A member in public practice “shall not for a commission recommend or refer to a client any product or service, or for a commission recommend or refer any product or service to be supplied by a client, or receive a commission,” when the firm also performs for that client (a) an audit or review of a financial statement, (b) a compilation “when the member expects, or reasonably might expect, that a third party will use the financial statement” and the report does not disclose a lack of independence, or (c) an examination of prospective financial information.
- Time window (.02). The ban covers the period of the engagement “and the period covered by any historical financial statements involved in such listed services.” So a commission received in 2025 can taint a 2025 audit you are hired for in 2026.
- Disclosure of permitted commissions (.03). If you are allowed to take the commission, you “shall disclose that fact” to anyone you recommend the product or service to.
- Referral fees (.04). “Any member who accepts a referral fee for recommending or referring any service of a CPA to any person or entity or who pays a referral fee to obtain a client shall disclose such acceptance or payment to the client.”
Two interpretations finish the picture. ET 1.520.080 says the disclosures in paragraphs .03 and .04 must be made “in writing,” effective for arrangements entered into on or after January 31, 2017. ET 1.520.040 says you are responsible for distributors or agents acting on your behalf, so routing a commission through a third party does not get around the attest-client ban.
Notice the asymmetry. Paragraph .01 has no referral-fee ban at all. A referral fee, in AICPA terms, is money for referring a CPA’s services (yours or another CPA’s). A commission is money for recommending a product or service someone else supplies, like an insurance policy, a fund or software. The attest prohibition applies to commissions. Referral fees only trigger disclosure.
Paying vs receiving: which arrangements are allowed
This decision table maps each common money flow to the AICPA rule. State rules can be stricter, so read it together with the state table further down.
| Arrangement | Client is an audit, review, third-party compilation or prospective-FI client | Client is a non-attest client (tax, advisory, bookkeeping) | AICPA citation |
|---|---|---|---|
| Your firm pays a financial advisor, attorney or another CPA a fee for sending you a client | Allowed by AICPA with written disclosure to the client; check independence rules if the payee is the attest client itself | Allowed with written disclosure to the client | ET 1.520.001.04, 1.520.080 |
| Your firm receives a fee for referring a client to another CPA firm | Allowed with written disclosure | Allowed with written disclosure | ET 1.520.001.04, 1.520.080 |
| Your firm receives a commission for recommending an insurance policy, investment product or software to a client | Prohibited during the engagement and the period covered by the statements | Allowed with written disclosure | ET 1.520.001.01 to .03, 1.520.080 |
| Commission paid through a distributor or agent instead of directly | Prohibited (you are responsible for agents acting on your behalf) | Allowed with written disclosure | ET 1.520.040 |
| Commission for referring a non-attest client’s products to owners, officers or employees of an attest client | Allowed with disclosure to those owners, officers or employees | Not applicable | ET 1.520.050 |
| Your spouse earns the commission | Allowed only if the spouse’s activities are separate from your practice and you are not significantly involved | Allowed | ET 1.520.030 |
| You buy a product, take title and resell it at a profit | Not a commission | Not a commission | ET 1.520.060 |
| You mark up a subcontractor’s bill | Not a commission | Not a commission | ET 1.520.070 |
One timing trap from ET 1.520.040: if you take a disclosed commission from a non-attest client and later accept an audit or review covering the period when the commission was received, the AICPA treats that as a violation. Before you take any commission, ask whether that client could need audited or reviewed statements for the same year, for a bank loan or a sale.
State board rules: five states compared
The AICPA Code binds AICPA members. Your license is governed by your state board, and boards copy, tighten or ignore the AICPA wording. These five rules were read in full for this article; each row cites the section you can pull yourself.
| State | Citation | Can a CPA pay a fee to get a client? | Commissions for attest clients | What the written disclosure must contain |
|---|---|---|---|---|
| California | Bus. & Prof. Code 5061; 16 CCR 56 | No. 5061(a)(1): shall not “pay a fee or commission to obtain a client.” Also no fee “solely for the referral of a client to a third party.” | Prohibited for audit, review, third-party compilation and prospective FI clients, and for their officers, directors and client-sponsored retirement plans (5061(c)) | 12 point type or larger; statement that the fee is for professional services and cannot be accepted solely for a referral; product or service; third party’s identity; business relationship; description of the fee; dollar amount or basis. Signed and dated by the client; kept 5 years. |
| Texas | 22 TAC 501.71 | Not prohibited by 501.71; written disclosure required for compensation paid or received | Prohibited when you perform any service “requiring independence under 501.70” | “The nature, source, and amount, or an estimate of the amount when the amount is not known,” in writing, no later than the recommendation, referral or sale |
| New York | 8 NYCRR 29.10(i); 29.1(b)(4) | Not directly addressed; 29.10(i) replaces the general ban on referral fees in 29.1(b)(3), but the fee-splitting ban in 29.1(b)(4) still applies | Prohibited for audit, review, third-party compilation, prospective FI “and/or any other service” (see note below) | 12 point type or larger, on firm letterhead, signed by the licensee; product or service; third party’s identity; business relationship; description of the commission; dollar amount or basis. Client signs, dates and acknowledges. Kept 7 years. |
| Florida | Fla. Stat. 473.3205; Rule 61H1-21.003 | No for attest and CPA financial-statement work: may not “accept or pay a commission or referral fee” for public accounting services in 473.302(8)(a) and (c) | Prohibited for audit, review, compilation, prospective financial data and opinion-level special procedures | Commissions: an engagement letter signed by the client before work starts, with “complete details of the financial arrangements” |
| Illinois | 68 Ill. Admin. Code 1420.200 | Yes, but failing to disclose it is unprofessional conduct (1420.200(a)(5)) | Follows the AICPA Code, incorporated by reference (2015 edition) | Disclosure of the referral fee to the client; also bans any fee for “professional services not actually rendered” (a)(10) |
California: the strictest of the five
Section 5061(a) is blunt: “Except as expressly permitted by this section, a person engaged in the practice of public accountancy shall not: (1) pay a fee or commission to obtain a client or (2) accept a fee or commission for referring a client to the products or services of a third party.” The only commissions allowed under 5061(b) are for providing a third party’s products or services “in conjunction with professional services provided to the client,” and “fee” is defined in 5061(f) to include “a commission, rebate, preference, discount, or other consideration, whether in the form of money or otherwise.” That definition matters for gift cards and “thank you” dinners. The California Board of Accountancy’s consumer notice repeats the point: a licensee “still is prohibited from accepting any fee or commission solely for referral of a client to a third party.” Payments for buying a practice and retirement payments are carved out in 5061(g).
Texas: disclosure of nature, source and amount
Texas Rule 501.71(c) reaches both sides of the deal: a person who “receives, expects or agrees to receive, pays, expects or agrees to pay, other compensation in exchange for services or products recommended, referred, or sold by him” must disclose “in writing the nature, source, and amount” no later than the recommendation. The attest ban in 501.71(a) is tied to any service “requiring independence,” which is broader wording than the AICPA’s three-item list. Practice sale and retirement payments are excluded under 501.71(d).
New York: commissions defined to include referral fees
8 NYCRR 29.10(i)(1) defines commission as “compensation, including a referral fee, remuneration paid by a third party to the licensee” for recommending or referring a product or service supplied by another person. Paragraph (5) lets a licensee who is not doing attest work for the client accept a commission with a 12 point written disclosure given before the service is performed. One drafting point to check with the State Board: the published list of prohibited services in 29.10(i)(2)(i) ends with “(d) and/or any other service,” which reads more broadly than paragraph (5) allows. Paragraph (7) also exempts licensees doing accounting, advisory, consulting or tax work for an entity not required to register under Education Law 7408. Separately, the general rule in 29.1(b)(4) bans “permitting any person to share in the fees for professional services” other than partners, employees, associates, or a subcontractor or consultant “authorized to practice the same profession.” A revenue split with a non-CPA partner is the arrangement most likely to hit that line.
Florida: the statute covers attest work, not tax
Florida Statute 473.3205 bans paying or accepting a referral fee “in connection with the sale or referral of public accounting services as defined in s. 473.302(8)(a) and (c).” Paragraph (a) is attest and assurance work and (c) is preparing financial statements; 473.302(8)(b), which covers tax, management advisory and consulting services, is not named in the ban. Commissions on products sold to clients must be disclosed to the client in writing. The statute expressly does not prohibit practice purchase payments, retirement payments, or “payment of fees to a referring certified public accountant or firm for public accounting services to the successor certified public accountant or firm or the client in connection with an engagement.”
Illinois: the AICPA rule, frozen at 2015
Illinois lists “failure to disclose a referral fee to a client for recommending or referring any service of a CPA to any entity or who pays a referral fee to obtain a client” as unprofessional conduct in 1420.200(a)(5), and incorporates the AICPA Code “(2015, no later editions or amendments included).” The AICPA’s in-writing interpretation, ET 1.520.080, was added in August 2016, after that edition. Put the disclosure in writing anyway: it is still required of AICPA members, and it is your evidence if a client later says they were never told.
How much each rule asks you to disclose
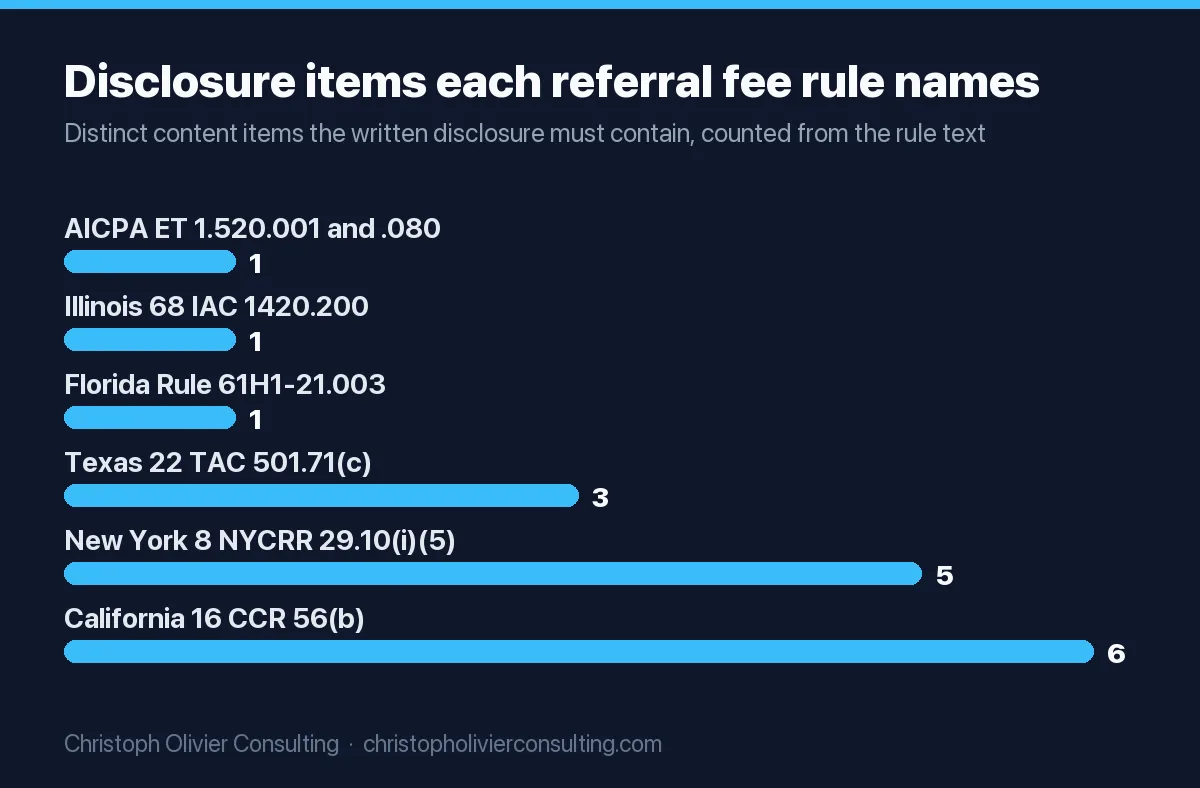
The chart counts the distinct content items each rule names for the written disclosure, taken from the citations in the state table above. More items means more paperwork per referral, and a template built for California or New York will also satisfy the lighter rules.
Audit clients: SEC independence rules
If the client files audited financial statements with the SEC, the federal rule is broader than the AICPA rule. SEC Regulation S-X Rule 2-01(c)(5) says an accountant “is not independent if, at any point during the audit and professional engagement period, the accountant provides any service or product to an audit client for a contingent fee or a commission, or receives a contingent fee or commission from an audit client.” There is no disclosure fix. The only compliant number is zero.
For private attest clients, watch the reverse relationship too. Under AICPA ET 1.265.010, a “cooperative arrangement” with an attest client, such as a joint venture to market services or one party acting as the other’s distributor or marketer, impairs independence if it is material to either side. A formal referral partnership with a law firm or RIA you also audit can drift into that territory. The interpretation lists the safeguards that keep it out: separate agreements that create no rights or obligations between you, neither side responsible for the other’s results, and neither side acting as the other’s agent.
IRS Circular 230: what changes for tax practices
Circular 230 does not mention referral fees by name, but two sections apply to how tax clients are found and billed.
- Section 10.30 (solicitation). A lawful solicitation “made by or on behalf of a practitioner” must “clearly identify the solicitation as such and, if applicable, identify the source of the information used in choosing the recipient.” Under 10.30(d), you may not “assist, or accept assistance from, any person or entity who, to the knowledge of the practitioner, obtains clients or otherwise practices in a manner forbidden under this section.” If a paid referral partner cold-pitches your tax services with misleading claims, that is your problem as well as theirs.
- Section 10.27 (fees). A practitioner “may not charge a contingent fee for services rendered in connection with any matter before the Internal Revenue Service,” with exceptions for exams of original returns, certain amended returns filed within 120 days of an exam notice, interest and penalty claims, and judicial proceedings. If a partner arrangement pushes you toward pricing by results, note that 10.27(c)(1) names a fee “based on a percentage of the taxes saved” as a contingent fee.
The AICPA’s own Contingent Fees Rule, ET 1.510.001, separately bars preparing “an original or amended tax return or claim for a tax refund for a contingent fee for any client.”
When a financial advisor pays the CPA: the SEC Marketing Rule
The most common referral fee question runs the other way: an RIA wants to pay your firm for introductions. For the advisor, your referral is an “endorsement” under SEC Rule 206(4)-1, which defines it to include any statement that “refers any current or prospective client” to the adviser. If the adviser compensates you, Rule 206(4)-1(b) requires:
- Clear and prominent disclosure that you are not a client, that you were paid, and a brief statement of your material conflicts, at the time of the referral.
- The material terms of the compensation arrangement.
- “A written agreement with any person giving a testimonial or endorsement that describes the scope of the agreed-upon activities and the terms of compensation.”
The written-agreement and disqualification conditions do not apply to “de minimis compensation,” defined as “$1,000 or less (or the equivalent value in non-cash compensation) during the preceding 12 months.” The disclosure condition still applies. So a single referral payment from an RIA triggers two disclosure regimes at once: theirs under the SEC rule and yours under ET 1.520 and your state rule. One document can satisfy both if it lists every required item. In California, the fee itself is the problem, since 5061 bars accepting a fee solely for referring a client to a third party.
How CPA firms structure compliant referral partnerships
My view: paying per referral is rarely the best growth lever for a CPA firm. Reciprocal relationships with a handful of advisors and attorneys, tracked like a pipeline, cost nothing to disclose and avoid most of the rules above. The playbook for that is in our guide on how accounting firms build referral relationships. If you do pay or accept money, set it up in this order:
- Classify every client the arrangement could touch. List which clients get audits, reviews, third-party compilations or prospective financial statements, now or for any period a commission would cover. Those clients are out for commissions under ET 1.520.001, Cal. B&P 5061(c), Texas 501.71(a), NY 29.10(i) and Florida 61H1-21.003.
- Check your state’s rule on paying, not just receiving. California prohibits paying to obtain a client. Florida prohibits it for attest and financial statement work. Texas, New York and Illinois focus on disclosure.
- Prefer payment for work over payment for names. California only allows a commission for a third party’s product provided “in conjunction with professional services.” AICPA ET 1.520.070 says marking up a subcontractor’s services is not a commission. A co-delivered engagement with a defined scope is easier to defend than a flat fee per introduction.
- Do not share professional fees with non-CPAs. New York 29.1(b)(4) bans it outright except for partners, employees, associates and same-profession subcontractors. A “20% of first-year fees” deal with an advisor is a fee split.
- Remember the other side’s rules. Attorneys answer to their state bar’s rules of professional conduct and RIAs to the SEC Marketing Rule. Each side should confirm its own rules in writing before money moves.
- Write the disclosure before the first referral, using the template below, and get the client’s signature where California, New York or Florida require it.
- Diligence the person you refer to. A 2020 Journal of Accountancy article on referral liability recommends checking credentials and complaint history, giving clients several names rather than one, and stating in writing that you have not supervised the professional’s work. A paid referral looks like an endorsement if something goes wrong.
For outreach scripts to approach advisors and attorneys, use our referral partner outreach templates. For the advisor’s side of the same relationship, see how financial advisors build referral partnerships.
Copy-ready referral fee disclosure template
This template is built to cover every content item named in the five state rules above plus AICPA ET 1.520.001 and 1.520.080. Print it on firm letterhead in 12 point type or larger (the New York and California minimum). Delete the bracketed notes before use, and have counsel or your state board confirm it fits your state.
| Section | Template text | Rule it satisfies |
|---|---|---|
| Heading | Disclosure of Referral Fee / Commission. [Firm name], [address]. Date: [date] | NY 29.10(i)(6) letterhead; CA 16 CCR 56(c) |
| 1. What is being recommended | We are recommending [product or service, e.g. “investment advisory services”] provided by [third party’s legal name, address]. | CA 56(b)(2); NY 29.10(i)(5)(i) |
| 2. Our relationship | [Firm] and [third party] have the following business relationship: [e.g. “a written referral agreement dated ___; no ownership interest in each other”]. | CA 56(b)(2); NY 29.10(i)(5)(i); SEC 206(4)-1(b)(1)(iii) if the payer is an RIA |
| 3. Who pays whom | [Firm] [will receive from / has paid to] [third party] a [referral fee / commission] in connection with this recommendation. The source of this payment is [third party / our firm]. | AICPA ET 1.520.001.03 and .04; TX 501.71(c) “source”; CA 5061(e)(4) |
| 4. How much | The amount is [$___] [or: computed as ___% of ___, estimated at $___ for the first year]. | TX 501.71(c) “amount, or an estimate”; CA 56(b)(3); NY 29.10(i)(5)(ii) |
| 5. Nature of the payment | This payment is [a one-time fee / an ongoing commission]. [California: “This fee is paid for professional services. A fee or commission cannot be accepted solely for the referral of a client to the products or services of a third party.”] | TX 501.71(c) “nature”; CA 56(b)(1) |
| 6. Your choice | You are not required to use [third party]. Our fees and services to you do not depend on whether you do. You may ask us for other options. | Good practice; ET 1.520.050.03 points to the Conflicts of Interest interpretation, ET 1.110.010 |
| 7. Acknowledgment | I have read and understand this disclosure. Client signature: ____ Date: ____ CPA signature: ____ Date: ____ | CA 56(c); NY 29.10(i)(6); FL 61H1-21.003(2) for commissions |
| Retention note (internal) | Keep the signed copy for at least 7 years and give the client a copy. | NY 29.10(i)(6) (7 years); CA 56(c) (5 years) |
Timing: hand it over before or at the time of the recommendation (Texas 501.71(c), California 56(b)) and, in New York, before the service is performed. If the specific product cannot be named yet, California and New York both require a supplemental disclosure within 30 days of receiving the fee.
Pre-payment checklist: pass or fail
| Check | Pass | Fail |
|---|---|---|
| Attest status of the client | No audit, review, third-party compilation or prospective FI engagement for this client or the periods involved | Any of those exists or is likely: no commission |
| Public company audit client | Not an SEC audit client | SEC audit client: no commission, no contingent fee (Rule 2-01(c)(5)) |
| State rule on paying for clients | Your state does not prohibit it (e.g. Texas, Illinois) | California, or Florida for attest and financial statement work |
| Fee sharing | Payment is a flat referral fee or a fee for defined work | Payment is a share of your professional fees to a non-CPA (fails New York 29.1(b)(4)) |
| Written disclosure | Signed template delivered before or at the recommendation | Verbal disclosure only, or disclosure after the fact |
| RIA counterparty | Written agreement on file if over $1,000 in 12 months; adviser’s disclosure delivered | No written agreement, or the adviser expects you to skip the disclosure |
| Tax fee structure | Your fee does not depend on the refund or taxes saved | Fee or partner payout tied to the tax result (Circular 230 10.27, ET 1.510.001) |
Referral fees are a small piece of growth for most firms. The bigger lever is a referral system and a clear niche, which we cover in marketing for CPA and accounting firms and the CPA marketing guide for 2026. If you want help designing a compliant partner program, you can book a consultation.
Ready to scale your revenue?
Book a free 30-min consultation. We’ll diagnose your growth bottleneck and map out the 3 highest-leverage moves for your business.
Frequently asked questions
Can CPA firms pay referral fees?
Under the AICPA Code, yes. ET 1.520.001 lets a member pay a referral fee to obtain a client if the payment is disclosed to the client, and ET 1.520.080 requires that disclosure in writing for arrangements from January 31, 2017. State law can be stricter: California Business and Professions Code 5061 says a CPA shall not pay a fee or commission to obtain a client, and Florida bans it for attest and financial statement work.
What are the AICPA rules on referral fees and commissions?
ET 1.520.001 prohibits commissions when the firm also performs an audit, review, a compilation a third party will use without disclosing lack of independence, or an examination of prospective financial information for that client. Permitted commissions must be disclosed. Anyone who pays or accepts a referral fee for CPA services must disclose it to the client, in writing under ET 1.520.080.
Can CPAs receive referral fees from financial advisors?
Often yes for non-attest clients, with written disclosure under ET 1.520 and your state rule. The advisor must also meet SEC Rule 206(4)-1: disclose that you were paid and your conflicts, and sign a written agreement with you unless total pay is $1,000 or less in 12 months. California is the exception, since 5061 bars accepting a fee solely for referring a client to a third party.
Do CPA referral fee rules differ by state?
Yes. California prohibits paying for client referrals and requires a client-signed disclosure kept five years. New York requires a 12 point disclosure on letterhead, signed by both sides and kept seven years. Texas requires written disclosure of nature, source and amount. Florida bans referral fees for attest work. Illinois makes undisclosed referral fees unprofessional conduct.
Can a CPA take a commission from an audit client?
No. AICPA ET 1.520.001 bans commissions while you audit, review or examine prospective financial information for that client and for the periods covered by those statements. For SEC audit clients, Regulation S-X Rule 2-01(c)(5) says the accountant is not independent if it provides any service or product for a commission or receives a commission from the audit client at any point in the engagement period.
Does a CPA referral fee disclosure have to be in writing?
Yes for AICPA members: ET 1.520.080 requires written disclosure of commissions and referral fees for arrangements entered into on or after January 31, 2017. Texas, California, New York and Florida also require writing, and California and New York require the client to sign and date the disclosure, in 12 point type or larger.