
Facebook ads for an accounting firm work best as a seasonal lead engine: a Leads campaign with an Instant Form or a booking page, a radius drawn around the area your firm actually serves, one offer per service (tax prep, IRS notice help, bookkeeping, year-end planning), and a fixed fee or fee range in the ad. Meta’s own help center lists “tax and accounting services” among the offers that are not part of its Financial products and services Special Ad Category, so a plain tax or bookkeeping campaign keeps the full targeting toolset. The rest of the job is budget math (Meta wants about 50 results a week per ad set), timing ads to the IRS calendar, copy that clears the AICPA Code and Circular 230, and calling every lead back within minutes.
Below: the setup decisions in one table, what Meta actually says about the Special Ad Category, a copy-ready Instant Form, a budget calculator, the 2027 tax-calendar schedule, creative specs, six ads you can paste into Ads Manager, and a pass/fail compliance check.
Facebook ads for an accounting firm: the setup in 8 decisions
Every setting below is explained further down with its source. Use the table as the brief for whoever builds the account.
| Decision | Default for a CPA, EA or bookkeeping firm | Why |
|---|---|---|
| Special Ad Category | None, for tax prep, bookkeeping and advisory offers | Meta lists “Tax and accounting services” as not included in Financial products and services |
| Campaign objective | Leads | Optimizes for form fills or booked calls, not clicks |
| Conversion location | Instant Form (Higher intent) for notice and advisory offers; website for fixed-fee bookings | Higher intent adds a review screen before submit |
| Ad sets | One per offer, not one per audience | Each ad set needs about 50 results a week to exit learning |
| Location | Office address plus a radius that covers your real client base | Advantage+ audience never expands past your location setting |
| Audience | Advantage+ audience on, radius as the hard limit | Location, minimum age, language and exclusions are never expanded |
| Creative | 1440 x 1800 image or video for Feed, 1440 x 2560 for Stories and Reels | Meta’s current recommended sizes |
| Follow-up | Call within 5 minutes, up to 6 attempts | Qualification odds drop sharply after the first hour (HBR, 2011) |
Do accountants need Meta’s Special Ad Category?
Usually not. Since January 21, 2025, Meta has required the Financial products and services Special Ad Category for financial products and services campaigns from advertisers based in the US or showing ads to US audiences, according to its help article How to Choose a Special Ad Category. The category replaced the old Credit category.
Meta’s article About ads for housing, employment or financial products and services lists what is in and out. In the US, covered offers include credit cards, loans, debt recovery, debt consolidation and relief, banking services, prepaid cards, investment services, pension or retirement funds, insurance products, consumer payment services, buy now pay later, and “brand ads for financial products and services, regardless of offer.” It then says these ads “don’t include offers for” gift cards, store rewards, business-to-business-only financial products and services, and tax and accounting services.
That settles the common case, but accounting firms often sell more than tax and accounting. Here is how Meta’s list maps onto a typical firm’s offers.
| Your ad promotes | Where Meta’s list puts it | Category to select |
|---|---|---|
| Individual or business tax preparation | Excluded: “tax and accounting services” | None |
| Bookkeeping, payroll, CFO or advisory services | Excluded: “tax and accounting services” | None |
| IRS notice response or representation | Not named by Meta. “Debt consolidation and relief” is on the covered list | None if the ad sells representation; expect review risk if it promises to reduce or settle tax debt |
| Refund advance or refund transfer products | A refund advance is a loan, and “loans” are covered | Financial products and services |
| Your wealth management, retirement plan or insurance arm | Covered: investment services, pension or retirement funds, insurance | Financial products and services |
Meta notes that its examples are “not a comprehensive list” and “not legal advice,” and that ads may be rejected if the right category is not chosen. If a reviewer rejects an accounting ad as a financial products ad, request a review and point to that exclusion.
What you lose if you select the category
Under the Special Ad Category, Meta’s help center says age, gender, ZIP code targeting, exclusion targeting, lookalike audiences and saved audiences are limited or unavailable, some interests disappear, and city or pin-drop locations get an expanded radius. Meta’s Marketing API documentation adds the exact limits: age fixed at 18 to 65+, all genders, no location exclusions, and a minimum 15 mile (25 km) radius around any selected city, address or dropped pin in the US and Canada. So if your firm also advertises an investment or insurance service, run it as a separate campaign so your tax and bookkeeping campaigns keep their normal targeting.
Campaign objective: Leads with Instant Forms or website conversions
Choose the Leads objective, then pick where the lead is captured. Meta’s help article on choosing an instant form type describes three form types: More volume (the default, built for quick mobile submissions), Higher intent, and Rich creative. Higher intent adds inline text under the contact fields saying the business may follow up, plus a review screen where people confirm their details. Meta says it “may make more sense” when every lead needs follow-up, and that it is delivered only to Facebook and Instagram feeds on mobile, not desktop.
| Offer | Conversion location | Form type | What you optimize for |
|---|---|---|---|
| IRS notice review, tax resolution consult | Instant Form | Higher intent | Leads, called within 5 minutes |
| Year-end planning or advisory meeting | Instant Form | Higher intent | Leads, booked to a partner calendar |
| Fixed-fee tax return, extension filing | Website booking page | Not applicable | Schedule event sent by the Pixel and Conversions API |
| Monthly bookkeeping | Instant Form or website | Higher intent | Leads, then a fit call |
| Checklist or guide download | Instant Form | More volume | Leads, then the email sequence |
Copy-ready Instant Form for a tax or bookkeeping firm
Keep it to the questions your intake person would ask on the phone anyway. Each answer routes the lead before anyone calls.
- Intro headline: “Tell us what you need. A [CPA / enrolled agent] will call you within one business hour.”
- Full name, phone, email (prefilled by Meta).
- “What do you need help with?” Multiple choice: Individual tax return / Business tax return / IRS or state notice / Monthly bookkeeping / Year-end planning.
- “Is this for you, a business, or both?” If business: “What type of entity?” (Sole proprietor, LLC, S corporation, Partnership, C corporation, Not sure).
- “When does this need to be done?” Before a filing deadline / Within 30 days / No deadline.
- “If you received a notice, what date is printed on it?” Short answer, optional. This sets call priority.
- Fee line on the intro or completion screen: “Individual returns start at $[fee]. Business returns from $[fee], depending on the condition of the books.” This is permitted fee information under Circular 230 and keeps the range honest under the AICPA Code (both covered below).
- Privacy policy link that says how you use the form data.
- Completion screen: “Thanks, [first name]. We call new requests within one business hour. Want to skip the wait? Book a time now:” with a button to your calendar.
Audience options for a CPA or tax firm
Location radius
Set your office address as a pin and draw the radius around the area you actually serve and can meet clients in. A firm whose work is face to face gains nothing from a radius twice the size of its service area. A virtual firm that files in several states can target those states instead of a radius. If you ever do select the Special Ad Category, the radius cannot go below 15 miles.
Advantage+ audience
Advantage+ audience lets Meta’s delivery system search beyond the audience you suggest. Meta’s developer documentation (updated June 26, 2026) says “non-negotiable business constraints are not expanded,” and names them: location constraints, minimum age, language and custom audience exclusions. With Advantage+ audience on, minimum age can only be set between 18 and 25 and the maximum is fixed at 65. For an accounting firm that means the radius is the setting that matters most. Excluding current clients also stays fixed, but it requires uploading a client list, which runs into the 7216 rule below.
Client lists, hashing and lookalikes
A customer list custom audience is built from identifiers such as email, phone and address. Meta’s customer list article says the data is hashed before use, and its hashing article says hashing “cannot be reversed” and the hashed data “is deleted promptly after the match process is complete.” A lookalike audience then finds people similar to that list. Meta notes that a smaller percentage matches the source more closely, and that a list of your best customers can beat a list of all customers.
The accounting-specific catch is federal, not Meta. Under Treas. Reg. 301.7216-1(b)(3), a taxpayer’s name, address or identifying number furnished in connection with return preparation is tax return information. Under Treas. Reg. 301.7216-3(a), unless section 7216 or 301.7216-2 specifically authorizes it, a preparer may not disclose or use that information before getting the taxpayer’s written consent, and the consent must be knowing and voluntary. Uploading tax clients’ emails to an ad platform is a disclosure and a use. Get signed 7216 consents, or have counsel confirm an exception, before a tax client list goes anywhere near Ads Manager. Lists of bookkeeping-only clients or newsletter subscribers who never gave you return information are a different question.
Budget math: what the learning phase costs an accounting firm
Meta’s article About the learning phase says ad sets exit learning once delivery is stable, which “usually occurs after about 50 results in the week after the ad set’s last significant edit.” During learning, performance is less stable and cost per result is usually higher. Ad sets that cannot get enough results show “Learning limited.” So the minimum budget that lets one ad set learn is:
Weekly budget = 50 x your cost per lead. Daily budget = weekly budget divided by 7.
| Cost per lead you expect | Weekly budget for 50 leads | Daily budget | Per 30 days |
|---|---|---|---|
| $15 | $750 | $107 | $3,214 |
| $27.39 (WordStream all-industry median, Leads campaigns) | $1,370 | $196 | $5,869 |
| $40 | $2,000 | $286 | $8,571 |
| $60 | $3,000 | $429 | $12,857 |
Most small firms cannot fund that for every offer, which is why the setup table says one ad set per offer and one or two offers at a time. If your budget sits below the 50-result line, the campaign can still produce leads; it will just run as “Learning limited” with less stable costs. Do not respond by splitting it further.
From budget to clients: a worked example
Plug your own rates into this chain. The rates below are placeholders to show the arithmetic, not benchmarks.
- Monthly budget $3,000 at $27.39 per lead = 109 leads.
- Reached by phone (example 60%): 65 conversations.
- Booked a consultation (example 40%): 26 consultations.
- Signed an engagement (example 30%): about 8 new clients.
- Cost per new client: $3,000 / 8 = $375. Compare it with first-year fees, not with cost per lead.
Where this sits inside a whole-firm budget, with the busy-season pauses already planned, is covered in the accounting firm marketing plan template.
Facebook ads benchmarks for accountants: what exists in 2026
There is no published accounting-specific Facebook ads benchmark from WordStream or LocaliQ. Their 2026 Facebook ads benchmarks (published September 14, 2026) cover 452 US Leads campaigns and 1,377 US Traffic campaigns, and report medians. The Leads table has no accounting, finance, legal or business services row. The closest categories appear only in the Traffic table.
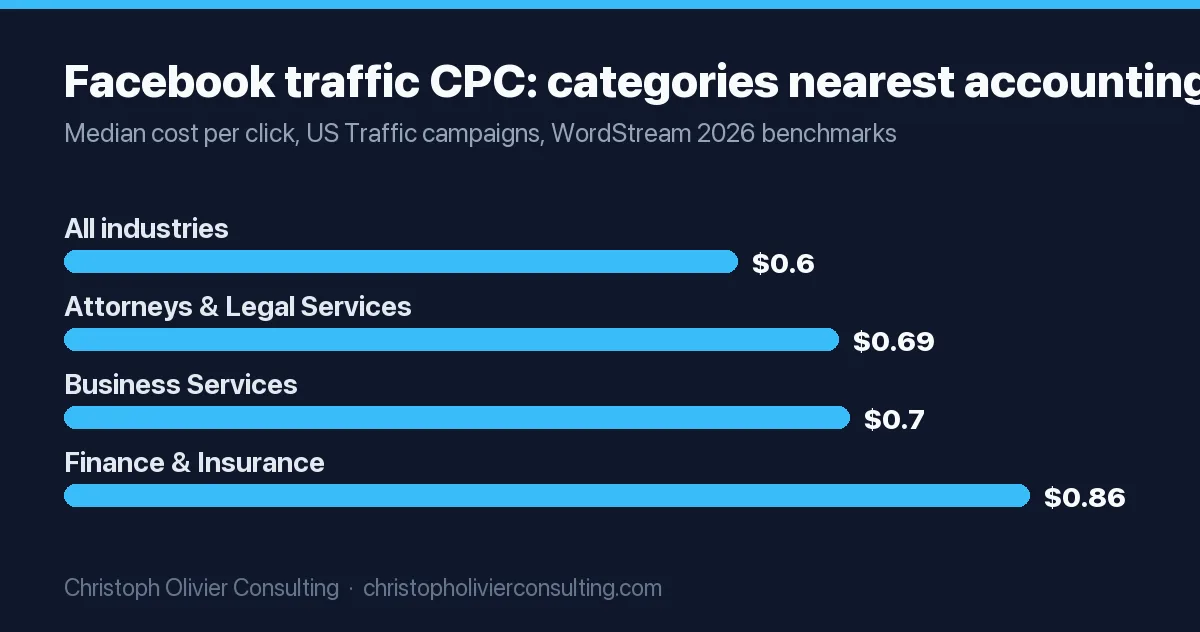
| Metric (WordStream 2026) | All industries | Business Services | Finance & Insurance | Attorneys & Legal |
|---|---|---|---|---|
| Traffic campaigns: CTR | 1.93% | 1.64% | 1.46% | 1.77% |
| Traffic campaigns: CPC | $0.60 | $0.70 | $0.86 | $0.69 |
| Leads campaigns: CTR | 2.70% | not reported | not reported | not reported |
| Leads campaigns: CPC | $1.80 | not reported | not reported | not reported |
| Leads campaigns: conversion rate | 8.54% | not reported | not reported | not reported |
| Leads campaigns: cost per lead | $27.39 | not reported | not reported | not reported |
Use $27.39 as a starting assumption for the budget table, then replace it with your own cost per lead after the first two to three weeks. Ignore any “accountant CPL” figure that does not name its sample.
When to run Facebook ads: the 2027 tax-calendar schedule
The deadlines below follow the rules in IRS Publication 509: partnership and S corporation returns are due the 15th day of the 3rd month after year end, individual returns the 15th day of the 4th month, each with an automatic 6-month extension (Form 7004 for businesses, Form 4868 for individuals). None of the 2027 dates falls on a weekend. Check the 2027 edition of Publication 509 when it is released.
| Window | Deadline it serves | Campaign | Budget setting |
|---|---|---|---|
| Nov 2 to Dec 18, 2026 | Tax year ends Thu, Dec 31, 2026 | Year-end planning meeting for business owners (ad 6) | Full |
| Jan 4 to about Feb 12, 2027 | Individual returns due Thu, Apr 15, 2027 | New individual and Schedule C clients (ad 1); catch-up books (ad 5) | Full, until your intake cap is hit |
| Feb 15 to Apr 15, 2027 | Business returns due Mon, Mar 15; individual returns Thu, Apr 15 | Retargeting only; IRS notice review (ad 3) if capacity allows | Reduced or paused |
| Apr 19 to Aug 13, 2027 | None | Monthly bookkeeping (ad 4), IRS notice review (ad 3) | Always-on, lower |
| Aug 16 to Oct 8, 2027 | Extended business returns Wed, Sep 15; extended individual returns Fri, Oct 15 | Extended-return clients (ad 2) | Full, short burst |
| Oct 18 to Dec 17, 2027 | Tax year ends Fri, Dec 31, 2027 | Year-end planning (ad 6) | Full |
Launch each burst at least a week before you need leads, so the ad set is through learning by the time demand peaks. The same dates drive the client emails in the 2027 CPA email calendar, so run the ad and the email to the same offer in the same week.
Creative specs for accounting firm ads
These match Meta’s Ads Guide and the full table in our Facebook ad dimensions guide. Design once at 1440 px wide and crop.
| Placement | Ratio and size | Text limits Meta recommends | Accounting-specific note |
|---|---|---|---|
| Facebook Feed image | 4:5, 1440 x 1800 px, JPG or PNG, up to 30 MB | Primary text 50 to 150 characters, headline 27 | Put the fee or the deadline in the headline, not only in the image |
| Instagram Reels and Stories image | 9:16, 1440 x 2560 px | Reels primary text 44 characters | Keep 14% top, 35% bottom and 6% each side free of text and logos |
My preference is a photo of the partner or team who will actually call back, or the office, over stock calculators: the ad is selling a person you will talk to. For layouts other service firms use, see these social media ad examples.
6 copy-ready Facebook ads for accountants and bookkeepers
Character counts include the bracketed placeholders, so keep real fees short. Each primary text is under Meta’s 150-character Feed recommendation and each headline is 27 characters or fewer.
1. Tax prep: Schedule C returns (January)
Primary text: “Sole proprietors filing Schedule C: federal and state returns for a fixed $[fee], quoted before we start. Upload your documents from your phone.”
Headline: “Schedule C returns: $[fee]”
Button: Book now. Destination: booking page.
Compliance note: a fixed fee for a routine service is allowed under Circular 230 §10.30(b). Charge no more than that fee for at least 30 calendar days after the ad last runs, and say whether the client pays extra costs such as state filing fees.
2. Tax prep: extended returns (August to October)
Primary text: “Individual returns on extension are due Friday, October 15, 2027. We have [number] openings for extended returns. Fixed fee from $[fee].”
Headline: “Extended returns, due 10/15”
Button: Book now.
Compliance note: the opening count must be true when the ad runs. “From $[fee]” is a range floor, so the AICPA Code requires telling the prospect if their fee is likely to be substantially higher.
3. Tax resolution: IRS notice review (year-round)
Primary text: “IRS notices print a response date. Our enrolled agents read the notice, explain what it asks for and draft the reply. Flat review fee: $[fee].”
Headline: “IRS notice review: $[fee]”
Button: Get quote. Destination: Higher intent Instant Form.
Compliance note: enrolled agents may not call themselves “certified” or imply employment by the IRS (§10.30(a)(1)), and the AICPA Code bars implying an ability to influence a regulatory agency. No IRS logos. Avoid “settle your tax debt” or “stop the IRS”: it promises a result, and debt relief is on Meta’s financial products list.
4. Bookkeeping: monthly service (always-on)
Primary text: “Monthly bookkeeping for [contractors] in [City]: accounts reconciled by the 15th and a profit and loss you can read. From $[fee]/month.”
Headline: “Books closed by the 15th”
Button: Learn more.
Compliance note: state what moves the price (transactions per month, number of accounts) on the form or landing page so the “from” price is not misleading.
5. Bookkeeping: catch-up before tax season (January)
Primary text: “Catch-up bookkeeping before tax season: we reconcile up to 12 months of bank and card accounts and hand your preparer a clean file.”
Headline: “12-month catch-up books”
Button: Get quote.
Compliance note: do not write “Behind on your books?” or “Drowning in receipts?” Meta’s personal attributes policy bars ads that assert or imply personal attributes, including “vulnerable financial status.” Describe the service, not the reader.
6. Small-business advisory: year-end planning (November to December)
Primary text: “Before December 31: a 45-minute planning meeting for S corporation owners on owner pay, entity choice and equipment timing. Fee: $[fee].”
Headline: “Year-end S corp review”
Button: Book now. Destination: Higher intent Instant Form or partner calendar.
Compliance note: no “save $X in taxes” claims; that creates an unjustified expectation of a favorable result. If the meeting also pitches retirement plans or investments, Meta’s list puts that content in the Financial products and services category.
Compliance check before any accounting ad goes live
Three rule sets apply at once. The AICPA Code of Professional Conduct, rule 1.600.001, says a member in public practice “shall not seek to obtain clients by advertising or other forms of solicitation in a manner that is false, misleading, or deceptive.” Circular 230 §10.30 applies to practitioners, CPAs, attorneys and enrolled agents among them, in any IRS matter. Meta’s ad standards sit on top. Your state board’s rules on the CPA title and testimonials also apply (AICPA 1.600.100 points members to them).
| Check | Pass | Fail | Rule |
|---|---|---|---|
| Outcome claims | Describes the service and the deadline | “Guaranteed refund,” “maximum refund,” “cut your tax bill by $5,000” | AICPA 1.600.010.02(a): no false or unjustified expectations of favorable results |
| Agency influence | “We draft and file the response” | “We know how to make the IRS back off” | AICPA 1.600.010.02(b) |
| Fees | Fixed fee, hourly rate, fee range or consultation fee, with what drives the range | A low teaser fee you expect to rise substantially, with no warning | Circular 230 §10.30(b)(1); AICPA 1.600.010.02(c) |
| Fee holding period | Published fee honored 30 calendar days after the ad’s last run | Fee raised the week the ad stops | Circular 230 §10.30(b)(2) |
| Record keeping | Copy of each ad and a description of who it targeted, kept 36 months | Ads deleted from Ads Manager with no archive | Circular 230 §10.30(c) (e-commerce communications) |
| Designations | “Enrolled to practice before the Internal Revenue Service” | “IRS certified,” IRS seal or logo | Circular 230 §10.30(a)(1) |
| Reader assumptions | “Catch-up bookkeeping for small businesses” | “Struggling with tax debt?” | Meta personal attributes policy |
| Client data | Signed 7216 consent before uploading tax clients | Practice management export uploaded as a custom audience | Treas. Reg. 301.7216-3 |
This is a marketing checklist, not legal advice. Have whoever owns compliance at your firm sign off on the first round of ads.
Lead handling: the first five minutes after a Facebook lead
A Facebook lead is someone who tapped a form on a phone, often outside office hours, and has not yet spoken to anyone. The 2011 study in Harvard Business Review found firms that tried to contact a lead within an hour were nearly seven times as likely to qualify it as firms that tried even an hour later. Our speed to lead statistics page traces that and the other response-time studies to their sources.
- Sync the Instant Form to your CRM or practice management intake so the lead creates a task and a text alert immediately, not when someone downloads a CSV.
- Call within 5 minutes during business hours. Open with what they asked for: “You just sent us a request about an IRS notice.”
- No answer: leave a 20-second voicemail and send a text with your booking link right away.
- Retry the same day, then on days 2, 4 and 7. Stop at six attempts.
- On the call, ask the fit, need, timing and fee questions, then book the consultation before you hang up.
The full phone script, qualification matrix and consultation agenda are in our playbook on turning calls into consultations at accounting firms. If you want a second opinion on the offer, the budget line or the compliance read before you spend, you can book a consultation.
Frequently asked questions
Do Facebook ads work for accounting firms?
They work best for specific, deadline-driven offers: fixed-fee returns in January, extended returns before October 15, IRS notice reviews, monthly bookkeeping and year-end planning meetings. Use the Leads objective, one ad set per offer, a fee or fee range in the ad, and call every lead back within five minutes. Generic brand ads that ask people to hire a CPA with no offer or deadline rarely pay back.
Do accountants have to use the special ad category on Facebook?
Not for tax or accounting offers. Meta's help center lists tax and accounting services among the offers that are not part of the Financial products and services Special Ad Category. You do need the category, for US audiences, if an ad promotes loans such as refund advances, investment services, retirement funds, insurance or debt relief. Run those as a separate campaign so tax and bookkeeping campaigns keep normal targeting.
How much should an accounting firm spend on Facebook ads?
Start from Meta's learning-phase guidance: an ad set usually exits learning after about 50 results in a week. Multiply 50 by your expected cost per lead. At the WordStream 2026 all-industry median of $27.39 per lead, that is about $1,370 a week, or $196 a day, for one ad set. Smaller budgets still produce leads but run as Learning limited.
What is a good cost per lead for Facebook ads for accountants?
No published benchmark covers accounting firms specifically. WordStream and LocaliQ's 2026 Facebook benchmarks report a $27.39 median cost per lead across all industries for Leads campaigns, with no accounting, finance or business services row. Use that as a starting assumption, then replace it with your own cost per lead and, more importantly, your cost per signed client after two to three weeks.
Can a CPA upload a client list to Facebook for ads?
Meta hashes customer lists and deletes the hashed data after matching, but that does not settle the tax rule. Under Treas. Reg. 301.7216-1, a client's name, address or identifying number furnished for return preparation is tax return information, and 301.7216-3 requires written, voluntary consent before disclosing or using it unless an exception applies. Get signed consents or counsel's sign-off before uploading tax clients.
What should Facebook ads for a bookkeeping service say?
Name the client type, the deliverable and the price driver: for example, monthly bookkeeping for contractors with accounts reconciled by the 15th, from a stated monthly fee that depends on transaction volume. Avoid lines like 'Behind on your books?', which Meta can reject for implying a personal attribute, and avoid any promised savings or outcome.
When should a tax firm run Facebook ads?
Run bursts ahead of demand: November to mid-December for year-end planning, early January to mid-February for new return clients, mid-August to early October for extended returns due September 15 (business) and October 15 (individual), with bookkeeping and IRS notice offers running at a lower level from April to August. Reduce or pause new-client ads during the February to April 15 crunch.
More marketing guides for cpa
- Lead Generation for CPA and Accounting Firms
- How Accounting Firms Get Cited and Recommended by AI Search
- How Much Should Accounting Firms Spend on Marketing
- Marketing KPIs for Accounting Firms: What CPAs Should Track
- CRM and Client Follow-Up for CPA and Accounting Firms
- How a CPA or Accounting Firm Gets More Online Reviews and Manages Its Reputation