
A fund manager meeting with a limited partner is rarely one meeting. It is a sequence of five: the first intro call, the investment deep dive, the on-site operational due diligence visit, the annual meeting, and the re-up conversation for your next fund. Each one has a different agenda, a different set of materials, and a different pass test, and institutional LPs score all of them against the same 20 topics in the ILPA Due Diligence Questionnaire 2.0 (updated November 2021). Below is what to bring to each meeting, what LPs evaluate, what the SEC lets you say and show, a copy-ready agenda and follow-up email, and a pipeline tracker with the math. This is general information, not legal or investment advice. Your fund counsel and CCO decide what applies to your offering.
The five fund manager meetings at a glance
Use this table to decide which meeting you are actually in. Most stalled raises come from running the wrong meeting: pitching performance on an operations visit, or walking into a first call with a 40 page appendix. The lengths and timings are my working rule of thumb for an emerging or mid-size manager, not an industry standard.
| Meeting | When | Typical length | Bring | What the LP is testing | Your goal leaving the room |
|---|---|---|---|---|---|
| 1. First intro call | After a warm introduction or an LP inbound | 30 to 45 minutes | Tear sheet, 15 to 20 page deck | Strategy fit with their program, size fit, whether the team is worth a second meeting | A dated deep dive and data room access |
| 2. Investment deep dive | 1 to 4 weeks after the intro | 90 minutes to half a day | Deal-level track record, case studies including losses, completed DDQ | Investment process, track record attribution, team stability, alignment | References released and an ODD visit scheduled |
| 3. On-site operational due diligence | After investment team sign-off | Half a day to a full day | Policies, ADV, audits, service provider list, CFO, COO and CCO in the room | Valuation, cash controls, compliance, cyber, service providers | No open ODD findings before the LP’s investment committee |
| 4. Annual meeting (AGM) and LPAC | Once a year, usually after audited financials | Half a day to a full day | Portfolio review, valuations, fees, pipeline, in-camera session | Whether you report bad news as clearly as good news | Materials you would be comfortable sending to a Fund II prospect |
| 5. Re-up conversation | Before you launch the next fund | 45 to 90 minutes | Prior fund marks tied to audits, gross and net returns, Fund II term changes | Whether Fund I behaved as promised and what changed | A soft circle and an anchor for first close |
What you may say in an LP meeting: 506(b) vs 506(c)
Most private funds raise under Regulation D, and which rule you file under decides who you may meet and how they found you. Rule 502(c) bars offering or selling “by any form of general solicitation or general advertising,” and its examples include “any seminar or meeting whose attendees have been invited by any general solicitation or general advertising” (17 CFR 230.502(c)). Rule 506(b) keeps that ban and allows up to 35 non-accredited but sophisticated purchasers in any 90 day period, who must receive disclosure documents (SEC, Rule 506(b)). Rule 506(c) lifts the ban but requires that “all purchasers” are accredited and that you “take reasonable steps to verify” it (17 CFR 230.506(c)).
The SEC staff’s Securities Act Rules C&DIs set the practical lines for meetings:
- Relationship first, offering second (256.26, 256.29). Offering to someone with a “pre-existing, substantive relationship” is not general solicitation. “Pre-existing” means formed before the offering began, or through a registered broker-dealer or investment adviser before that firm joined the offering.
- “Substantive” means you evaluated them (256.31). You must have enough information to evaluate, and actually evaluate, the person’s financial circumstances and sophistication. “Self-certification alone (by checking a box)” is not enough.
- No waiting period (256.30). There is no minimum time, but the relationship must exist before the offering starts. Passing time alone does not create one (Question 148.01).
- Factual business information (256.25). You may talk widely about your firm and business, but factual business information generally excludes projections, and for a continuously offered fund it excludes “information about past performance of the fund.”
- Your website is a public channel (256.23). An unrestricted website with an offer of securities is general solicitation.
| Situation | Under 506(b) | Under 506(c) |
|---|---|---|
| Someone you met at a conference last week asks about Fund II | Talk about the firm, your strategy and market views. Do not discuss the live offering, terms or fund performance until a substantive relationship exists, and only if it predates the offering | You may discuss the offering. Nobody invests until accreditation is verified |
| LP introduced by their registered adviser | Can work if the adviser’s relationship predates its participation in your offering (256.29) | Fine; verification still required |
| Open-invite LinkedIn post for a fund briefing | General solicitation; the meeting itself becomes the problem | Permitted, with verification before acceptance |
| Prospect asks for your net IRR on a first call | Only inside a qualifying relationship, and subject to the performance rules below | Permitted, subject to the performance rules below |
If you plan group sessions, decide this before the first invitation goes out. Our guide to investor webinars and events for fund managers covers registration gates for both paths.
Showing performance in a meeting: the SEC Marketing Rule
If you are an SEC-registered adviser, the Marketing Rule, 17 CFR 275.206(4)-1, governs the deck and the numbers you put in front of prospective LPs. Exempt reporting and state advisers should ask counsel which parts reach them; antifraud rules apply either way. Five points matter in a meeting room:
- Talking is treated differently from slides. The definition of advertisement excludes “extemporaneous, live, oral communications,” and the adopting release (pages 38 to 39) says a phone call or live video can qualify. It also says prepared remarks delivered from scripts do not qualify, and slides “distributed or presented to the audience” can be advertisements. Your answers to questions are one thing. Your deck is another.
- One-on-one is narrower than it sounds. A communication to one person is generally outside the first prong, but the release says “customizing a template presentation or mass mailing by filling in the name of an investor” does not make it one-on-one. A pitch book with the LP’s logo on the cover is still your standard pitch book.
- Gross needs net beside it. Under paragraph (d)(1), any gross performance must come with net performance at least as prominent, over the same period, using the same type of return and methodology. The SEC’s Marketing Compliance FAQ (February 6, 2024) adds that “presenting only Net IRR that includes the impact of fund-level subscription facilities could mislead investors.” Show net IRR with and without the sub line. The DDQ asks for exactly that at question 7.9.
- Your best deal is extracted performance. A single deal case study is “a subset of investments extracted from a portfolio,” allowed only if you provide, or offer to provide promptly, the total portfolio’s performance (paragraph (d)(5)). The March 19, 2025 FAQ update lets you show gross extracted performance without a net figure for the extract when you prominently show the gross and net performance of the total portfolio, with clear labels and matching periods.
- Target returns are hypothetical performance. Results “not actually achieved by any portfolio” need policies tying them to the audience’s financial situation, plus disclosure of the criteria, assumptions, risks and limitations (paragraph (d)(6)). There is a carve-out: hypothetical performance given to a private fund investor in a one-on-one communication, or in response to an unsolicited request, is outside the first prong. That is how many managers answer DDQ question 4.23 (“What is the targeted return-profile threshold…?”) in a one-to-one setting, but get your CCO’s position in writing first.
Two more rules travel with you into every meeting. The 1, 5 and 10 year period requirement in (d)(2) applies to portfolios “other than any private fund,” so fund-level IRR tables do not need it. And prior-firm results fall under the predecessor performance conditions in (d)(7). The verification options for that history are in our guide to building a verified track record.
Meeting 1: the first intro call
The first meeting decides one thing: whether the LP spends more time on you. They are checking fit with their program before they check quality. Ask about them before you present. Grata’s five first-meeting questions are a good base: “Can you describe your program so I can better tailor this conversation?”, “What is the length of your investment process?” and “How often does your team commit to first-time managers?”
Agenda for a 40 minute intro call
- Minutes 0 to 5: their program, check size, pacing, and where emerging managers fit.
- Minutes 5 to 15: the thesis in one sentence, why this team, and why this market now.
- Minutes 15 to 25: how you source and decide, using one realized deal and one deal that went wrong.
- Minutes 25 to 35: their questions. Write down every objection word for word.
- Minutes 35 to 40: fund size, target close dates, and a dated next step.
Materials: a one-page tear sheet and the deck, sent after the call rather than screen-shared slide by slide. If you do not have these yet, our breakdown of fund marketing materials and who to hire to build them lists what each one must contain.
Pass test: you leave with a named next meeting on a calendar, data room access requested, and the LP’s process in writing (committee dates, who signs off). “Send me the deck” with no date is a polite no until proven otherwise.
Meeting 2: the investment deep dive
This is where the LP’s investment team works through the DDQ with you, usually after reading your answers. ILPA describes the DDQ as a “roadmap for further engagement with GPs.” So prepare from the questions, not from your deck. These are the sections and the specific questions that come up in the room:
| ILPA DDQ 2.0 section | What they will ask | What to bring |
|---|---|---|
| 3. Succession Planning / Key Persons | Has a “Key Person” event occurred in the last two predecessor funds (3.11)? What is the key person provision and what changed (3.12)? | Key person clause, a one-page succession note |
| 4. Investment Strategy | Control or minority preference and history (4.15); targeted gross IRR or multiple threshold and holding period (4.23) | Strategy page, CCO-approved answer on targets |
| 8. Investment Process; 9. Team | Who sources, who decides, use of third parties in diligence (8.7), background checks and references (9) | IC memo sample (redacted), deal-by-deal role attribution |
| 10. Alignment of Interests | GP commitment, carry split by partner | Commitment and carry table by individual |
| 14. Track Record | Excluded investments and why (14.4); 3 to 5 investments below 1.0x TVPI, “what went wrong, action taken” (14.5); benchmarks, with and without credit facility (14.6) | Full deal list in spreadsheet form, loss case studies, benchmark comparison |
| Appendix C. References | References at all portfolio companies in the last two predecessor funds, including “any displaced CEOs” | Reference list cleared in advance, LPAC and LP references |
Question 14.5 is the one emerging managers underprepare for. If you only have one fund, show the deals below cost and what you changed. An LP who finds a loss you did not mention stops trusting every number you did mention.
Pass test: no unanswered DDQ questions after the meeting, references released, and an ODD visit date.
Meeting 3: the on-site operational due diligence visit
Operational due diligence looks at how your firm runs, not what it buys. The reviewers want to meet the people who run cash, valuation and compliance, not just the investment partners. Put your CFO or fund administrator lead, COO and CCO in the room.
Before the visit, have every document from DDQ Appendix A (“Requested Documents”) ready in the data room. The ODD-relevant items include:
- Current LPA, plus a black-lined version against the predecessor fund
- Most recent Form ADV Parts 1 and 2
- All audited annual and unaudited quarterly reporting packages for each active predecessor fund over the last five years
- Compliance manual, conflicts of interest, personal trading, MNPI, whistleblower and risk management policies
- Any regulatory exam deficiency letter, such as an SEC deficiency letter
- Internal control reports (SSAE 18 or ISAE 3402), yours and your key third parties’
- Examples of capital call and distribution notices
Pass and fail checklist for the visit
| Area (DDQ section) | Pass | Fail |
|---|---|---|
| Valuation (15) | Written valuation policy, changes in the last five years explained (15.5), independent valuation firm or LPAC review stated (15.8, 15.9) | Marks set by the deal partner with no documented review |
| Administration (15.14) | Independent, unaffiliated fund administrator named, contract available | Spreadsheet NAV kept by the GP |
| Cash controls (my addition, not a DDQ section) | Two-person approval for wires, callback on bank changes, demonstrated live | One partner can release wires alone |
| Compliance (13) | Named CCO, manual dated within the year, exam letters disclosed | Policies exist but staff cannot describe them |
| Data security and third parties (18) | Service provider list with contract expiry dates (Appendix C3), cyber and information policy on file (1.29) | No list of who holds investor data |
| Reporting (16) | Sample quarterly package in ILPA format, delivery dates met | No sample; “we will build it after close” |
Pass test: the ODD team writes “no material findings” or a short remediation list with dates you have agreed. Once an LP soft commits, the paperwork phase starts; our LP onboarding checklist covers subscription documents, 506(c) verification and wire controls.
Meeting 4: the annual meeting and LPAC
Your annual meeting is a reporting event that turns into marketing material. DDQ 2.0 asks every manager whether there will be “an annual investor meeting throughout the life of the Fund” (2.9), whether LPAC meetings get an in-camera session (2.10), and the timing, format and whether minutes or recordings are available (2.11). Appendix A then asks for “Annual General Meeting materials for last two years” and “Presentation materials and minutes of all LPAC meetings held over the last two years.” Your Fund II prospects will read your Fund I AGM deck.
ILPA Principles 3.0 (June 2019) lists recommended LPAC agenda elements, and they make a strong AGM backbone:
- Firm update and market conditions, with the effect on strategy
- Fund dashboard on performance per company relative to original plan
- Portfolio company valuations and methodology over the last four quarters, to highlight changes
- Potential exits, timing and amounts, “preferably in writing”
- Detailed fund expenses, including payments to affiliates, and offsets
- Capital call line usage, and fund performance excluding the line
- Team changes, LPA compliance (concentration limits, key person), pipeline
- In camera, LP only session, plus an annual in camera discussion with the auditor
On compliance: the Marketing Rule release says presentations to existing investors about the performance of funds they already hold, “for example, at annual meetings of limited partners,” are not advertisements. That changes when you pitch Fund II from the stage, or invite prospects. Keep the new fund in a separate, counsel-reviewed session. A minute-by-minute run of show is in our LP annual meeting agenda template.
Meeting 5: the re-up conversation
Do not assume your Fund I LPs are your Fund II first close. In Coller Capital’s 41st Global Private Capital Barometer (December 2024), 79% of LPs had declined to re-invest with at least one current GP in the prior 12 months and 88% expected to do so in the next 12, from a survey of 107 investors (Hedge Fund Alpha coverage). In the 44th edition (June 2026), 23% of LPs expected to reduce their number of GP relationships over the next three years, up from 16% in 2020.
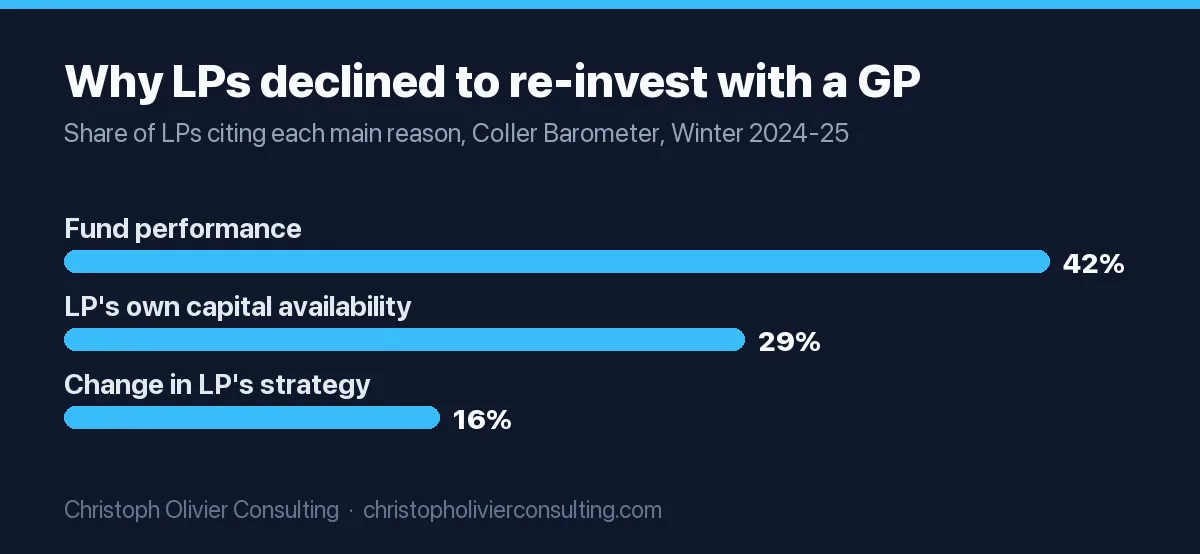
Only some of those reasons are yours to fix. Performance led at 42%, but 29% of declines came from the LP’s own capital availability and 16% from a change in the LP’s strategy. So the re-up meeting has two jobs: prove Fund I behaved as promised, and find out early whether the LP has room in its plan for you at all.
Principles 3.0 lists what Fund II marketing materials should include, and the re-up meeting is where an LP checks it against what you reported:
- Values for each unrealized company in prior funds, based on the most recent audited financials, with an explanation of any that deviate
- Gross and net performance of prior funds, including IRR, multiple and DPI, and how IRR was derived
- Pending or threatened litigation, agents and sub-agents used, valuation policy and subscription line policy
Open the conversation with your current LPs before the new deck exists, ideally at or right after the AGM, and ask directly: “What would make Fund II an easy yes for your committee, and what would make it hard?” Our guide to LP retention and reporting covers the quarterly reporting that makes that conversation short.
Copy-ready LP meeting agenda and follow-up email
Send the agenda two business days before the first meeting. It signals that you respect their process and it lets them bring the right colleague.
Pre-meeting email
Subject: [Fund name] and [LP name]: agenda for [day, date, time, time zone]
Hi [first name],
Thank you for making time on [date]. So we use the 40 minutes well, here is a proposed agenda:
1. Your program: check size, pacing and how you approach [emerging / sector] managers (5 min)
2. Our strategy and team in brief (10 min)
3. How we source and decide, with one realized deal and one that did not go to plan (10 min)
4. Your questions (10 min)
5. Timeline and next steps (5 min)If there is something you would like us to cover in depth, or a colleague who should join, reply and I will adjust. Dial-in: [link].
[Name], [title], [direct line]
Follow-up email, within one business day
Subject: [Fund name]: follow-up from [date] and next step on [date]
Hi [first name],
Thank you for the conversation. Three things I heard that matter to your committee: [priority 1 in their words], [priority 2], [priority 3].
Answers to the questions I owed you:
[Question 1]: [answer, two sentences, linked document]
[Question 2]: [answer]As requested, I have attached [only what they asked for] and opened data room access for [names]. Our completed ILPA DDQ is in folder [X].
Proposed next step: a deep dive with [partner names] on [date options], focused on [their stated focus]. Our first close is targeted for [date]; I mention it only so you can plan, not to rush your process.
[Name]
If you are raising under 506(b), send this only inside a qualifying relationship, and have your CCO approve any performance figures before they go into the email. More variants, including a nudge after diligence goes quiet, are in our investor meeting follow-up templates.
Pipeline tracker: stages, exit criteria and the math
Track every LP by stage, with a written exit criterion for each stage, in your CRM. The conversion rates below are illustrative assumptions for planning, not industry data. Replace them with your own numbers after the first 30 meetings.
| Stage | Exit criterion (move only when true) | Assumed conversion to next stage |
|---|---|---|
| Target list | Program fit checked: check size, strategy, emerging manager appetite | 30% get a first meeting |
| First meeting held | Dated deep dive and data room access | 40% |
| Deep dive done | DDQ complete, references released, ODD date set | 60% |
| ODD complete | No open findings; investment committee date known | 60% |
| Soft circle | Amount and close named in writing | 85% |
| Closed | Countersigned subscription, funded | n/a |
Worked example. You are raising $50 million with an average commitment of $2 million, so you need 25 closed LPs. From first meeting to close, the assumed rates multiply to 0.40 x 0.60 x 0.60 x 0.85 = 0.1224, about 12%. That means 25 / 0.1224 = about 204 first meetings, and at a 30% meeting rate, about 681 targeted LPs. If you can hold eight first meetings a week, 204 meetings is about 26 weeks of meetings alone, before diligence time.
Two levers move that math more than better pitching. Raising the average check from $2 million to $3 million cuts the required LPs to 17 and the first meetings to about 139. Raising deep-dive-to-ODD conversion from 60% to 75%, usually by having the DDQ finished before the first meeting, cuts first meetings needed at a $2 million check to about 163.
If you want a second set of eyes on your meeting sequence and materials before the first LP sees them, you can book a consultation.
Frequently asked questions
What happens in a fund manager meeting with an LP?
It depends on the stage. A first intro call (30 to 45 minutes) tests fit with the LP's program. The deep dive works through the ILPA DDQ: track record, team, process and alignment. The on-site operational due diligence visit reviews valuation, compliance and controls. The annual meeting reports to existing LPs, and the re-up conversation decides whether they back your next fund.
How should I prepare for a first meeting with an LP?
Research their program first: check size, pacing and appetite for emerging managers. Send a five-part agenda two business days ahead, bring a tear sheet and deck, and prepare one realized deal and one loss. Ask how their process runs and leave with a dated next meeting, not just a request for the deck.
Can I discuss my fund with an investor I just met under Rule 506(b)?
Not the live offering. Under 506(b) you need a pre-existing, substantive relationship, formed before the offering began, in which you actually evaluated the person's finances and sophistication. Box-ticking self-certification is not enough. You can discuss your firm and views. Under 506(c) you may discuss the offering but must verify accreditation. Confirm with fund counsel.
Can I show target returns or gross IRR in an LP meeting?
For SEC-registered advisers, gross performance needs net performance beside it with equal prominence, same period and method. Target returns count as hypothetical performance and need policies plus disclosed assumptions and risks, though one-on-one communications with a private fund investor are carved out of the first prong. Get your CCO's sign-off first.
What documents do LPs ask for before an operational due diligence visit?
ILPA DDQ 2.0 Appendix A lists them: the current LPA and a black-line against the predecessor fund, Form ADV Parts 1 and 2, five years of audited and quarterly reports, compliance, conflicts, trading and whistleblower policies, any SEC deficiency letter, SSAE 18 or ISAE 3402 reports, and sample capital call and distribution notices.
What should a fund's annual LP meeting cover?
ILPA Principles 3.0 suggests a firm and market update, performance per company against plan, four quarters of valuations and methodology, exit plans, detailed fees and expenses with offsets, subscription line usage and performance without it, team changes, LPA compliance, pipeline, and an LP-only in camera session. Keep any Fund II pitch in a separate session.
When should I start the re-up conversation with existing LPs?
Before your next fund's deck exists, ideally at or soon after the annual meeting. In Coller Capital's December 2024 Barometer, 79% of LPs had declined to re-up with at least one GP in the prior year, and 29% of declines came from the LP's own capital limits, so ask early whether they have room for you.
More marketing guides for capital raisers
- Marketing Channels for Fund Managers and Capital Raisers
- Video Content for Fund Managers Without Breaking Solicitation Rules
- LP Retention: Reporting and Communication for Fund Managers
- Investor Onboarding for Fund Managers That Builds Trust and Re-Ups
- Marketing Calendar for Fund Managers: An Investor-Communication Cadence
- The Marketing and CRM Tech Stack for Fund Managers and Capital Raisers
- Marketing for Capital Raisers & Fund Managers