
To convert calls to consultations at an accounting firm, do three things on every inquiry: reach the person within 5 minutes, qualify them in about four minutes on fit, need, budget and timing, and book the consultation on a calendar before the call ends. Then turn consultations into signed engagements with a fixed 30-minute agenda that ends in a fee range, a proposal sent the same day, and a decision meeting already booked.
Below is the whole playbook in the order a prospect experiences it: a copy-ready phone and callback script, a pass/fail qualification matrix, the speed-to-lead numbers that justify the 5-minute rule, the booking stack with verified USD prices, the math on free versus paid consultations, a reminder sequence that cuts no-shows, the consultation agenda minute by minute, the engagement-letter handoff with the AICPA and Circular 230 rules that apply, and the two conversion rates to track, with formulas.
Phone intake script: first 60 seconds, qualifying questions, booking close
Whoever answers the phone (front desk, client-services lead, or a partner in a small firm) runs the same script. It takes 4 to 6 minutes. Its only job is to decide whether to book a consultation, and with whom. It does not answer the tax question.
The first 60 seconds of an inbound call
0:00. “Thanks for calling [Firm], this is [Name]. Are you a current client, or looking for help for the first time?”
Current clients go to their manager’s line or a message ticket. New prospects stay with you.
0:10. “Glad you called. In case we get cut off, what’s your name and the best number to reach you?”
Get the name and number before anything else. A dropped call without a number is a lost lead.
0:20. “So I get you to the right person, can I ask you four quick questions? It takes about three minutes.”
0:30. “What’s going on that made you call us today?”
Then stop talking. The answer is the trigger: an IRS letter, a new S corporation, a bookkeeper who quit, a business sale, a prior return they do not trust, a move to a new state. Write it down in the caller’s own words. It becomes the subject line of the confirmation email and the first sentence of the consultation.
The four qualifying questions (minutes 1 to 4)
- Fit: “Is this for you personally, for a business, or both? If a business, what type of entity is it, and roughly how much revenue does it do in a year?”
- Need: “What would you want us to take off your plate: the tax returns, the monthly books, planning for next year, or something specific like that letter?” If an IRS or state notice is involved: “What’s the date on the letter, and what does it ask for?”
- Timing: “When does this need to be handled by? Is there a filing deadline, a lender, or a buyer waiting on it?”
- Budget: “So you’re not surprised later: for a [business return like yours], our fees usually run $[X] to $[Y] a year, depending on how clean the books are. Is that roughly in the range you expected?”
Add one more if a business is involved: “Is anyone else involved in choosing an accountant, like a business partner or spouse?” If yes, invite them to the consultation now. The consultation that loses to an absent decision maker was lost on this call.
Why ask budget on the phone: a fee range given early is the cheapest filter you have. Stating it is allowed. Circular 230 section 10.30(b) lists fixed fees, hourly rates, fee ranges and the “fee charged for an initial consultation” as fee information a practitioner may publish. The limit comes from the AICPA Code, interpretation 1.600.010.02(c): quoting a fee range is misleading if it was likely the fee would be substantially higher and you did not say so. That is why the script says “depending on how clean the books are.”
The booking close
“Based on what you’ve told me, the next step is a 30-minute consultation with [Partner], who works with [S corporations / rental owners / contractors] every week. I have Tuesday at 10:00 or Wednesday at 2:00. Which works better?”
Offer two specific times, not “when are you free?” Then, while they are still on the line:
“I’m sending the confirmation to your phone and email right now. It has a short form and an upload link. If you can upload last year’s return before Tuesday, [Partner] will review it first, so the 30 minutes goes to your questions instead of paperwork. Did the text come through?”
Wait for the yes. A booking the prospect has seen arrive is a booking they remember.
Callback script for a web form or a missed call
Call within 5 minutes during business hours. Open with what they sent, not with who you are:
“Hi [Name], it’s [Name] from [Firm]. You just sent us a note about [the S corporation election / an IRS notice]. Have you got three minutes now, or is later today better?”
Then run the four questions and the booking close above. If you reach voicemail, leave 20 seconds and send a text immediately after:
“Hi [Name], this is [Name] at [Firm] about your [IRS letter] question. You can book 30 minutes with [Partner] here: [link]. Or reply with a good time and I’ll call you.”
Try again later that day, then on days 2, 4 and 7. Six attempts is a sensible cap: in Velocify’s data of almost 3.5 million leads, 93% of converted leads were reached by the 6th call.
When the caller is not a fit
“I want to be straight with you: we’re not the right firm for [a single W-2 return / a payroll-only service]. [Named firm or resource] will serve you better and cost less. Can I text you their details?”
Saying no quickly protects partner hours, and a polite referral is often remembered by the person who sent the caller to you.
Qualification matrix: fit, need, budget, timing with pass/fail rules
Score each answer while you are on the call. The pass and fail lines below are my recommended defaults, not industry standards. Replace the bracketed values with your own service menu and fee floor.
| Criterion | Pass | Unclear | Fail and route |
|---|---|---|---|
| Fit (who they are) | Entity type, size and state are on your service list and in a niche you serve | Edge of your niche, or a state you rarely file in | Work you do not offer (audit, payroll only, a country you do not file in): refer out |
| Need (what they want done) | Names a deliverable and a reason: a notice, a new entity, a sale, recurring books, planning before year end | “Looking for a new accountant,” no trigger yet | Wants a free answer to one question with no engagement: send your published consultation option |
| Budget (fee range) | Accepts the range you stated, or asks what drives it | “Depends,” or needs to check with a partner | Anchors below your floor, for example wanting a business return for a few hundred dollars: refer out |
| Timing (when) | Can start inside your current capacity window | Deadline falls inside your busy-season intake cutoff | Needs work you cannot staff before their deadline: offer the first slot after it, or refer |
| Decision (who signs) | Caller decides, or the other decision maker is invited to the consultation | Other decision maker known but not invited | Caller is gathering quotes for someone who will not talk to you: send information only |
Routing rule: book the consultation when Fit and Need pass and no more than one other line is Unclear. Two or more Unclear lines get a 15-minute fit call first. Any Fail gets the route in the last column, the same day.
Sanity check for your budget line: the most common fees reported in Ignition’s 2025 benchmark of 219 US firms using its software were $400 to $599 per individual return, $1,000 to $1,499 per business return, more than $2,000 a year for tax planning and advisory, $250 to $499 a month for bookkeeping, and more than $2,500 a month for CFO and controller work. If a caller’s expectation sits far below the band for their work, the call is usually over, however friendly it is. How to build the actual fee tiers is covered in our guide to proposals and pricing presentation for accounting firms.
For the deeper question list to use once someone is booked, see our discovery call questions for accounting firms.
How fast to call back: the speed-to-lead numbers that apply
These are the figures that hold up when traced to the original studies. Quote the outcome each one measured.
| Finding | What was measured | Source |
|---|---|---|
| Odds of contacting a web lead drop 100 times, and odds of qualifying it drop 21 times, when the first call comes at 30 minutes instead of 5 | Contact and qualification. “This study did not address close ratios.” | MIT and InsideSales.com Lead Response Management study, 2007 (6 companies, 15,000+ leads, 100,000+ call attempts) |
| Firms that tried to reach a lead within an hour were nearly 7 times as likely to qualify it as firms that tried an hour later, and more than 60 times as likely as firms that waited 24 hours or more | Qualification, defined as “a meaningful conversation with a key decision maker” | Harvard Business Review, March 2011 (1.25 million leads, 42 US companies) |
| 23% of 2,241 US companies never responded to a test lead; the average response was 42 hours | Response time | Harvard Business Review, March 2011 |
| Two thirds of companies never replied to a demo or contact form, 96% never called, and 5% of replies arrived within five minutes | Response to 6,346 test forms | Clay, September 2026 |
None of these studies looked at accounting firms specifically, and none measured signed engagements. What they show is that a lead you reach in minutes is far more likely to turn into a real conversation, and that most businesses are slow enough that a fast firm stands out. Every number above, with its caveats, is traced in our speed to lead statistics roundup.
A response standard that fits an accounting firm, adapted from those findings:
- Inbound calls: answered live during business hours. If the line is busy, the caller gets a text with a booking link and a human callback within 5 minutes.
- Consultation or callback forms: an automated confirmation with your booking link at once, and a human call within 5 minutes during business hours.
- After hours: the same automatic text and email with the booking link, then a call within the first hour of the next business day.
- February to mid-April: keep the 5-minute callback even if the consultation itself is booked for a date after your busy-season cutoff. A fast “we’ll meet you on April 22” beats silence until April 22.
The booking stack: scheduling tools and practice-management intake, priced in USD
You need three things: a scheduling link that books into a partner’s real calendar, automated reminders, and a place for intake answers and documents to land. Prices below were checked on each vendor’s own US pricing page in late October and early November 2026.
| Tool | Plans and USD prices | What matters for consultations |
|---|---|---|
| Calendly | Free; Standard $10 per seat per month; Teams $16 per seat per month (yearly billing); Enterprise from $15,000 a year, 50-seat minimum | Standard adds automatic reminders, a cancellation policy, HubSpot integration and Stripe or PayPal payment at booking. Routing forms and round robin are on Teams |
| Acuity Scheduling | Starter $16 (annual) or $20 (monthly); Standard $27 or $34; Premium $55 or $69 per month | Intake forms and payments (Stripe, Square, PayPal, Venmo) on all plans. Text reminders start on Standard. Calendars: 1, up to 6, up to 36 |
| HubSpot Meetings (in Sales Hub) | Free for up to 2 users; Starter shown at $7 and $20 per seat per month depending on billing period, with discounts for new customers only; Professional $90 and $100 per seat per month plus a $1,500 one-time onboarding fee | Free includes 1 personal meetings link with HubSpot branding. Paid plans include 1,000 personal and team meetings links without branding |
| Chili Piper | Growth from $1,250 a month, including 15 seats, then $45 per seat per month; all plans billed annually; ChiliCal standalone $12 per user per month with a 200-seat minimum | Instant booking from a web form with routing to the CRM owner. Priced for sales teams, not a 5-partner firm |
| TaxDome | Essentials $800 per seat a year (1-year term, solo users only); Pro $1,000; Business $1,200 | Intake forms (organizers) unlimited on all plans; proposals and payments from Essentials. Lists Calendly, Schedulista, Squarespace and Youcanbook.me as scheduler integrations |
| Karbon | Team $59 per user per month annual or $79 monthly; Business $89 or $99; Enterprise custom. Monthly billing only for teams of 4 or more | Client portal on all plans; Engagements listed on Team. No built-in scheduler listed on the pricing page |
| Canopy | Standard $74, Plus $109, Premium $149 per user per month, billed annually | Questionnaires and organizers listed as a feature (plan not stated); client portal, eSign and payments on Standard. No booking feature listed |
How to choose: for most small and midsize firms, Calendly Standard or Acuity Standard is enough. Pick Acuity if you want text reminders and payment collection in one low-cost plan. Pick Calendly Teams once two or more people take consultations and you want routing and round robin. HubSpot’s free meetings link works if HubSpot is already your CRM. Chili Piper’s pricing makes sense only for a large firm with a dedicated sales team. Whichever scheduler you choose, send the confirmed booking into your practice-management system so the intake form and document upload are waiting in the client’s portal. The full intake form for tax clients, and the rule that prospects should never be asked for Social Security numbers before they sign, are in our client questionnaire template for tax planning firms.
Set up three event types, not one:
- 15-minute fit call (free): for prospects with two or more Unclear lines in the matrix. Taken by a manager, not a partner.
- 30-minute consultation: for qualified prospects. Required booking questions: entity type, what they need, deadline, and “anything we should read before the call?” Add a 15-minute buffer after it for notes.
- 60-minute paid planning session: for one-time advisory questions. Collect payment at booking.
The exact Calendly settings for buffers, minimum notice and invitee questions are walked through in our discovery call guide for coaches and consultants; the same settings apply to an accounting firm.
Free or paid consultation? Worked math
A paid consultation filters out people who only want a free answer and frees partner hours. A free one books more people. Which wins depends on your average fee and how scarce partner time is. Here is the comparison for one month, with every input labeled as an assumption you should replace with your own numbers.
| Line | Free 30-minute consultation | $300 consultation, credited to the first invoice |
|---|---|---|
| Consultations booked (assumption) | 20 | 10 |
| Show rate (assumption) | 75%: 15 held | 90%: 9 held |
| Partner hours at 45 minutes each (30 minutes plus prep and notes) | 11.25 | 6.75 |
| Signed (assumption) | 1 in 3: 5 clients | 1 in 2: 4.5 clients |
| Consultation fees kept from people who do not sign | $0 | 4.5 x $300 = $1,350 |
| Value of partner hours freed, at an assumed $250 an hour | n/a | 4.5 hours x $250 = $1,125 |
The paid model gains $1,350 + $1,125 = $2,475 a month and loses 0.5 signed client. So the break-even rule is:
Charge for the consultation when (signed clients lost x average first-year fee) is less than (fees kept from non-signers + value of partner hours freed).
- Recurring compliance client at an $8,100 first-year fee (the compliance tier in our proposals guide): 0.5 x $8,100 = $4,050, which is more than $2,475. Keep the consultation free.
- One-time planning engagement at $2,500: 0.5 x $2,500 = $1,250, which is less than $2,475. Charge for it.
- In February to April, when a partner hour might be worth $400 to you instead of $250: hours freed are worth $1,800 and the gain is $3,150. More engagements cross the line, so a paid session for new prospects in busy season is easier to justify.
Two rules if you charge. First, if you publish the fee on your booking page, Circular 230 section 10.30(b)(2) says you may charge no more than the published rate for at least 30 calendar days after it was last published, so change it deliberately, not mid-season. Second, credit the fee toward the engagement, but never refund it based on the tax savings you find. “Free if we don’t find you savings” makes the fee depend on the result, which is the definition of a contingent fee in both Circular 230 section 10.27(c)(1) and AICPA rule 1.510.001.03.
Cutting no-shows: the reminder sequence
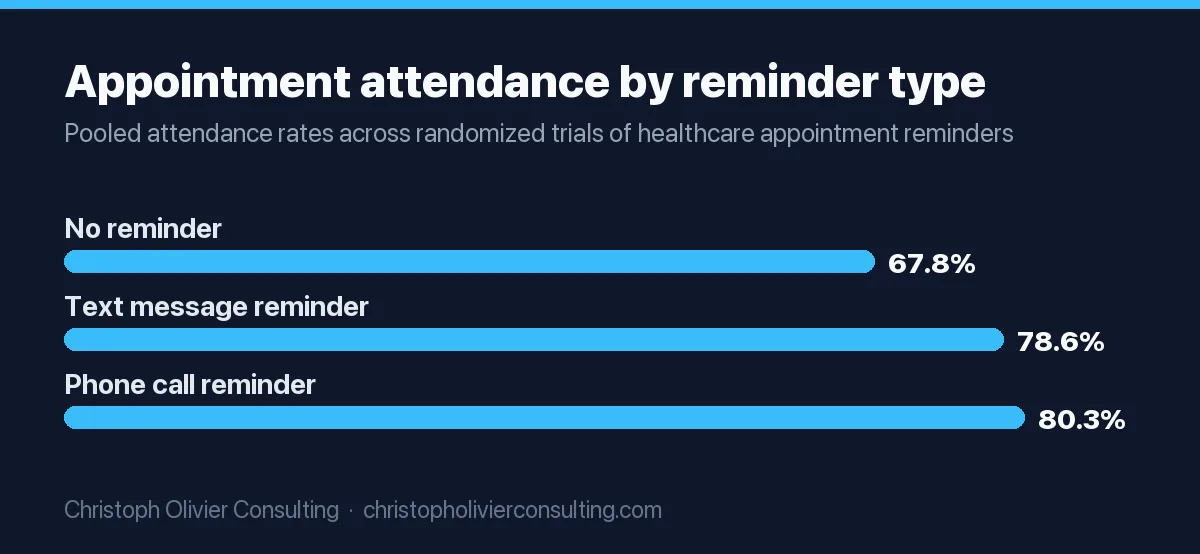
There is no large, independent study of no-show rates for accounting consultations, so do not trust a vendor’s “average no-show rate” for your planning. The best controlled evidence on reminders comes from healthcare appointments. A 2013 Cochrane review found moderate quality evidence from seven randomized trials (5,841 participants) that text reminders improved attendance compared with no reminders (risk ratio 1.14), and three trials (2,509 participants) showing texts performed about the same as phone call reminders. Medical appointments are not sales meetings, so take the direction, not the exact percentages.
A sequence built for an accounting consultation (timings are my recommendation):
| When | Channel | Message |
|---|---|---|
| On booking | Text and email | Confirmation with date, partner’s name, video link or address, and the upload link for last year’s return |
| 48 hours before | “[Partner] reviews your return before the call. Upload it here by tomorrow so the 30 minutes goes to your questions.” Include a reschedule link | |
| 24 hours before | A three-line agenda: what you’ll review, the questions you’ll ask, and that you’ll give a fee range at the end | |
| 2 hours before | Text | “Hi [Name], [Partner] at [time] today. Reply 1 to confirm or use this link to move it: [link]” |
| 10 minutes after a no-show | Call, then email | “Looks like today didn’t work. Here are two new times, or book here: [link].” One attempt, then one email two days later |
The 48-hour upload request does double duty: a prospect who uploads a return has committed effort, and your partner walks in prepared. If a prospect tells you they are not interested, stop. Circular 230 section 10.30(c) says a practitioner may not keep trying to contact a prospective client who has made it known they do not want to be solicited.
The 30-minute consultation agenda, minute by minute
The consultation has one goal: agree on a scope and a fee range, and book the decision. It is not a free review of their whole return.
| Clock | Block | What you say or do |
|---|---|---|
| 0:00 to 2:00 | Confirm and set the agenda | “We have 30 minutes. I’ll ask about the business, share what I saw in the return you uploaded, and at the end I’ll tell you what I’d recommend and what it costs. If we’re not the right fit, I’ll say so.” |
| 2:00 to 10:00 | Situation | Entity, owners, revenue, states, who does the books, what the current preparer does and does not do, and the trigger from the phone notes, in their words |
| 10:00 to 17:00 | What you found | Two or three specific observations from the uploaded return or notice, for example an owner salary that looks low for an S corporation or estimated payments that did not match the tax owed. Name the issue; save the fix for the engagement |
| 17:00 to 21:00 | Put a number on it | Ask for their numbers: hours a month they spend on finance, penalties paid, the lender or buyer deadline. These are the figures your proposal will quote back |
| 21:00 to 26:00 | Recommend scope and fee range | “Based on this, I’d recommend [scope]. That runs $[X] to $[Y] a year. The written proposal will show three options.” Confirm who signs and the deadline |
| 26:00 to 30:00 | Book the decision | “You’ll have the proposal by [5 pm today]. Let’s hold 15 minutes on [Thursday] to answer questions and decide.” Send the invite before you hang up |
Two things to avoid in the 21:00 block. Do not promise savings or a refund amount; AICPA interpretation 1.600.010.02(a) treats promotion that creates “false or unjustified expectations of favorable results” as misleading. And do not quote a range you already suspect will rise once you see the books, unless you say so.
Handing off to the proposal and engagement letter
Most firms lose more signed engagements between the consultation and the signature than on the call itself. Keep the handoff short and scheduled:
- Same day: send the proposal with three options, built from the numbers they gave you. The template, tier math and pricing benchmarks are in the proposals and pricing guide linked above.
- Signature and payment together: the proposal becomes the engagement letter. Collect the e-signature and the ACH or card authorization in the same step; TaxDome, Karbon and Canopy all bundle proposals or engagements with payments.
- Separate consent for other uses of tax data: if you will use return information for anything beyond preparing the return, such as offering planning or sharing with an advisor, get the separate written IRC 7216 consent first. The required wording is in the client questionnaire template linked above.
- Decision meeting: already booked from the consultation. If it slips, follow up on day 1, 3, 7, 12 and 21 with our proposal follow-up email templates, then close the file.
- Kickoff: once signed, the portal invite, organizer and document checklist go out within one business day.
The fee rules that most often affect what you say between the call and the signature:
| Rule | What it says | What it means for your consultation process |
|---|---|---|
| AICPA 1.510.001, Contingent Fees Rule | A member may not prepare an original or amended tax return or claim for a tax refund for a contingent fee for any client | No “percentage of your refund” pricing, and no consultation fee refunded only if you find savings |
| Circular 230, 31 CFR 10.27 | Contingent fees generally barred for matters before the IRS, with exceptions for examinations, certain interest and penalty claims, and judicial proceedings. A 2014 court ruling, Ridgely v. Lew, barred the IRS from applying it to ordinary refund claims | Price exam or notice representation separately; the AICPA rule above still applies to CPA members |
| Circular 230, 31 CFR 10.30(b) | Fee ranges and initial consultation fees may be published; published rates hold for at least 30 calendar days | Your phone script range and booking-page fee are fine, but changing them is a decision, not an edit |
| Circular 230, 31 CFR 10.30(c) | No persistent contact after a prospect says they do not want to be solicited; keep copies of direct mail and e-commerce communications for 36 months | Stop follow-ups on a “no,” and keep your reminder and follow-up templates on file |
| AICPA 1.600.010.02 | Promotion is misleading if it creates unjustified expectations of favorable results or quotes a fee that was likely to rise substantially without saying so | No promised savings on the call; say what could change the fee |
The AICPA quotes are from the Code of Professional Conduct updated through July 2026. State boards can be stricter. This is general guidance, not legal advice.
KPIs: call-to-consult rate and consult-to-engagement rate, with formulas
I have not found a published, independent benchmark for accounting firms’ call-to-consultation or consultation-to-engagement rates, so measure your own baseline for one quarter before you set targets. These are the numbers to pull each month:
| KPI | Formula | What a low number points to |
|---|---|---|
| Answer rate | New-prospect calls answered live ÷ new-prospect calls received | Phone coverage, especially at lunch and in busy season |
| Speed to lead | Median minutes from form or missed call to first human call | Routing and ownership, not effort |
| Call-to-consult rate | Consultations booked ÷ qualified new-prospect calls and forms (exclude existing clients, vendors and spam) | The intake script, the booking close, or slow callbacks |
| Show rate | Consultations held ÷ consultations booked | Reminders, booking too far ahead, no upload request |
| Consult-to-engagement rate | Engagements signed ÷ consultations held | The agenda, the fee range, or proposals that go out late |
| Proposal turnaround | Median business days from consultation to proposal sent | Partner bottleneck on proposal writing |
| Revenue per consultation | New first-year fees signed ÷ consultations held | Whether the free versus paid decision above is still right |
Worked example with hypothetical numbers. In one month a firm gets 80 new-prospect calls and forms, and 60 of them are qualified. It books 24 consultations (24 ÷ 60 = 40% call-to-consult rate), holds 20 (20 ÷ 24 = 83% show rate) and signs 8 (8 ÷ 20 = 40% consult-to-engagement rate). At an average first-year fee of $8,100, that is $64,800 in new fees, or $64,800 ÷ 20 = $3,240 per consultation held. If the reminder sequence raised the show rate to 90%, the firm would hold about 21.6 consultations a month and, at the same 40% close rate, sign about 8.6 clients: roughly two extra clients every three months, or about $5,200 a month in new first-year fees on average. That is the kind of single-stage change to test, one at a time, so you know which fix worked.
Fix the stage with the biggest drop first. These numbers also feed the funnel math in our marketing plan for accounting firms, where a revenue goal becomes the number of consultations a month your partners need to hold. If you want a second pair of eyes on your intake script and booking flow, you can book a consultation.
Frequently asked questions
How do you convert calls to consultations at an accounting firm?
Reach every new caller or form fill within 5 minutes, ask four qualifying questions on fit, need, budget and timing, then offer two specific consultation times and book one before you hang up. Send the confirmation by text and email while the caller is still on the line, with an upload link for last year's return, and follow it with reminders at 48 hours, 24 hours and 2 hours.
What should an accounting firm say in the first 60 seconds of a new client call?
Ask whether they are a current client or new, take their name and number in case the call drops, ask permission for four quick questions, then ask what made them call today. Write the trigger down in their own words, such as an IRS letter or a new S corporation, because it becomes the subject of your confirmation email and the opening of the consultation.
Should accountants charge for an initial consultation?
It depends on your average fee and how scarce partner time is. In the worked example on this page, a free consultation wins for recurring clients worth about $8,100 a year, while a paid session wins for one-time planning work around $2,500. If you charge, credit the fee toward the engagement and never refund it based on savings found, which would make it a contingent fee.
Can a CPA quote a fee range on the phone before a consultation?
Yes. Circular 230 section 10.30 lets practitioners publish fee ranges and the fee for an initial consultation, and published rates must hold for at least 30 days. Under AICPA interpretation 1.600.010.02, a range is misleading if a substantially higher fee was likely and you did not say so, so add what could change it, such as the state of the books.
How do you reduce no-shows for accounting consultations?
Send a confirmation by text and email at booking, an upload request 48 hours before, a short agenda 24 hours before, and a text 2 hours before with a reschedule link. A 2013 Cochrane review of healthcare appointments found text reminders raised attendance compared with no reminders and worked about as well as phone calls. If someone no-shows, call once within 10 minutes, then email.
How do you calculate call-to-consult and consult-to-engagement rates?
Call-to-consult rate is consultations booked divided by qualified new-prospect calls and forms, excluding existing clients, vendors and spam. Consult-to-engagement rate is engagements signed divided by consultations held, not booked. Track show rate separately as held divided by booked, so you can tell whether a drop comes from intake, reminders or the consultation itself.
How long should a sales consultation for an accounting firm be?
Thirty minutes works for most new-client consultations: 2 minutes to set the agenda, 8 on their situation, 7 on what you found in the return they uploaded, 4 to quantify the problem, 5 to recommend a scope and fee range, and 4 to book the decision meeting. Use a separate free 15-minute fit call for prospects who are not yet qualified.
More marketing guides for cpa
- Marketing Tech Stack for CPA and Accounting Firms
- Strategic Partnerships and Referral Networks for CPA and Accounting Firms
- How to Build a Marketing Plan for a CPA or Accounting Firm
- Marketing Channels for CPA and Accounting Firms: How to Build the Mix
- Video Marketing for CPA and Accounting Firms
- Podcast Strategy for CPA and Accounting Firms
- Marketing for CPA & Accounting Firms