
The SEC has brought 32 enforcement actions charging violations of the amended Investment Adviser Marketing Rule (Advisers Act Rule 206(4)-1) since the rule’s November 4, 2022 compliance date, with $4,570,000 in disclosed civil penalties. We built this tracker by reading every SEC administrative order with an Advisers Act release number published from November 4, 2022 to November 10, 2026, plus every SEC litigation release through November 12, 2026. Nineteen of the 32 actions involved hypothetical performance, most of it posted on a firm’s public website.
Short answer: From August 2023 to November 12, 2026 the SEC charged 32 Marketing Rule cases: 31 settled administrative orders and 1 federal court case settled by consent. Disclosed civil penalties total $4.57 million, with a median of $90,000 and a range of $20,000 to $850,000. Hypothetical performance shows up in 19 actions, unsubstantiated or misleading claims in 14, testimonials and endorsements in 4 and third-party ratings in 4. The most recent action in our data is dated September 4, 2025.
SEC Marketing Rule enforcement by the numbers
Every figure below comes from the SEC orders and releases linked in the full tracker further down. Settled orders are entered “without admitting or denying” the findings, and the Titan order notes that settled findings “are not binding on any other person or entity.”
| Metric | Value | Note |
|---|---|---|
| Enforcement actions charging the amended Marketing Rule | 32 | 31 settled administrative orders, 1 civil action (Black Dragon, S.D. Fla.) |
| Separate firms named | 32 actions, 33 firms plus 1 individual | Black Dragon case named two affiliated advisers and their CEO |
| Total civil penalties disclosed | $4,570,000 | 31 actions with a stated amount; Black Dragon amount not stated in SEC release |
| Median civil penalty | $90,000 | Mean $147,419 |
| Smallest penalty | $20,000 | InSight Securities and Bradesco Global Advisors (both reduced for corrective steps, per SEC press release 2024-46) |
| Largest penalty | $850,000 | Titan Global Capital Management, plus $192,454 disgorgement and $7,598 prejudgment interest |
| Actions announced in group batches | 23 of 32 | Sept. 11, 2023 (9 firms), April 12, 2024 (5), Sept. 9, 2024 (9) |
| Actions involving hypothetical performance | 19 (59%) | 14 of them charged only Rule 206(4)-1(d), median penalty $55,000 |
| Actions with a “conflict-free” style claim | 5 | AZ Apice, Droms Strauss, Integrated Advisors, Callahan, Meridian |
| First action | Aug. 21, 2023 | Titan (firm had elected early compliance with the amended rule) |
| Most recent action in the data | Sept. 4, 2025 | Meridian Financial; none found from Sept. 5, 2025 to Nov. 12, 2026 |
For scale: our State of RIA Websites 2026 study counted 17,263 SEC-registered advisers on the roster dated November 2, 2026, so the 32 public actions are a thin slice of the firms subject to the rule. This count covers public enforcement actions only; examination deficiencies are described by the SEC only in aggregate, through risk alerts. If you want the wider market context, our RIA industry statistics page covers firm counts and assets.
Marketing Rule actions and fines by year
Enforcement clustered in 2024. No action in our data charged the amended rule in November or December 2022, and the first case came nine months after the compliance date.
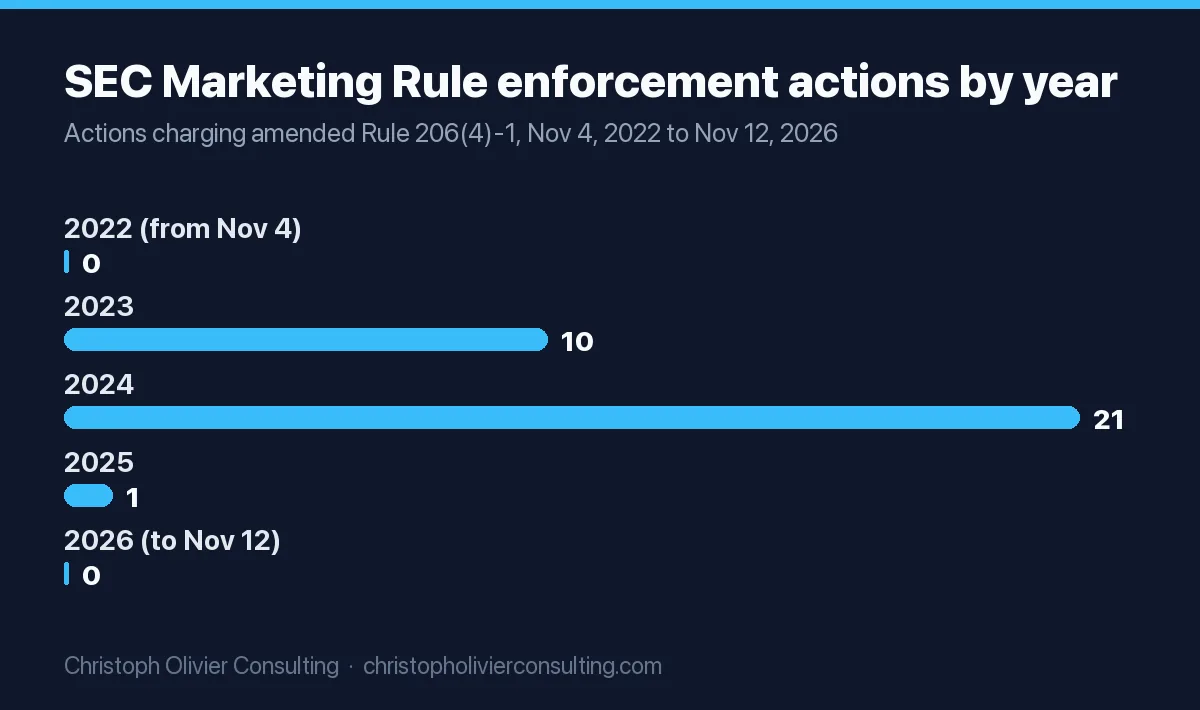
| Year | Actions | Total civil penalties | Median penalty | What happened |
|---|---|---|---|---|
| 2022 (from Nov. 4) | 0 | $0 | n/a | Compliance date Nov. 4, 2022 |
| 2023 | 10 | $1,700,000 | $92,500 | Titan (Aug. 21) and the Sept. 11 hypothetical-performance sweep |
| 2024 | 21 | $2,795,000 | $95,000 | AI-washing pair (March 18), April 12 actions, Sept. 9 sweep, Wahed, Atlas, Black Dragon |
| 2025 | 1 | $75,000 | $75,000 | Meridian Financial (Sept. 4) |
| 2026 (to Nov. 12) | 0 | $0 | n/a | No new actions found; FAQ update Jan. 15, 2026 |
2024 penalties include 20 actions with a stated amount; the Black Dragon consent judgment’s penalty is not stated in the SEC litigation release.
The three Marketing Rule sweeps, verified
The SEC announced 23 of the 32 actions in three batches. Two press releases use the word “sweep” directly.
| Date | SEC release | Firms | Combined penalties | Theme |
|---|---|---|---|---|
| Sept. 11, 2023 | 2023-173 | 9 | $850,000 | Hypothetical performance on public websites without required policies; 2 firms also failed to keep copies of ads |
| April 12, 2024 | 2024-46 | 5 | $200,000 | Same hypothetical-performance failure; 4 firms got reduced penalties for fixing it before SEC contact; GeaSphere charged with much more |
| Sept. 9, 2024 | 2024-121 | 9 | $1,240,000 | Untrue or unsubstantiated claims, testimonials, endorsements and third-party ratings without required disclosures |
The April 2024 release is the clearest signal on cooperation: Bradesco, Credicorp, InSight and Monex “received reduced penalties because of the corrective steps they undertook in advance of being contacted by the SEC staff.” Their penalties were $20,000 to $30,000, against $50,000 to $175,000 for the nine firms in the September 2023 batch charged with the same provision.
Full tracker: every SEC Marketing Rule enforcement action
Download the data: sec_marketing_rule_actions.csv (32 actions, 16 fields: date, respondent, release number, violation types, penalties, AUM and SEC links). Free to reuse with a link to this page.
Sorted by date. Firm names link to the SEC order or release. AUM is the regulatory assets under management figure as stated in the order, which the SEC takes from the firm’s own Form ADV. “Undertakings” means the firm agreed to compliance steps such as hiring a consultant or reviewing its advertisements.
| Date | Respondent | Release | Violation types | Civil penalty | AUM (per order) | Other relief | What the order found |
|---|---|---|---|---|---|---|---|
| Aug. 21, 2023 | Titan Global Capital Management USA LLC | IA-6380 | Hypothetical performance; Untrue or misleading statements; Compliance rule 206(4)-7 | $850,000 (plus $192,454 disgorgement, $7,598 interest) | $548 million | Censure; cease-and-desist | Advertised a hypothetical “annualized” return as high as 2,700% for its crypto strategy, extrapolated from three weeks; firm had elected early compliance with the amended rule. |
| Sept. 11, 2023 | BTS Asset Management Inc. | IA-6405 | Hypothetical performance | $135,000 | $377 million | Censure; cease-and-desist; undertakings | Advertised hypothetical performance to the general public on its website without policies and procedures to make it relevant to the intended audience. |
| Sept. 11, 2023 | Banorte Asset Management, Inc. | IA-6404 | Hypothetical performance | $50,000 | $139 million | Censure; cease-and-desist; undertakings | Advertised hypothetical performance to the general public on its website without policies and procedures to make it relevant to the intended audience. |
| Sept. 11, 2023 | Elm Partners Management LLC | IA-6406 | Hypothetical performance | $175,000 | $1.28 billion | Censure; cease-and-desist; undertakings | Advertised hypothetical performance to the general public on its website without policies and procedures to make it relevant to the intended audience. |
| Sept. 11, 2023 | Hansen and Associates Financial Group Inc. | IA-6407 | Hypothetical performance | $50,000 | $196 million | Censure; cease-and-desist; undertakings | Advertised hypothetical performance to the general public on its website without policies and procedures to make it relevant to the intended audience. |
| Sept. 11, 2023 | Linden Thomas Advisory Services, LLC | IA-6408 | Hypothetical performance | $135,000 | $1.14 billion | Censure; cease-and-desist; undertakings | Advertised hypothetical performance to the general public on its website without policies and procedures to make it relevant to the intended audience. |
| Sept. 11, 2023 | MRA Advisory Group | IA-6411 | Hypothetical performance; Books and records | $85,000 | $213 million | Censure; cease-and-desist; undertakings | Advertised hypothetical performance to the general public on its website without policies and procedures to make it relevant to the intended audience. Also failed to keep required copies of advertisements. |
| Sept. 11, 2023 | Macroclimate LLC | IA-6409 | Hypothetical performance; Books and records | $100,000 | $158 million | Censure; cease-and-desist; undertakings | Advertised hypothetical performance to the general public on its website without policies and procedures to make it relevant to the intended audience. Also failed to keep required copies of advertisements. |
| Sept. 11, 2023 | McElhenny Sheffield Capital Management, LLC | IA-6410 | Hypothetical performance | $60,000 | $400 million | Censure; cease-and-desist; undertakings | Advertised hypothetical performance to the general public on its website without policies and procedures to make it relevant to the intended audience. |
| Sept. 11, 2023 | Trowbridge Capital Partners LLC | IA-6412 | Hypothetical performance | $60,000 | $42 million | Censure; cease-and-desist; undertakings | Advertised hypothetical performance to the general public on its website without policies and procedures to make it relevant to the intended audience. |
| March 18, 2024 | Delphia (USA) Inc. | IA-6573 | Untrue or misleading statements; Compliance rule 206(4)-7 | $225,000 | $187 million | Censure; cease-and-desist | “AI washing”: claimed to use AI and machine learning on client data in its investment process when it did not (2019 to 2023). |
| March 18, 2024 | Global Predictions, Inc. | IA-6574 | Untrue or misleading statements; Testimonials and endorsements; Hypothetical performance; Compliance rule 206(4)-7 | $175,000 | None reported on Form ADV (per order) | Censure; cease-and-desist | Called itself the “first regulated AI financial advisor”, could not substantiate performance claims, omitted testimonial conflicts, advertised hypothetical performance without required policies. |
| April 12, 2024 | Bradesco Global Advisors Inc. | IA-6589 | Hypothetical performance | $20,000 | $200 million | Censure; cease-and-desist; undertakings | Hypothetical performance on public website without required policies (Nov. 4, 2022 to June 8, 2023). SEC press release says the penalty was reduced for corrective steps taken before SEC staff contact. |
| April 12, 2024 | Credicorp Capital Advisors LLC | IA-6588 | Hypothetical performance | $30,000 | $516 million | Censure; cease-and-desist; undertakings | Hypothetical performance on public website without required policies (Nov. 4, 2022 to June 8, 2023). SEC press release says the penalty was reduced for corrective steps taken before SEC staff contact. |
| April 12, 2024 | Gea Sphere, LLC (GeaSphere Advisors) | IA-6585, IC-35170 | Untrue or misleading statements; Testimonials and endorsements; Hypothetical performance; Books and records; Compliance rule 206(4)-7 | $100,000 | $86 million | Censure; cease-and-desist; undertakings | False and misleading performance claims, gross without net performance, unsubstantiated performance, hypothetical performance without policies, no written agreements with paid endorsers, missing ad and performance records. |
| April 12, 2024 | InSight Securities, Inc. | IA-6586 | Hypothetical performance | $20,000 | $126 million | Censure; cease-and-desist; undertakings | Hypothetical performance on public website without required policies (Nov. 4, 2022 to June 8, 2023). SEC press release says the penalty was reduced for corrective steps taken before SEC staff contact. |
| April 12, 2024 | Monex Asset Management, Inc. | IA-6587 | Hypothetical performance | $30,000 | $160 million | Censure; cease-and-desist; undertakings | Hypothetical performance on public website without required policies (Nov. 4, 2022 to June 8, 2023). SEC press release says the penalty was reduced for corrective steps taken before SEC staff contact. |
| June 14, 2024 | Twenty Acre Capital LP | IA-6628 | Untrue or misleading statements | $100,000 | $180.7 million | Censure; cease-and-desist | Advertised a private fund using returns experienced by a single investor (for example 44.8% net in 2021) without disclosing they differed from fund performance. |
| Aug. 9, 2024 | The Pacific Financial Group, Inc. | IA-6646 | Hypothetical performance | $430,000 | $3.7 billion | Censure; cease-and-desist; undertakings | Hypothetical performance on public website without required policies and procedures. |
| Sept. 3, 2024 | Black Dragon Capital, LLC; Black Dragon Capital Investment Management, LLC; Louis Hernandez, Jr. | LR-26095 (civil action); follow-on IA-6729 | Untrue or misleading statements; Books and records; Compliance rule 206(4)-7 | Not stated | Not stated (filed Form ADV as exempt reporting adviser claiming private fund AUM under $150 million) | Consent final judgment (Sept. 25, 2024): permanent injunction; civil penalties agreed, amount not stated in SEC release; follow-on censure (IA-6729) | Federal court case (S.D. Fla.), settled by consent without admitting or denying: performance data on website and misleading performance in marketing materials, plus failure to register. |
| Sept. 9, 2024 | AZ Apice Capital Management LLC | IA-6679 | Untrue or misleading statements | $70,000 | $345 million | Censure; cease-and-desist; undertakings | Claimed advice was “free from conflicts of interest” and “conflict-free” without context; could not substantiate. |
| Sept. 9, 2024 | Abacus Planning Group, Inc. | IA-6678 | Third-party ratings; Untrue or misleading statements | $150,000 | $1.68 billion | Censure; cease-and-desist; undertakings | Untrue statement about third-party ratings received; ratings shown without the date given and period covered. |
| Sept. 9, 2024 | Beta Wealth Group, Inc. | IA-6684 | Third-party ratings; Untrue or misleading statements | $80,000 | $399 million | Censure; cease-and-desist; undertakings | Rating without date and period; could not substantiate “top wealth managers … 14 consecutive years” award claim. |
| Sept. 9, 2024 | Droms Strauss Advisors, Inc. (Droms Strauss Wealth Management) | IA-6680 | Untrue or misleading statements | $85,000 | $676 million | Censure; cease-and-desist; undertakings | Claimed an adviser representative gave advice free from conflicts of interest, without context; could not substantiate. |
| Sept. 9, 2024 | Howard Bailey Securities, LLC | IA-6681 | Testimonials and endorsements | $90,000 | $463 million | Censure; cease-and-desist; undertakings | “Official Wealth Management Partner” of a university athletic program shown without paid non-client endorsement disclosures; “testimonials” that were not from current clients. |
| Sept. 9, 2024 | Integrated Advisors Network LLC | IA-6682 | Untrue or misleading statements | $325,000 | $4.2 billion | Censure; cease-and-desist; undertakings | Claimed it was “aligning incentives and eliminating conflicts of interest” without context; could not substantiate. |
| Sept. 9, 2024 | Professional Financial Strategies, Inc. | IA-6683 | Third-party ratings | $60,000 | $191 million | Censure; cease-and-desist; undertakings | Third-party rating shown without the date given and period covered. |
| Sept. 9, 2024 | Richard Bernstein Advisors LLC | IA-6685 | Third-party ratings | $295,000 | $5.2 billion | Censure; cease-and-desist; undertakings | Two third-party ratings shown without the date given and period covered. |
| Sept. 9, 2024 | TS Bank d/b/a Callahan Financial Planning | IA-6686 | Untrue or misleading statements | $85,000 | $248 million | Censure; cease-and-desist; undertakings | Claimed membership in a non-existent organization called “Fiduciary Firm” and “no conflict of interest” without context. |
| Nov. 1, 2024 | Wahed Invest, LLC | IA-6763 | Testimonials and endorsements; Hypothetical performance | $250,000 | $523.5 million | Censure; cease-and-desist; undertakings | Endorsements from professional athletes on website, social media and email without required disclosures; backtested hypothetical performance without required policies. |
| Dec. 20, 2024 | Atlas Financial Advisors, Inc. | IA-6803 | Untrue or misleading statements; Hypothetical performance; Books and records; Compliance rule 206(4)-7 | $175,000 | $106 million | Censure; cease-and-desist; undertakings | False and misleading strategy and performance claims, gross without net performance, unsubstantiated performance, hypothetical performance without policies, missing performance calculation records. |
| Sept. 4, 2025 | Meridian Financial, LLC | IA-6916 | Untrue or misleading statements; Books and records; Compliance rule 206(4)-7 | $75,000 | $258 million | Censure; cease-and-desist; undertakings | Claimed it “refuse[d] all conflicts of interest” without context; did not keep copies of website advertisements; compliance program failures. |
What firms were charged with, by violation type
Many orders charge more than one provision, so the counts add up to more than 32. We tagged each action from the findings in the order itself, not from press coverage.
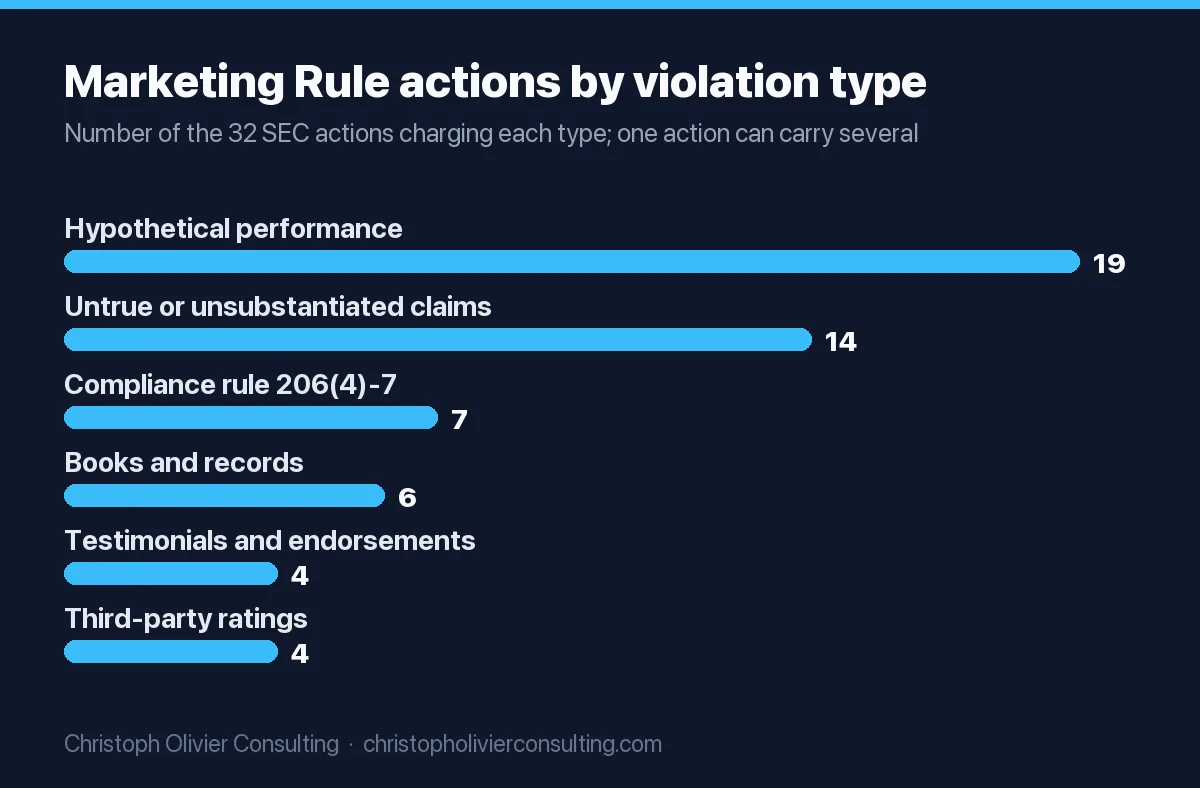
| Violation type | Rule | Actions | Share of 32 | Median penalty | Example from the orders |
|---|---|---|---|---|---|
| Hypothetical performance without required policies or context | 206(4)-1(d) | 19 | 59% | $100,000 | Titan advertised a 2,700% “annualized” crypto return extrapolated from three weeks |
| Untrue, misleading or unsubstantiated statements | 206(4)-1(a) | 14 | 44% | $100,000 | Callahan claimed membership in a non-existent organization called “Fiduciary Firm” |
| Compliance program failures charged alongside | 206(4)-7 | 7 | 22% | $175,000 | Atlas failed to implement its own marketing policies |
| Books and records | 204-2(a)(11), (16) | 6 | 19% | $100,000 | Meridian did not keep copies of advertisements on its website |
| Testimonials and endorsements | 206(4)-1(b) | 4 | 13% | $137,500 | Wahed used professional athlete endorsements without required disclosures |
| Third-party ratings | 206(4)-1(c) | 4 | 13% | $115,000 | Richard Bernstein Advisors showed two ratings without the date or period covered |
Median penalties by type are computed over actions with a stated penalty and overlap, because one order can carry several types. Penalties also tracked firm size: among the 30 actions with both a stated penalty and a stated AUM figure, the median was $72,500 for firms under $250 million (14 actions), $82,500 for $250 million to $1 billion (10) and $235,000 for firms over $1 billion (6).
SEC marketing rule testimonials and endorsements: the four cases
Testimonials and endorsements get the most attention from advisor marketers, yet only four actions charge Rule 206(4)-1(b). Each one turned on disclosure or paperwork, not on the use of testimonials as such.
- Global Predictions (March 18, 2024, $175,000): failed to disclose material conflicts of interest from its relationships with certain people giving testimonials, alongside its AI claims.
- GeaSphere (April 12, 2024, $100,000): failed to enter into written agreements with people it compensated for endorsements.
- Howard Bailey Securities (Sept. 9, 2024, $90,000): advertised that it was the “Official Wealth Management Partner of” a university athletic program on videos, social media, bags and flags without disclosing that the endorser was a paid non-client; it also posted “testimonials” that did not come from current clients.
- Wahed Invest (Nov. 1, 2024, $250,000): ran endorsements from several professional athletes on its website, social media and email without the required disclosures.
The rule’s required disclosures, from 17 CFR 275.206(4)-1(b), are short: whether the person is a current client, whether they were paid, and a brief statement of material conflicts, all “clearly and prominently.” The Division of Examinations’ December 16, 2025 risk alert found the same gaps in exams: missing disclosures, no written agreements with paid promoters, and disclosures placed behind hyperlinks or in small fonts. If you are planning a testimonial program, our guide to client testimonials and case studies for financial advisors covers how to collect them; this tracker shows where firms slipped on the disclosure side.
What got firms fined: a pass/fail website and marketing checklist
Each row maps a violation the SEC actually charged to a check you can run on your own website, social profiles and pitch decks. “Fail” examples are taken from the orders.
| Check | Pass if | Fail looks like (from SEC orders) | Rule |
|---|---|---|---|
| 1. Hypothetical, model or backtested returns on public pages | None on public pages, or written policies showing the numbers fit the likely audience, plus criteria, assumptions, risks and limitations shown with the figure | 19 firms; Titan’s 2,700% annualized figure from 3 weeks of data | (d)(5) |
| 2. Gross performance always paired with net | Net shown with at least equal prominence, same period, same method | GeaSphere and Atlas showed gross without net | (d)(1) |
| 3. Performance is the portfolio’s, not one investor’s | Fund or composite returns, with cherry-picking avoided | Twenty Acre advertised one investor’s 44.8% 2021 net return as fund performance | (a) |
| 4. No “conflict-free” claims | No “free from conflicts,” “no conflict of interest,” “eliminating conflicts” language anywhere | AZ Apice, Droms Strauss, Integrated Advisors, Callahan, Meridian | (a)(2) |
| 5. Every award and fact has a file behind it | Substantiation saved before publishing (award letter, criteria, date) | Beta Wealth’s “14 consecutive years” award claim it could not substantiate | (a)(2) |
| 6. Ratings show date, period, rater and payment | Each rating badge shows the date given, period covered, who rated it, and any fee paid | Abacus, Professional Financial, Beta Wealth, Richard Bernstein Advisors; some ratings were more than five years old | (c) |
| 7. Testimonials come from current clients | Quote is from a current client, labeled as such, with payment and conflicts disclosed | Howard Bailey’s “testimonials” were not from current clients | (b)(1) |
| 8. Paid promoters and sponsorships disclosed | Disclosure that the endorser is a paid non-client; written agreement on file for paid promoters | Howard Bailey athletic sponsorship, Wahed athletes, GeaSphere | (b)(1), (b)(2) |
| 9. Memberships, technology and AI claims are literally true | Every organization exists and every tool claim matches what the firm actually uses | Callahan’s “Fiduciary Firm”; Delphia and Global Predictions AI claims | (a)(1) |
| 10. Disclosures sit next to the claim | Risks and assumptions visible with the number, not only behind a “Disclosures” link | Titan’s key assumptions were “accessible only through links” | (a), (d)(5) |
| 11. Copies of every ad are kept | Website, social and email versions archived with performance workpapers | Macroclimate, MRA, GeaSphere, Atlas, Meridian | 204-2 |
In my view the cheapest fixes are checks 4 and 6: deleting a “conflict-free” line or adding a date to an award badge takes minutes, and both appear in multiple orders. Copywriters should treat the rule as a constraint from the first draft; our notes on financial advisor website copy that converts and on getting more reviews assume the disclosures above are in place. Social posts count as advertisements too: the April 2024 risk alert lists advisers that “did not maintain copies of information posted to social media,” which matters if you follow a social media plan for financial advisors.
Marketing Rule guidance timeline: risk alerts and FAQ updates
Exams and staff FAQs move faster than enforcement. This is the full public guidance trail we could verify on sec.gov.
| Date | Type | Topic | Source |
|---|---|---|---|
| Dec. 22, 2020 | Rule adopted | Amended Rule 206(4)-1 replaces the separate advertising and cash solicitation rules (Release IA-5653) | Risk alert, Sept. 2022 |
| March 18, 2021 | FAQ | Compliance date: no partial early adoption | Marketing Compliance FAQ |
| April 14, 2021 | FAQ | Time period requirement: interim performance up to about one month after year-end | Marketing Compliance FAQ |
| May 4, 2021 | Effective date | Advisers may comply early, in full | Marketing Compliance FAQ |
| Sept. 19, 2022 | Risk alert | Exams will review policies, substantiation, performance advertising, books and records | Division of Examinations |
| Nov. 4, 2022 | Compliance date | All ads from SEC-registered advisers subject to the amended rule | Same risk alert |
| June 8, 2023 | Risk alert | Added focus: testimonials, endorsements, third-party ratings, Form ADV accuracy, general prohibitions | Division of Examinations |
| Feb. 6, 2024 | FAQ | Gross and net IRR must use the same method; subscription facility treatment | Marketing Compliance FAQ |
| April 17, 2024 | Risk alert | Initial observations: weak policies, missing social media records, “free of all conflicts” claims, misleading “seen on” media claims | Division of Examinations |
| March 19, 2025 | FAQ | Extracted performance (updated) and gross portfolio characteristics | Marketing Compliance FAQ |
| Dec. 16, 2025 | Risk alert | Testimonials, endorsements and third-party ratings: disclosure, oversight and due diligence gaps | Division of Examinations |
| Jan. 15, 2026 | FAQ | Model fees vs actual fees; SRO final orders and testimonial disqualification | Marketing Compliance FAQ |
Reading the two lists together: guidance kept coming after enforcement slowed. The January 15, 2026 FAQ, for example, says whether showing net performance with actual fees violates the general prohibitions “depends on all of the facts and circumstances,” a softer reading than some advisers took from footnote 590 of the adopting release.
What Rule 206(4)-1 covers and who it applies to
The Marketing Rule applies to investment advisers registered or required to be registered with the SEC under Section 203 of the Advisers Act, as the April 2024 and December 2025 risk alerts state. The rule has four working parts, per the regulation text:
- (a) Seven general prohibitions: no untrue or misleading statements, no material facts you cannot substantiate on demand, no misleading implications, no benefits without fair and balanced risks, and no cherry-picked performance or time periods.
- (b) Testimonials and endorsements: allowed with disclosures, oversight, written agreements for paid promoters, and no compensation to disqualified persons.
- (c) Third-party ratings: allowed with due diligence on the survey and disclosure of date, period, rater and compensation.
- (d) Performance: net with gross, 1, 5 and 10 year periods for non-private-fund ads, and hypothetical performance only with audience-relevance policies and disclosure of criteria, assumptions, risks and limitations.
The FTC enforces a different set of advertising rules for most other businesses; our FTC advertising enforcement statistics make a useful comparison for firms that also market non-advisory services.
Methodology
- We crawled the full SEC Administrative Proceedings listing and kept all 2,122 entries dated November 4, 2022 to November 10, 2026.
- We downloaded the 451 orders carrying an Advisers Act (IA) release number, extracted the text and searched for “206(4)-1” and “Marketing Rule.” 37 orders matched.
- We read each match. 31 found violations of the amended rule and are in the tracker. 6 were excluded: Fundrise Advisors (IA-6381, conduct under the old cash solicitation rule, charged only under Rule 206(4)-7), Wellesley Asset Management (IA-6433, old advertising rule, conduct 2015 to March 2022), Joseph Andrew Paul (34-100323, follow-on to an old-rule injunction), Inspire Investing (IA-6710, Rule 206(4)-1 appears only in the cease-and-desist clause, with findings under Section 206(2) and Rules 206(4)-7 and 206(4)-8), Invesco Advisers (IA-6770, old rule 206(4)-1(a)(5), conduct 2020 to July 2022) and the Black Dragon follow-on order (IA-6729, counted with its court case).
- We fetched all 1,115 SEC litigation releases dated November 4, 2022 to November 12, 2026 and searched the same terms. One civil action matched: SEC v. Black Dragon Capital (LR-26095).
- We scanned SEC press release headlines back to April 2023 for Marketing Rule, hypothetical performance, testimonial, endorsement and advertising terms to confirm the sweep dates and totals.
- For each action we recorded date, respondent, release number, provisions found violated, other charges, civil penalty, disgorgement and interest, other relief, AUM as stated in the order, and links. Violation-type tags are our classification of the order’s findings. Requests to sec.gov used a generic research user agent and were paced at no more than about five per second.
Limitations
- Litigated complaints: Marketing Rule counts that appear only in a court complaint, without a litigation release mentioning the rule, would be missed. Black Dragon’s penalty amount is not stated in the SEC release.
- Exam findings are not public: individual examination deficiencies are not published, so they are not in this data; the risk alerts describe them only in aggregate.
- Other regulators: state securities regulators and FINRA actions are not included.
- AUM: the figure is what the order states from a Form ADV filed near the time of the case; it is self-reported and may have changed.
- FAQ history: the dates come from the FAQ page as published on November 12, 2026; questions removed or superseded earlier may not show.
- Cut-off: orders published after November 10, 2026 and litigation releases after November 12, 2026 are not included.
This tracker summarizes public SEC records for research purposes and is not legal advice; talk to your compliance counsel before changing advertising. If you want a second pair of eyes on how your marketing plan holds up against these orders, you can book a consultation.
Ready to scale your revenue?
Book a free 30-min consultation. We’ll diagnose your growth bottleneck and map out the 3 highest-leverage moves for your business.
Frequently asked questions
What is the SEC marketing rule?
The SEC Marketing Rule is Rule 206(4)-1 under the Investment Advisers Act, amended in December 2020 with a compliance date of November 4, 2022. It replaced the old advertising and cash solicitation rules with one rule covering seven general prohibitions, testimonials and endorsements, third-party ratings and performance advertising, including strict conditions on hypothetical performance.
How many firms has the SEC charged under the marketing rule?
Our tracker counts 32 SEC enforcement actions charging the amended Marketing Rule from August 21, 2023 to November 12, 2026: 31 settled administrative orders and one federal court case against Black Dragon Capital settled by consent. Those actions named 33 advisory firms plus one individual. The most recent action we found is Meridian Financial on September 4, 2025.
How big are SEC marketing rule fines?
Disclosed civil penalties total $4,570,000 across 31 actions with a stated amount. The median penalty is $90,000 and the range runs from $20,000 (InSight Securities and Bradesco, both reduced for early corrective steps) to $850,000 (Titan Global Capital Management, which also paid $192,454 in disgorgement). Firms with over $1 billion in assets had a median penalty of $235,000.
Can financial advisors use testimonials under the SEC marketing rule?
Yes, if the advertisement clearly and prominently discloses whether the person is a current client, whether they were paid, and any material conflicts, and the adviser has oversight and written agreements for paid promoters. All four SEC testimonial and endorsement cases, including Howard Bailey and Wahed Invest, involved missing disclosures or agreements, not testimonials as such.
Who does the SEC marketing rule apply to?
The Marketing Rule applies to investment advisers registered or required to be registered with the SEC under Section 203 of the Advisers Act, including advisers to private funds. It covers advertisements disseminated on or after November 4, 2022, which includes website pages, social media posts, emails and pitch materials that offer advisory services to more than one person.
What does SEC rule 206(4)-1 focus on?
Rule 206(4)-1 focuses on keeping adviser advertising truthful and balanced. In enforcement, the SEC has focused most on hypothetical performance shown without required policies (19 of 32 actions), unsubstantiated claims such as being conflict-free (14 actions with general prohibition charges), testimonials and endorsements (4) and third-party ratings without dates or sources (4).
What is hypothetical performance under the marketing rule?
Hypothetical performance is performance not actually achieved by any portfolio of the adviser, such as model, backtested or projected returns. An adviser may advertise it only with policies making it relevant to the likely audience and with disclosure of criteria, assumptions, risks and limitations. All 14 firms in the September 2023 and April 2024 sweeps were charged for showing it on public websites without this.