
Home services companies sell on two different yardsticks. Owner-run shops trade at roughly 2.5x to 2.8x seller’s discretionary earnings (SDE): BizBuySell’s sold-business data for Q3 2021 through Q2 2026 puts HVAC at 2.83x, plumbing at 2.61x and pest control at 2.46x. Once a company is big enough to be priced on EBITDA, the reference points move to roughly 5.6x to 6.8x: GF Data’s small-deal average was 5.8x in Q1 2026, and the IBBA and M&A Source Market Pulse put the $5M to $50M band at 5.8x in Q2 2026, its highest since Q1 2022.
Every figure below carries its source and date. The numbers come from different datasets (a business-for-sale marketplace, a private equity deal survey, a broker survey and advisor reports), and each one fits a different size of company. This page is market data, not financial, tax, legal or investment advice. Get a formal valuation before you price a sale.
Home services multiples at a glance (November 2026)
| Segment | Multiple | Earnings basis | Source, period |
|---|---|---|---|
| Owner-run HVAC businesses sold | 2.83x | SDE, average | BizBuySell, sales Q3 2021 to Q2 2026 |
| Owner-run plumbing businesses sold | 2.61x | SDE, average | BizBuySell, sales Q3 2021 to Q2 2026 |
| Owner-run pest control businesses sold | 2.46x | SDE, average | BizBuySell, sales Q3 2021 to Q2 2026 |
| All small businesses sold in 2025 | 2.61x | Cash flow (SDE), average | BizBuySell 2025 Year in Review |
| PE deals, $1M to $25M enterprise value | 5.8x (Q1 2026); 5.9x (2025) | TEV / adjusted EBITDA, average | GF Data via Mercer Capital, Summer 2026 |
| Broker-advised deals, $5M to $50M purchase price | 5.8x | EBITDA | IBBA and M&A Source, Q2 2026 |
| PE deals, $10M to $50M enterprise value | About 6.8x | TEV / adjusted EBITDA | GF Data via Mercer Capital, Q2 2026 |
| HVAC services M&A | 9.5x | EV / EBITDA, average | Capstone Partners, 2024 to YTD 2026 |
| Residential services M&A, all segments | 12.0x | EV / EBITDA, last twelve months | Capstone Partners, October 2026 |
| Platform deal: Champions Group (HVAC, plumbing, electrical) | About 18.5x | EV / EBITDA | Blackstone deal, February 2026, via Capstone |
| Public company: Rollins (pest control) | 19.0x | EV / LTM EBITDA | Capstone, as of July 27, 2026 |
The jump from the top rows to the middle rows stacks two effects: a real size premium and a change in the earnings base (SDE includes the owner’s pay, EBITDA does not). The advisor averages near the bottom come from deals where a multiple was disclosed, which skews toward larger, platform-quality targets. A 40-truck HVAC company and a 4-truck HVAC company are not priced off the same row.
BizBuySell Insight Report 2025: median cash flow and the cash flow multiple
BizBuySell does not publish a median cash flow multiple. Its 2025 Year in Review reports an average cash flow multiple of 2.61x, up 1% from 2024, and a median cash flow of $158,950, up 3%. If you need a median-based ratio, divide the median sale price ($350,000) by the median cash flow ($158,950): about 2.20x. That is our arithmetic, a ratio of two medians, not a BizBuySell statistic. It runs below the 2.61x average because a minority of large, high-multiple sales pull the average up.
| BizBuySell 2025 metric (all industries, US) | 2025 value | Change vs 2024 |
|---|---|---|
| Closed transactions | 9,586 | +0.4% |
| Median sale price | $350,000 | +2% |
| Median cash flow (SDE) | $158,950 | +3% |
| Median revenue | $703,000 | +3% |
| Average cash flow multiple | 2.61x | +1% |
| Average revenue multiple | 0.69x | +2% |
| Sale price as share of asking | 94% | n/a |
| Median days to close | 170 (service businesses: 167) | n/a |
2025 multiples for service and home services trades
BizBuySell’s trade benchmark pages break the multiple out by year, so you can get a 2025-only number for your trade. Service businesses as a group averaged 2.70x earnings in 2025, the highest of the five years shown, per its service business benchmarks. The quartile column is the useful one for pricing: half of sold businesses fell inside it.
| Trade | 2025 avg earnings (SDE) multiple | 2025 avg revenue multiple | 2025 median sale price | Middle 50% of SDE multiples, 2021 to 2025 sales |
|---|---|---|---|---|
| All service businesses | 2.70x | 0.87x | $395,000 | 1.75x to 3.13x |
| HVAC | 2.68x | 0.62x | $800,000 | 1.99x to 3.33x |
| Plumbing | 2.59x | 0.71x | $837,500 | 1.66x to 3.15x |
| Pest control | 2.35x | 1.10x | $237,500 | 1.69x to 3.00x |
Pest control’s revenue multiple is the outlier, and margins explain it: owner earnings were 45.7% of revenue for pest control businesses sold in 2025, against 24.8% for HVAC, per the same BizBuySell pages. A buyer pays more per dollar of revenue when more of each dollar reaches the owner.
Latest quarter: BizBuySell Q3 2026
The BizBuySell Insight Report for Q3 2026 counted 2,132 businesses sold, down 7% from Q3 2025. The median sale price was $350,000, up 17% year over year, which BizBuySell says partly reflects a shift toward larger deals. Median cash flow rose 5% to $156,000 and median revenue rose 3% to $669,801. The average cash flow multiple rose 2.6%.
- Size split: businesses that sold for more than $1 million averaged 3.73x cash flow and 0.97x revenue and closed at 100.8% of asking. Those under $1 million averaged 2.30x cash flow, 0.62x revenue and 93.6% of asking. Sales above $1 million were 22% of the quarter’s transactions, the highest share on record.
- Service sector: 992 transactions, up 9% year over year and 47% of all reported sales. Median sale price $350,000, median cash flow $157,378 (up 18%), median revenue $561,633.
- Financing: 78% of surveyed buyers expect to use SBA financing. New SBA rules effective October 1 require an independent valuation on every SBA-financed change of ownership, a quality of earnings report on acquisitions of $3 million or more, and proof that historical earnings cover the debt.
These are the same Q3 2026 figures we put on the slides in our owner workshop presentation outline for exit planning advisors, if you are presenting this data to a room of owners.
SDE multiples by trade: HVAC, plumbing, pest control, landscaping
BizBuySell’s valuation multiples by industry pool five years of reported sales (Q3 2021 through Q2 2026) and are updated twice a year. The earnings multiple is sale price divided by the SDE the owner or broker reported. Across all sectors the average is 2.58x earnings and 0.67x revenue.
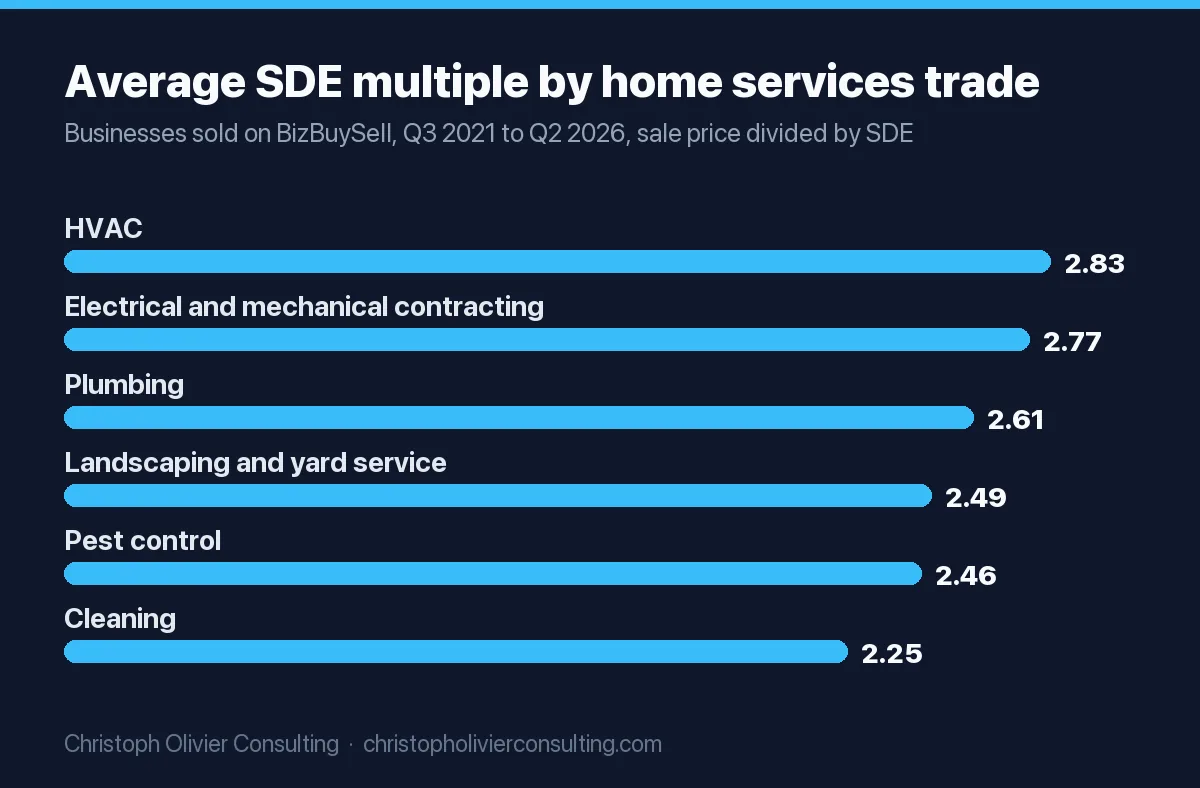
| Trade (BizBuySell category) | Avg earnings (SDE) multiple | Avg revenue multiple | Median sale price |
|---|---|---|---|
| HVAC businesses | 2.83x | 0.60x | $750,000 |
| Electrical and mechanical contracting | 2.77x | 0.63x | $1,009,000 |
| Plumbing businesses | 2.61x | 0.69x | $699,000 |
| Landscaping and yard service | 2.49x | 0.72x | $449,950 |
| Pest control businesses | 2.46x | 1.01x | $250,000 |
| Cleaning businesses | 2.25x | 0.72x | $281,500 |
Two notes before you use these. First, BizBuySell’s tables have no roofing category, so there is no SDE benchmark for roofing on the platform. Second, the HVAC figure differs between BizBuySell pages (2.83x here, 2.75x on the HVAC benchmark page) because the windows differ: Q3 2021 to Q2 2026 here, calendar 2021 to 2025 there. Quote the window with the number.
SDE vs EBITDA: how to convert before you compare
SDE adds one full owner’s salary and perks back to profit. EBITDA assumes you pay someone a market wage to do your job. The IBBA’s Q2 2026 highlights draw the line by deal size in a footnote: below $2 million in purchase price it reports multiples of SDE, and from $2 million to $50 million it reports multiples of EBITDA.
FE International’s October 19, 2026 agency benchmarks put the switch at “roughly $500,000 in earnings” and give a rule of thumb: “an agency’s EBITDA multiple is usually 0.7x to 0.8x of the equivalent SDE multiple, because the owner’s replacement cost comes out of earnings first.” That rule was written for agencies, and we use the same source in our agency exit planning guide with current multiples. The safe way to apply it in the trades is to convert the earnings, not the multiple: subtract a replacement manager’s salary, then use a multiple quoted on that same basis.
| Step | Median HVAC shop | Larger HVAC shop (illustration) |
|---|---|---|
| SDE | $304,309 (BizBuySell five-year median owner earnings, HVAC sold) | $600,000 |
| Less replacement general manager | $134,940 | $134,940 |
| EBITDA | $169,369 | $465,060 |
| EBITDA as share of SDE | 0.56 | 0.78 |
| Price at 2.58x SDE (median HVAC sold multiple) | $785,117 | $1,548,000 |
| Same price as a multiple of EBITDA | 4.6x | 3.3x |
The replacement salary is the May 2025 mean annual wage for general and operations managers across all industries, $134,940, from the BLS Occupational Employment and Wage Statistics. Use your local figure if you have one. Two lessons fall out of the math. The smaller the shop, the bigger the bite the replacement salary takes, so the 0.7 to 0.8 ratio overstates EBITDA for a typical owner-operator. And a “4.6x EBITDA” offer on a small shop can be exactly the same check as a 2.6x SDE offer.
Lower middle market EBITDA multiples by deal size
GF Data collects deal terms directly from private equity firms (335 US firms contributed, per Mercer Capital’s Fall 2026 update), which makes it the closest thing to a transaction register for sponsor deals between $10 million and $500 million. Its expanded small-deal set covers $1 million to $25 million. Only the figures below are publicly reported; the full tables are paid.
| Deal size (enterprise value) | Average TEV / EBITDA | Period | Source |
|---|---|---|---|
| $1M to $25M, all deals | 5.8x (5.9x full-year 2025; 5.6x in Q4 2025) | Q1 2026 | GF Data via Mercer Capital, Summer 2026 |
| $1M to $25M, platform buyouts | 6.0x | Q1 2026 | Same |
| $1M to $25M, add-ons | 5.6x | Q1 2026 | Same |
| $10M to $50M | About 7x (Q1); about 6.8x (Q2) | 2026 | Mercer Summer and Fall 2026 |
| $50M to $250M | About 7.6x | Q2 2026 | Mercer Fall 2026 |
| $100M to $500M | About 9x to 11x | Q1 2026 | Mercer Summer 2026 |
| All deals, $10M to $500M | 7.3x (Q1); 7.0x (Q2); 7.1x first half | 2026 | GF Data release, August 27, 2026; Mercer |
GF Data recorded 85 completed transactions in Q2 2026, and average total debt on platform buyouts fell to 2.9x EBITDA from 3.4x in Q1. Mercer adds that buyer transaction costs, which sit outside these multiples, add about 0.3x to the all-in cost. The broker survey lands in the same zone: the IBBA and M&A Source Q2 2026 release (255 advisors, 181 closed deals, published August 25, 2026) put the $5M to $50M band at 5.8x, up from 5.5x.
PE add-on acquisition trends in 2026 for $5M to $50M deals
First, a definition, because the query wording mixes two things. The IBBA’s $5M to $50M band is purchase price, not EBITDA. At its 5.8x Q2 2026 multiple, that band holds companies with roughly $0.9 million to $8.6 million of EBITDA (our arithmetic: $5M and $50M divided by 5.8). A company with $5M to $50M of EBITDA sits in GF Data’s larger tranches instead. Here is what the 2026 data shows for add-ons in that size range.
- Add-ons are still most of the deal count, but fewer of them. PitchBook’s Q2 2026 US PE Breakdown estimates 885 add-ons made up roughly three-quarters of all US buyouts, even as add-on count fell 31.2% year over year and add-on value fell 44.5% to $52.6 billion. Platform buyouts fell 34% to 289.
- Add-ons price below platforms. In Q1 2026 GF Data reported platform acquisitions at 7.6x against 6.5x for add-ons, the widest spread in its recent series. In the $1M to $25M small-deal set the gap was 6.0x against 5.6x.
- Home services add-ons slowed but still lead. Capstone Partners’ October 2026 Residential Services report counts 223 transactions year to date (through July 27). Sponsors accounted for 60.5%. PE add-ons fell to 114 from 149 a year earlier but still made up 51.1% of volume, while new platforms rose 10.5% to 21.
- HVAC services runs on add-ons. Capstone’s July 27, 2026 HVAC services update counts 92 transactions year to date, down 4.2%, of which 38 were PE add-ons (41.3%) and 9 were new platforms.
- Buyers want $1M to $10M of EBITDA. Axial’s February 2026 buyer data shows 93.44% of private equity fund mandates include the $1M to $3M EBITDA band, 86.25% include $3M to $5M, 78.35% include $5M to $10M, and only 41.09% include $10M and up.
- Competition for good companies is real. In the IBBA’s Q2 2026 survey, 87% of deals over $5 million drew at least three offers and 33% drew 10 or more. Sellers received 83% to 92% of the price in cash at close on average, and lower middle market deals took 11 to 12 months.
Capstone’s read on where this goes: years of consolidation have made new home services platforms harder to form, so sponsor capital is moving to adjacent niches such as generator service, floor coatings, artificial turf, exterior cleaning, tree care and pool services. If you run an independent HVAC company deciding whether to sell or compete, our piece on how independent HVAC companies compete with private equity consolidators covers the other side of that choice.
HVAC, plumbing, roofing and pest control: advisor-published multiples and deal data
These figures come from M&A advisors and a public company filing. Each is dated. Advisor averages reflect deals where terms were disclosed, so treat them as the upper part of the market, not a median.
| Trade | What was published | Source, date |
|---|---|---|
| HVAC services | Average 9.5x EV/EBITDA and 2.0x EV/revenue for 2024 to YTD 2026, down from 13.3x and 2.3x in 2021 to 2023. Broader HVAC: 11.4x, down from 13.4x. | Capstone Partners, July 27, 2026 |
| HVAC services, public comparables | APi Group 20.1x, EMCOR 19.7x, Limbach 15.6x EV/LTM EBITDA as of June 30, 2026. PKF says private HVAC services transaction multiples have stayed “north of 10x EBITDA.” Of the 11 HVAC services deals PKF lists for January to June 2026, 8 were PE add-ons. | PKF O’Connor Davies, August 4, 2026 |
| HVAC, plumbing and electrical (residential) | 43 deals YTD 2026, 27 by PE (62.8%), 19.3% of residential services M&A. Blackstone announced its acquisition of Champions Group at a $2.5 billion enterprise value, about 18.5x EV/EBITDA; Champions has 150,000 active members and more than 1,800 field technicians. | Capstone Partners, October 2026 |
| Plumbing | No standalone plumbing EBITDA multiple published by these advisors; plumbing sits inside the HVAC, plumbing and electrical segment. SDE benchmark: 2.61x (BizBuySell). | Capstone, October 2026; BizBuySell |
| Roofing | Exterior services M&A cooled from a record 2025 “particularly in roofing as lower storm activity, carrier exits, and rising claim denials” shrank the claims-funded re-roofing pool. 27 exterior services deals YTD, 17 by PE (63%). Bertram-backed Ridgeline Roofing has made eight add-ons since January 2024. | Capstone Partners, October 2026 |
| Commercial roofing deal | TopBuild agreed to buy Progressive Roofing for $810 million, about 9.1x trailing EBITDA (8.6x after $5 million of synergies). Progressive had $438 million revenue, $89 million EBITDA, and about 70% of revenue from non-discretionary re-roofing and maintenance. | TopBuild 8-K exhibit, July 8, 2025 |
| Pest control | 33 deals YTD 2026, 12 by PE (36.4%); strategics were 63.6% of acquirers. Rollins traded at 19.0x EV/LTM EBITDA, Rentokil at 12.8x. SDE benchmark: 2.46x (BizBuySell). | Capstone Partners, October 2026 (public data as of July 27, 2026) |
Why the advisor numbers run higher than GF Data: Capstone’s residential services average of 12.0x EV/EBITDA over the last twelve months sits just under its 12.4x average for the whole US M&A market, and both are built from disclosed deals, which are mostly larger ones. GF Data’s 5.6x to 6.8x small and lower middle market figures are closer to what a $1 million to $5 million EBITDA company should expect as a starting point.
Worked example: valuing a $3M EBITDA HVAC company
Say you own a residential HVAC company with $3.0 million of adjusted EBITDA, after paying a general manager a market salary and removing personal expenses. Here is how the published benchmarks bracket it.
- Find your band. At 5.6x to 6.8x, the enterprise value lands between $16.8 million and $20.4 million. That puts you inside GF Data’s $1M to $25M small-deal set, its $10M to $50M tranche, and the IBBA’s $5M to $50M band. It also puts you squarely in the $3M to $5M EBITDA band that 86.25% of PE fund mandates on Axial include.
- Price the benchmark range. Multiply $3.0 million by each published multiple (table below).
- Adjust for the value drivers. Score yourself on the scorecard in the next section. Strong agreement revenue and a technician bench move you up the range; owner dependence and project-heavy revenue move you down.
- Translate price into cash. The IBBA’s Q2 2026 survey found sellers received 83% to 92% cash at close on average. At 83% of a $17.4 million price, that is about $14.4 million at closing, with the rest in earnouts, seller notes or retained equity.
| Benchmark applied to $3.0M EBITDA | Multiple | Enterprise value |
|---|---|---|
| GF Data small-deal add-on average (Q1 2026) | 5.6x | $16.8M |
| GF Data $1M to $25M average (Q1 2026); IBBA $5M to $50M (Q2 2026) | 5.8x | $17.4M |
| GF Data small-deal platform average (Q1 2026) | 6.0x | $18.0M |
| GF Data $10M to $50M (Q2 2026) | 6.8x | $20.4M |
| Capstone HVAC services average, disclosed deals (2024 to YTD 2026) | 9.5x | $28.5M |
Read the first four rows as the realistic range for a single-region company and the 9.5x row as a ceiling built from larger disclosed deals. The 18.5x Champions Group price and the 15x to 20x public comparables are platform and public-market values; a $3 million EBITDA add-on does not get them, which is the spread consolidators are buying. If the result matters to a real decision, pay for a quality of earnings report and a formal valuation. This example is illustration, not advice.
Value drivers that move a home services multiple
Buyers price the same EBITDA differently depending on how durable it looks. Use this scorecard to see which way your business leans before a buyer does.
| Driver | What buyers check | Stronger | Weaker | Where the benchmark comes from |
|---|---|---|---|---|
| Recurring maintenance agreements | Agreements per $1M of service sales; share of service calls that convert to an agreement | 1,000 or more agreements per $1M of service sales; 30% or more service-call conversion; 80% or more tune-up conversion | Below those targets, or agreements not tracked | ServiceTitan KPI targets (vendor targets, not averages) |
| Contracted vs project revenue | How much revenue repeats without a new sale | “Predictable preventative service work, especially if contractually locked in over multiple years” | One-off installs, new construction, storm work | PKF O’Connor Davies, August 2026; TopBuild (70% non-discretionary) |
| Technician retention | Whether recruiting, training and retention are institutional or sit with the founder | A training pipeline that runs without you, such as an in-house academy | Techs loyal to the owner personally; no hiring system | Capstone, October 2026 |
| Owner dependence | Who holds the license, sells replacements and owns key relationships | A manager and sales lead in place; license held by someone who stays | Owner is the license holder, top seller and dispatcher | PKF (owner, license-holder and key-man risk); BizBuySell Q3 2026 |
| Storm and insurance exposure | Share of revenue funded by insurance claims | Retail re-roof and maintenance work | Claims-funded storm work | Capstone, October 2026 |
| Size | Sale price and EBITDA scale | Over $1M sale price: 3.73x cash flow | Under $1M: 2.30x cash flow | BizBuySell Q3 2026 |
Maintenance agreements. Agreements are the clearest lever you control. Champions Group’s 150,000 active members were part of what Blackstone paid about 18.5x for, and Progressive Roofing’s 70% non-discretionary revenue sat behind its 9.1x. Our HVAC marketing statistics and benchmarks page shows what a 30% agreement conversion does to a month’s revenue, and the HVAC shoulder season marketing plan shows when and how to sell memberships, with real published plan prices. Roofers can build the same base with a spring and fall inspection program, laid out in our roofing lead generation guide.
Technicians. Capstone cites TechForce Foundation data that HVAC technician supply met just 63.8% of demand in 2024. That is why buyers now ask whether your hiring engine survives your exit. Capstone points to Michael & Son’s 12-week paid academy, running since 2017, and Jay’s Heating, Air & Plumbing’s Altitude Academy, opened in March 2026, as the kind of system acquirers value.
Owner dependence. BizBuySell’s Q3 2026 report says businesses “with strong cash flow, clean financial records, and limited owner dependence continue to attract significant attention.” Take a two-week absence and write down what broke. Every item on that list is a discount a buyer will find in diligence. In my view, most owners can fix two or three of these lines in 12 to 18 months, and the agreement base and lead flow are the ones marketing can move. If those are your weak lines, you can book a consultation to work through them before you go to market.
Frequently asked questions
What is the BizBuySell Insight Report 2025 median cash flow multiple for small businesses?
BizBuySell reports an average, not a median. Small businesses sold in 2025 averaged 2.61x cash flow, up 1%, on a median sale price of $350,000 and median cash flow of $158,950 across 9,586 sales. Dividing those two medians gives about 2.20x, a ratio we calculated rather than a BizBuySell figure. Service businesses averaged 2.70x in 2025.
What EBITDA multiple do home services companies sell for in 2026?
It depends on size. GF Data put private equity deals between $1 million and $25 million of enterprise value at 5.8x EBITDA in Q1 2026, and deals of $10 million to $50 million at about 6.8x in Q2 2026. Capstone Partners reports 9.5x for HVAC services deals with disclosed terms from 2024 to mid-2026, which skews toward larger targets.
What are PE add-on acquisition trends for $5M-$50M deals in 2026?
Add-ons still dominate deal count but slowed. PitchBook estimates 885 US add-ons in Q2 2026, about three-quarters of buyouts, with count down 31.2% year over year. GF Data reported add-ons at 6.5x EBITDA against 7.6x for platforms in Q1 2026. The IBBA's $5M to $50M purchase-price band reached 5.8x in Q2 2026, its highest since Q1 2022.
What multiple does an HVAC company sell for?
Owner-run HVAC businesses sold on BizBuySell averaged 2.83x SDE for sales from Q3 2021 to Q2 2026, with the middle half between 1.99x and 3.33x. Larger HVAC companies are priced on EBITDA: roughly 5.6x to 6.8x in GF Data's small and lower middle market sets, and 9.5x on average for disclosed HVAC services deals per Capstone Partners.
How do you convert SDE to EBITDA for a trade business?
Subtract a market salary for the manager who would replace you from SDE. With BizBuySell's median HVAC owner earnings of $304,309 and the BLS May 2025 mean general manager wage of $134,940, EBITDA is $169,369, or 0.56 of SDE. A price of 2.58x SDE on that shop equals about 4.6x EBITDA.
Do pest control companies sell for higher multiples than HVAC or plumbing?
On SDE, no: BizBuySell shows pest control at 2.46x against 2.83x for HVAC and 2.61x for plumbing. On revenue, yes: pest control sells at 1.01x revenue against 0.60x for HVAC, because owner earnings were 45.7% of revenue in 2025. At the public end, Rollins traded at 19.0x EBITDA as of July 27, 2026.
Are roofing company multiples lower than other home services?
BizBuySell publishes no roofing SDE benchmark. Capstone Partners reported in October 2026 that roofing M&A cooled as lower storm activity, carrier exits and claim denials shrank the claims-funded re-roofing pool. Recurring work still earns a premium: TopBuild agreed to pay about 9.1x EBITDA for Progressive Roofing, which had about 70% non-discretionary re-roofing and maintenance revenue.