
The best bank advertising examples are the ones you can check: Capital One’s “What’s in Your Wallet?” (launched 2000), Bank of America’s “What would you like the power to do?” (2018), Chase’s “Make More of What’s Yours” spots, SoFi’s 20-year stadium naming deal and “Break Up With Bad Banking” push, Ally’s equal sports media spend, TD’s Automated Thanking Machine, and community banks that won ABA marketing awards in 2025 and 2026. Each one pairs a single idea with a disclosure layer that regulators actually check: the FDIC advertising statement, Regulation DD for deposit rates and Regulation Z for credit terms.
Below are 14 examples with the bank, channel, year, message and the lesson, each linked to the press release, award announcement or ad record it comes from. Then the rules, quoted from the official text with section numbers and the dates that matter in 2026 and 2027, a trigger-term table, a pass/fail checklist and copy-ready ad templates. I describe the creative rather than reproduce it. This page is general information, not legal advice: have your compliance officer or counsel sign off on any live ad.
Short answer: Bank ads that promote deposits or the bank in general must carry the FDIC advertising statement (“Member FDIC” or the FDIC symbol) under 12 CFR 328.6. Any ad that states a savings rate must call it an “annual percentage yield” and add the conditions in 12 CFR 1030.8. Credit ads that mention a payment, term, down payment or finance charge must also state the APR under 12 CFR 1026.24. FDIC digital sign rules for websites, apps and ATMs require compliance by April 1, 2027.
14 bank advertising examples at a glance
National campaigns teach positioning; the award winners teach what works on a community bank budget. Row 14 is the counter-example.
| # | Bank | Channel | Year | Core message | Lesson for your bank | Source |
|---|---|---|---|---|---|---|
| 1 | Capital One | TV, humor with recurring characters | 2000 | “What’s in Your Wallet?” | One question can carry a brand for decades | Capital One release, 2003 |
| 2 | Bank of America | TV premiere on Sunday Night Football, digital video, social, print | 2018 | “What would you like the power to do?” | Lead with the customer’s goal, not the product list | Business Wire release via TMCnet |
| 3 | Chase | TV spot “Do More” | 2022 | “Make More of What’s Yours” | Show the products in use: auto loans, travel rewards | iSpot.tv record |
| 4 | SoFi | Stadium naming rights | 2019 | SoFi Stadium, 20-year agreement | Buy one long asset instead of many short ones | SoFi release |
| 5 | SoFi | TikTok, Instagram, Twitter, then national TV | 2022 | “Break Up With Bad Banking” | Tie a switching offer to a calendar moment | SoFi release |
| 6 | SoFi | NFL broadcasts, streaming, YouTube | 2023 | “All Your Ambitions, All In One App” | Real member stories plus a full disclosure block | SoFi release |
| 7 | Ally | Sports media buying | 2022 to 2026 | 50/50 pledge: equal spend on women’s and men’s sports media | A media-buying policy can be the campaign | Ally release |
| 8 | TD (Canada) | Branches, talking ATM, online video | 2014 | #TDThanksYou | Thank existing customers on camera | TD newsroom |
| 9 | Summit Bank, Eugene, Ore. | 3.5-minute film | 2025 | “Do you want to Bank?” | Local culture beats generic stock footage | ABA Banking Journal |
| 10 | Queensborough National Bank and Trust, Augusta, Ga. | Social media giveaway | 2025 | “LOCAL” limited-edition hat | A physical item people wear spreads the brand | ABA Banking Journal |
| 11 | Citizens First Bank, The Villages, Fla. | Video campaign | 2025 | Buffalo Charity Checking: $0.10 per transaction to a scholarship fund | Make the product itself the cause | ABA Banking Journal |
| 12 | S&T Bank, Indiana, Pa. | Three-day branded event during the NFL Draft | 2026 | “S&T Bank Draft Headquarters” | Own a local moment instead of buying a logo slot | ABA Banking Journal |
| 13 | Isabella Bank, Mount Pleasant, Mich. | Product relaunch, mascots, education | 2026 | Kids Club, “Bee Smart from the Start” | Relaunch an old product with a character | ABA Banking Journal |
| 14 | Voyager Digital (not a bank) | Website, app, social media | 2022 | Statements suggesting it was FDIC-insured | Never imply deposit insurance you do not have | FDIC press release |
National bank ad campaigns: what they ran and why it works
Capital One, “What’s in Your Wallet?” (2000)
Capital One’s own 2003 agency announcement says its branding campaign “originated in 2000 with the introduction of its ‘What’s in Your Wallet?’ advertisements.” The early spots used visigoths, pirates, gladiators and yetis created by D’Arcy Advertising. By the release date, Capital One reported 96 percent brand awareness and “more than 47 million customers,” and it listed an Effie Award among the campaign’s honors (Capital One, April 11, 2003). The lesson is consistency: the agency changed in 2003, the line did not.
Bank of America, “What would you like the power to do?” (2018)
Bank of America announced the positioning on November 16, 2018. The first TV ad premiered on November 18 during Sunday Night Football on NBC, with CEO Brian Moynihan framing the question. The campaign ran across television, digital video, mobile, social media and print, developed by Hill Holliday and Super Union (Business Wire release via TMCnet). A question headline works for a bank because it hands the stage to the customer’s goal. Copy the move on a branch billboard: ask the question your best customers answer when they open an account.
Chase, “Make More of What’s Yours” (2022)
The iSpot.tv ad database lists a Chase TV spot called “Do More,” published August 30, 2022, with the tagline “Make More of What’s Yours” and McGarry Bowen as agency. Its description: animated Chase customers buy cars and go on vacations while using auto loans and travel rewards, and the US Open partnership appears (iSpot.tv). Notice what the spot does not do: it names product categories but no rate or payment. That keeps it out of the Regulation Z trigger-term rules covered below.
SoFi: a stadium, a breakup and a quarterback (2019 to 2023)
SoFi stacks three ad types. On September 15, 2019 it signed “a 20-year agreement” as exclusive naming rights partner of SoFi Stadium, and the release states that “Financial terms of the agreement will not be disclosed” (SoFi). Any price you read elsewhere is a press estimate.
On February 9, 2022 SoFi launched “Break Up With Bad Banking” ahead of Valentine’s Day: a TikTok challenge with the hashtag #SoFiBreakUpChallenge, Instagram and Twitter activity, $75,000 in rewards points across the campaign and national TV from early March (SoFi). The release carries the full contest rules: publish yours with the same care as the creative.
On October 6, 2023 SoFi launched “All Your Ambitions, All In One App” featuring Los Angeles Chargers quarterback Justin Herbert, premiering during the Chargers’ first home game and running on Peacock, Roku, Amazon, Hulu, Vizio and Tubi (SoFi). The release closes with “SoFi Bank, N.A., NMLS #696891. Member FDIC.” That one line is the official advertising statement plus the lender ID, which is the habit to copy.
Ally, the 50/50 sports media pledge (2022 to 2026)
Ally launched its pledge in May 2022 with a five-year target of equal ad spend on men’s and women’s sports media. On April 14, 2026 it reported hitting the target a year early, increasing women’s sports media spend “more than 4.6X” and moving from 10 percent of its sports media spend to 50 percent (Ally). These are Ally’s own figures. A public, dated commitment about where you spend gives the press a story every year, which a single ad cannot.
TD, the Automated Thanking Machine (2014, Canada)
On July 25, 2014, more than 20,000 TD employees handed green envelopes with a $20 bill to over 30,000 customers in more than 1,100 branches across Canada. In a few branches, “an ATM that talks and delivers surprises” gave selected customers personal thank-you moments, filmed and released as a video under #TDThanksYou (TD newsroom). It is a Canadian campaign, so US deposit rules did not apply, but the idea transfers: reward people who already bank with you and let the film do the advertising.
Community bank marketing examples that won ABA awards
The American Bankers Association’s Brand Slam awards are judged by a panel of 75 Certified Financial Marketing Professionals across six categories (ABA Banking Journal, September 16, 2025). Neither ABA article reports results for the winners, so copy the idea, not an assumed return.
The 2025 winners (ABA Banking Journal, September 16, 2025) include Summit Bank in Eugene, Oregon, whose 3.5-minute film “Do you want to Bank?” “paid tribute to Eugene’s culture”; Bank of Guam’s storytelling campaign “Proud to Be Small Business”; Queensborough National Bank and Trust’s “LOCAL” hat giveaway on social media; and Citizens First Bank’s Buffalo Charity Checking, which donates $0.10 per transaction to a scholarship foundation. The 2026 winners (ABA Banking Journal, September 24, 2026) include S&T Bank’s three-day NFL Draft experience in Pittsburgh, which “combined community events, media partnerships, charitable giving and customer engagement activities,” Reading Cooperative Bank’s “Family Fortune Campaign” built on the theme “Life Happens,” and Isabella Bank’s relaunched Kids Club with new mascots. The common thread: every winner is about a place or a life moment, and none leads with a rate.
If you are a credit union, the same ideas apply, with NCUA rules in place of FDIC ones; our guide to credit union marketing covers that side.
How much the big banks advertise on Google
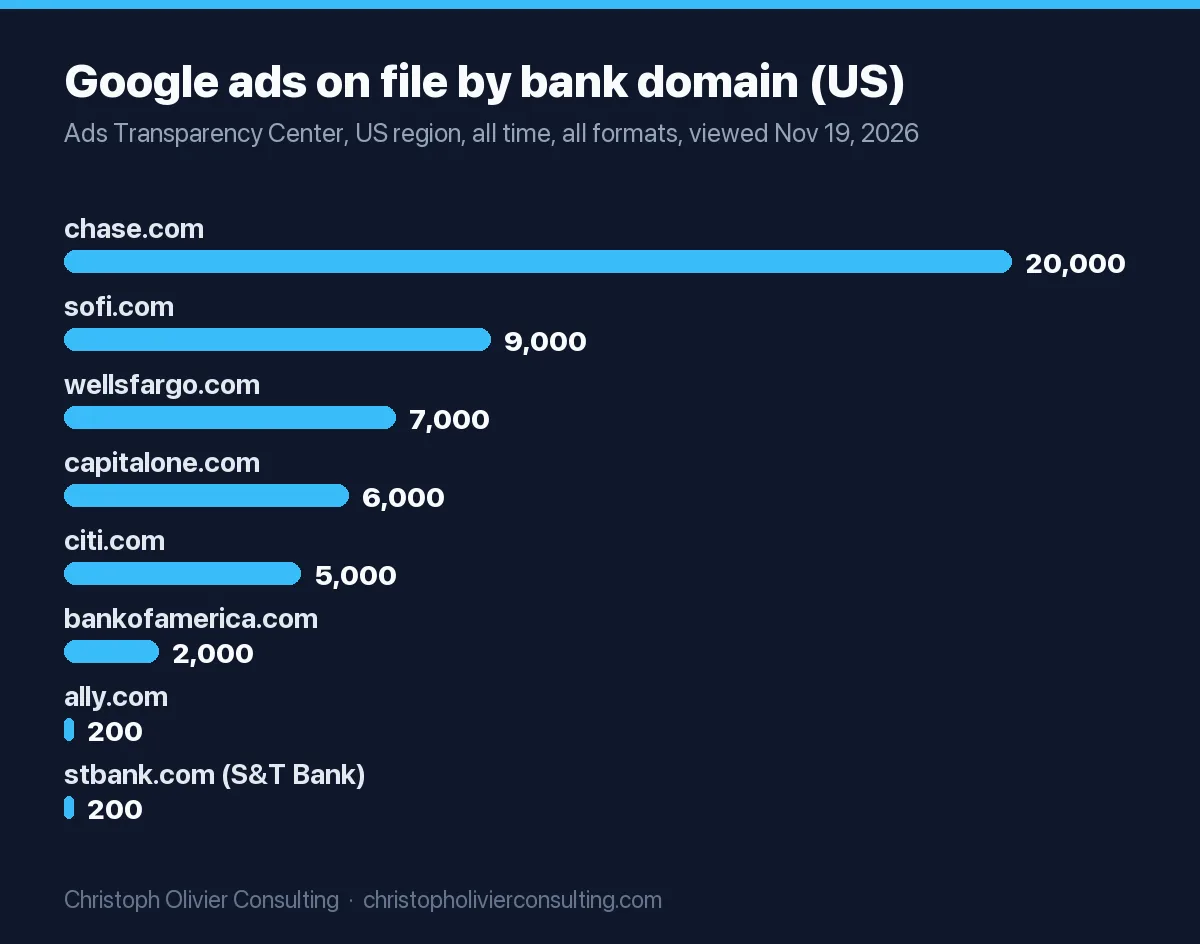
Search ads are where most bank budgets actually go day to day, and Google’s Ads Transparency Center shows how many ads point to each bank’s domain. I viewed the US region, all time, all formats, on November 19, 2026. Counts are rounded by Google and include every advertiser account sending ads to the domain, which can include agencies and co-brand partners (citi.com, for example, shows American Airlines ads for the co-branded card).
| Domain | Ads shown (US, all time) | Example advertiser account named | Record |
|---|---|---|---|
| chase.com | ~20K | JPMorgan Chase Bank, National Association | Ads Transparency Center |
| sofi.com | ~9K | Social Finance, Inc. | Ads Transparency Center |
| wellsfargo.com | ~7K | Wells Fargo Bank, N.A. | Ads Transparency Center |
| capitalone.com | ~6K | Verified advertiser accounts | Ads Transparency Center |
| citi.com | ~5K | Citibank, N.A.; American Airlines, Inc. | Ads Transparency Center |
| bankofamerica.com | ~2K | Bank of America Corporation | Ads Transparency Center |
| ally.com | ~200 | Ally Financial Inc. | Ads Transparency Center |
| stbank.com | ~200 | Alloy Marketing LLC. | Ads Transparency Center |
Before you write a rate ad, look up three competitors in your market and read their live creatives to see how they fit the APY line and Member FDIC into a small format. A few hundred ads on file is normal for a regional bank: S&T Bank sits at the same rounded count as Ally. How you split budget between search, social and branch is a separate question, covered in our breakdown of how much banks spend on marketing.
Bank advertising rules: the regulations with section numbers
Six sets of rules decide what a US bank ad must and must not say. The table quotes or closely paraphrases the official text in the eCFR (current as of November 17, 2026) and the Federal Register.
| Rule | Citation | What it requires in ads | Dates that matter |
|---|---|---|---|
| FDIC official advertising statement | 12 CFR 328.6 | Ads promoting deposits or “non-specific banking products and services” must include “Member of the Federal Deposit Insurance Corporation” or a short form (“Member FDIC,” “FDIC-Insured”) or the FDIC symbol, legibly. Exempt: radio and TV ads of 30 seconds or less (other than display ads), pens and key chains, ads that do not name the bank. Never use it in ads solely for non-deposit or hybrid products. | 2023 rule effective April 1, 2024; full compliance delayed to May 1, 2025 (89 FR 84261) |
| FDIC digital sign for websites and apps | 12 CFR 328.5 | The FDIC official digital sign on the homepage, the login page, and the page where a consumer first opens a deposit account. Pages primarily about non-deposit products need signage that they are not insured by the FDIC, are not deposits, and may lose value. Leaving the bank’s app for a third party’s non-deposit product triggers a one-time-per-session notice that can auto-dismiss after at least three seconds. | Amended by 91 FR 3801 (Jan. 29, 2026), effective March 2, 2026; compliance required by April 1, 2027 |
| FDIC sign on ATMs | 12 CFR 328.4 | The digital sign on the ATM’s initial screen. An idle-screen advertisement does not count as the initial screen. ATMs placed in service on or before April 1, 2027, and later ones without non-deposit transactions, may use the physical sign instead. | Same 2026 rule, compliance April 1, 2027 |
| Misrepresenting FDIC insurance | 12 CFR 328.102 | No person may use FDIC-associated terms or images to imply an uninsured product is insured, or imply they are an insured bank or associated with one without a clear, accurate description. Applies to fintechs and partners, not only banks. | In force |
| Truth in Savings (Regulation DD) | 12 CFR 1030.8 | No misleading ads. No “free” or “no cost” if any maintenance or activity fee may apply. Never call interest “profit.” Any stated rate must be an “annual percentage yield” (APY allowed once the full term appears). Stating an APY or a bonus triggers more disclosures (see the next table). | In force; keep evidence of compliance at least two years (1030.9(c)) |
| Truth in Lending (Regulation Z) | 12 CFR 1026.24 closed-end; 1026.16 open-end | Only advertise terms you actually offer. State rates as “annual percentage rate.” Trigger terms require the APR and other terms. Credit cards: “introductory” or “intro” next to each intro rate, plus the end date and the go-to rate. Deferred interest: “if paid in full” before the period. | In force |
| Equal housing lender | 12 CFR 338.3 | FDIC-supervised banks advertising home purchase, improvement or dwelling-secured loans must show the Equal Housing Lender logo and legend (or HUD’s Equal Housing Opportunity logo under 24 CFR 110.25); in spoken ads, say “Equal Housing Lender.” No words or images suggesting a discriminatory preference. | In force |
| UDAAP | 12 U.S.C. 5536(a)(1)(B); standards in 5531 | Unlawful for a covered person to “engage in any unfair, deceptive, or abusive act or practice.” Abusive includes conduct that “materially interferes with the ability of a consumer to understand a term or condition.” | In force |
| Credit unions (NCUA) | 12 CFR 740.5; deposit ads under 707.8 | Today: “Federally insured by NCUA” or an approved variant in ads, no smaller than the smallest other font. The NCUA has removed this requirement by final rule; the official sign rules in 740.4 stay. | 740.5 removed effective December 16, 2026 (91 FR 73430) |
Two timing points trip up marketing teams in 2026. The FDIC’s digital sign deadline moved several times: May 1, 2025, then March 1, 2026, then January 1, 2027, and the January 2026 final rule set the compliance date at April 1, 2027 (90 FR 54544 and 91 FR 3801). And credit unions keep the NCUA advertising statement until December 16, 2026, so do not strip it from live ads early.
The trigger-term table: if your ad says this, it must also say that
One number in a headline can switch on a list of required disclosures.
| If the ad states… | It must also state, clearly and conspicuously | Rule | Broadcast and billboard relief |
|---|---|---|---|
| An APY on a savings or money market account | “Annual percentage yield” at least once; variable-rate warning; the date the APY is accurate as of or how long it is offered; minimum balance to earn it; minimum opening deposit if higher; that fees could reduce earnings | 1030.8(b), (c) | TV, radio and billboards may omit variable-rate, date, opening deposit and fee statements (1030.8(e)(1)) |
| An APY on a CD | All of the above plus the term and that a penalty will or may be imposed for early withdrawal | 1030.8(c)(6) | Early withdrawal statement may be omitted in broadcast and outdoor |
| A bonus worth more than $10 | The APY; time requirement; minimum balance to get it; minimum to open if higher; when the bonus is paid | 1030.8(d); bonus defined in 1030.2 | Opening minimum and timing may be omitted in broadcast and outdoor |
| “Free” checking | Allowed only if no maintenance or activity fee may be imposed | 1030.8(a)(2) | None |
| A loan payment, number of payments, down payment or finance charge | Down payment; repayment terms over the full term; the APR, and if it can rise after consummation | 1026.24(d) | TV and radio may give the APR plus a toll-free number (1026.24(g)) |
| A mortgage rate or payment | Each rate and payment that will apply and for how long, the APR, and for first liens that taxes and insurance are not included | 1026.24(f) | Rule does not apply to TV or radio |
| “Fixed” on an adjustable mortgage | “Adjustable-Rate Mortgage” or “ARM” before the first “fixed,” and how long it is fixed | 1026.24(i)(1) | None |
| An intro credit card APR | “Introductory” or “intro” next to the rate, when it ends, and the APR after | 1026.16(g) | Proximity rules apply to written and electronic ads |
| “No interest” deferred-interest offer | “If paid in full” before the deferred interest period | 1026.16(h) | None |
| Home loan of any kind | Equal Housing Lender logo and legend, or the spoken statement | 12 CFR 338.3 | Spoken form allowed |
What went wrong: a deposit insurance claim that drew a cease-and-desist
On July 28, 2022, the FDIC and the Federal Reserve Board sent Voyager Digital a joint letter demanding it “cease and desist from making false and misleading statements” about its FDIC deposit insurance status. According to the agencies, Voyager’s website, app and social media stated or suggested that Voyager itself was FDIC-insured, that customers would get FDIC coverage for all funds held by Voyager, and that the FDIC would insure customers against Voyager’s failure (FDIC press release). Today 12 CFR 328.102 spells out the same prohibition for any person. If you are a bank partnering with a fintech, read its ads too: the partner’s claims about your FDIC insurance are your reputational risk. Our fintech marketing guide covers partner ad review, and these false advertising cases show what deceptive claims cost elsewhere.
Copy-ready bank ad templates with the rule check
These are templates, not finished ads. Replace every [placeholder] with a real, current figure you can document, and keep the disclosure lines with the headline. Character counts suit Google responsive search ads (headlines up to 30 characters) but the logic works in any format.
| # | Use case | Template headline(s) | Template body and disclosure | Rule check |
|---|---|---|---|---|
| 1 | Brand ad, no product | [Bank Name], Since [Year] Local Decisions in [Town] | Your loan officer lives here too. Visit [branch] or call [phone]. Member FDIC. | Non-specific banking ad needs the statement (328.6(c)(1)) |
| 2 | High-yield savings | [X.XX]% APY Savings Earn [X.XX]% Annual Percentage Yield | [X.XX]% Annual Percentage Yield (APY) accurate as of [date]. Rate may change after the account is opened. $[min] minimum balance to earn the APY; $[open] to open. Fees could reduce earnings. Member FDIC. | Full term once, then APY (1030.8(b)); (c)(1) to (c)(5) |
| 3 | CD special | [N]-Month CD: [X.XX]% APY | [X.XX]% APY as of [date] on a [N]-month CD. $[min] minimum to open and earn the APY. A penalty may be imposed for early withdrawal. Fees could reduce earnings. Member FDIC. | Term and penalty statement (1030.8(c)(6)) |
| 4 | Checking bonus | Get $[bonus] With New Checking | Open by [date], keep $[min] for [N] days and receive $[bonus] within [N] days after. [APY or “This account does not earn interest” if none]. [Monthly fee and how to avoid it.] Offer details: [URL]. Member FDIC. | Bonus over $10 triggers 1030.8(d); never “free” if a fee can apply (1030.8(a)(2)) |
| 5 | Auto loan | Auto Loans From [X.XX]% APR | Example: [X.XX]% APR, [N] monthly payments of $[amount] per $[amount] borrowed, $[down] down. Rates based on credit and term. | Payment amount is a trigger term (1026.24(d)); state only terms you actually offer (1026.24(a)) |
| 6 | Mortgage or HELOC | Home Loans Decided in [Town] | Talk to [name], NMLS #[ID], about purchase and refinance options. [If any rate is shown: each rate, its period and the APR, with equal prominence.] Equal Housing Lender. Member FDIC. | 338.3 logo or legend; 1026.24(f) if a rate or payment appears |
| 7 | Credit card intro APR | [0]% Intro APR for [N] Months | [0]% intro APR on purchases for [N] months from account opening, then a variable APR of [X.XX]% to [X.XX]%. [Annual fee or none.] | “Intro” next to the rate, end date and go-to APR (1026.16(g)) |
Before any of these go live, run each asset through this pass/fail check. One fail means rewrite.
- Insured status right: deposit and brand ads carry the FDIC statement or symbol; ads solely for investments, annuities or other non-deposit products carry no FDIC statement or symbol. Pass or fail.
- Rate wording right: every deposit rate is called “annual percentage yield” at least once; every credit rate is an “annual percentage rate.” No other rate is more prominent. Pass or fail.
- Triggers satisfied: every APY, bonus, payment, term, down payment or intro rate in the ad has its required companions from the trigger-term table, close to it. Pass or fail.
- No banned words: no “free” with any possible fee, no “profit” for interest, no “fixed” on an adjustable product without the ARM wording. Pass or fail.
- Offer is real: the advertised rate, bonus or term is actually available today to the people who will see the ad, and eligibility limits are stated. Pass or fail.
- Housing ads tagged: any home loan ad has the Equal Housing Lender logo or spoken statement, and imagery shows no preference. Pass or fail.
- Digital pages ready: homepage, login page and account-opening page show the FDIC digital sign by April 1, 2027. Pass or fail.
- Archived: a dated copy of the ad and its disclosures is saved for at least two years, which meets 1030.9(c) for deposit ads. Pass or fail.
Catchy banking slogans that are real
Most slogan lists online are invented. These are taglines verified in the sources above:
- “What’s in Your Wallet?” (Capital One, since 2000)
- “What would you like the power to do?” (Bank of America, since 2018)
- “Make More of What’s Yours” (Chase, on TV in 2022)
- “Get Your Money Right” (SoFi, used in its 2023 Justin Herbert spot title on YouTube)
- “Break Up With Bad Banking” (SoFi, 2022 campaign line)
- “Bee Smart from the Start” (Isabella Bank Kids Club, 2026)
What they share: short, second person, and free of rates, so they never trigger a disclosure on their own. My view: a community bank should write its line the same way and let product ads carry the numbers; for loan-officer ads, which carry the heaviest Regulation Z load, see our mortgage marketing playbook. If you want a second read on a campaign and its disclosures before launch, you can book a consultation.
Ready to scale your revenue?
Book a free 30-min consultation. We’ll diagnose your growth bottleneck and map out the 3 highest-leverage moves for your business.
Frequently asked questions
What are some examples of bank advertisements?
Verified examples include Capital One's "What's in Your Wallet?" (since 2000), Bank of America's "What would you like the power to do?" (2018), Chase's "Make More of What's Yours" TV spots, SoFi's 20-year stadium naming deal and "Break Up With Bad Banking" campaign, Ally's 50/50 sports media pledge, TD's Automated Thanking Machine, and ABA award winners such as Summit Bank's film and S&T Bank's NFL Draft event.
What are the rules for bank advertising?
Deposit and general bank ads need the FDIC advertising statement (12 CFR 328.6). Savings ads that state a rate must call it an annual percentage yield and add conditions (12 CFR 1030.8). Credit ads with trigger terms need the APR (12 CFR 1026.16 and 1026.24). Home loan ads need the Equal Housing Lender logo or statement (12 CFR 338.3), and all ads must avoid unfair, deceptive or abusive practices.
Does every bank ad need Member FDIC?
No. Under 12 CFR 328.6 it is required in ads promoting deposit products or the bank's banking services generally. Exemptions include radio and TV ads of 30 seconds or less (other than display ads), promotional items like pens, ads that do not name the bank, and directory listings. Ads solely for non-deposit products such as annuities must not use the statement.
When do banks have to show the FDIC digital sign?
The FDIC's January 2026 final rule (91 FR 3801) took effect March 2, 2026, with compliance required by April 1, 2027. Banks must show the FDIC official digital sign on the homepage, the login page and the page where a consumer first opens a deposit account, and on the initial screen of ATMs, with an exception for older ATMs.
Can a bank advertise free checking?
Only if no maintenance or activity fee may be imposed on the account. Regulation DD, 12 CFR 1030.8(a)(2), bars calling an account free or no cost, or using a similar term, if any such fee can apply. The same section also bans using the word profit to describe interest paid on an account.
What are some catchy slogans for banking?
Real, verified bank taglines include Capital One's "What's in Your Wallet?", Bank of America's "What would you like the power to do?", Chase's "Make More of What's Yours", SoFi's "Get Your Money Right" and "Break Up With Bad Banking", and Isabella Bank's "Bee Smart from the Start" for its Kids Club. Each is short, uses the second person and states no rate.
What are creative promotional ideas for banks?
Ideas proven by award-winning banks include a wearable local giveaway (Queensborough's LOCAL hat), a cause built into an account (Citizens First Bank donates $0.10 per transaction), a short film about your town (Summit Bank), owning a local event for a few days (S&T Bank at the NFL Draft), and filmed thank-you moments for existing customers (TD).
Real advertising examples by industry