
Marketing expenses are operating expenses. Under US GAAP you record advertising as an expense either when you incur it or the first time the ad runs, and almost nothing else in the marketing budget belongs on the balance sheet. For federal tax, most marketing is deductible in full as an ordinary and necessary business expense, but client meals, entertainment, gifts, political ads and pre-opening marketing each follow their own rule.
Short answer: Book marketing as an operating expense (usually inside selling or sales and marketing). ASC 720-35-25-1 lets you expense advertising “either as incurred or the first time the advertising takes place.” Only prepaid amounts, reusable physical assets, capitalized website and software costs, and contract-specific sales commissions go to the balance sheet. For tax, advertising is deductible under IRC 162; lobbying and entertainment are 0% deductible, client meals 50%, and business gifts cap at $25 per recipient per year.
This page is built for the person who has to code the invoice: owners, bookkeepers and staff accountants. It covers the GAAP rules with paragraph citations, where each cost lands on the income statement (with what seven public companies actually disclose), copy-ready journal entries, a chart of accounts you can import, and the federal tax rules as they stand after the 2025 tax law. It is general information, not tax or audit advice for your specific facts.
Where each marketing cost goes: the classification table
Start here. Find the cost, then read across for the book treatment, the income statement line and the federal tax treatment. Every rule is explained and sourced further down.
| Cost | GAAP (book) treatment | Typical P&L line | Federal tax treatment |
|---|---|---|---|
| Google, Meta, LinkedIn ads | Expense as the clicks or impressions are delivered | Selling / sales and marketing | Deductible (IRC 162) |
| TV, radio, print, outdoor media bought in advance | Prepaid asset until the space or airtime is used, then expense | Selling / sales and marketing | Deductible; timing follows the 12-month rule and, for accrual filers, economic performance |
| Ad production (video shoot, design, copy) | Expense as incurred, or defer to first airing if that is your stated policy | Selling / sales and marketing | Deductible |
| Agency retainer | Expense in the month the service is provided | Selling / sales and marketing | Deductible |
| Marketing staff salaries | Expense (payroll) | Selling, or G&A for shared roles | Deductible as wages |
| Sales commission paid only if a contract is signed | Asset under ASC 340-40, amortized; expense if amortization period is one year or less | Selling (commission expense) | Separate tax analysis; ask your preparer |
| Trade show booth space paid months ahead | Prepaid asset, expense when the show happens | Selling / events | Deductible |
| Reusable booth structure, signage, billboard you own | Fixed asset, depreciate; depreciation is an advertising cost | Selling (depreciation) | Depreciable property |
| Brochures, catalogs, logo pens on hand | Prepaid supplies until handed out, then expense | Selling / promotional | Deductible; items of $4 or less with your name are not “gifts” |
| Client gifts | Expense | Selling / promotional | Capped at $25 per recipient per year |
| Client meals | Expense | Selling or G&A | 50% deductible |
| Free food at a public promotional event | Expense | Selling / events | 100% deductible |
| Sports tickets, golf, concerts with clients | Expense | Selling or G&A | 0% deductible (entertainment) |
| Sponsorship of a charity event with your ad or logo | Expense | Selling / sponsorships | Business expense if a commensurate return is expected; otherwise a charitable contribution |
| Rebates, referral credits, co-op payments to customers | Reduction of revenue unless you receive a distinct service at fair value | Contra revenue | Separate tax analysis; ask your preparer |
| Website build | Planning and maintenance expensed; development and initial graphics capitalized | Amortization in operating expenses | Separate tax analysis; ask your preparer |
| Political ads, ballot measure campaigns, lobbying | Expense | G&A or other | Not deductible (IRC 162(e)) |
| Marketing before the business opens | Expense | Selling / sales and marketing | Start-up cost: up to $5,000 now, rest over 180 months |
How to account for marketing expenses under GAAP
The core rule: expense advertising as incurred or at first showing
US GAAP puts advertising in Subtopic 720-35. The recognition paragraph, as reproduced in FASB ASU 2016-20, says: “The costs of advertising within the scope of this Subtopic shall be expensed either as incurred or the first time the advertising takes place.” You pick one policy and apply it consistently to similar kinds of advertising. If you defer costs to the first showing and the ad is then cancelled, you expense the deferred cost immediately. The Codification’s own examples of “first time” are the first public showing of a TV commercial and the first appearance of a magazine ad.
The policy choice mostly matters for production costs. The source guidance, AICPA SOP 93-7, splits advertising into two parts: producing the ad (idea development, copy, artwork, crews) and communicating it (airtime, magazine space, billboard space, postage). Production costs are incurred during production. Communication costs are not incurred until the space or airtime has been received, so prepaid media is never expensed early. Real filers write exactly this into their policies: Expedia’s 2025 10-K expenses production costs “in the period in which the advertisement first takes place” and airtime “each time the advertisement is shown.”
What happened to capitalized direct-response advertising
Older textbooks (and some current web pages) still say you can capitalize direct-response advertising, such as a catalog mailing with order coupons, if you can track who responded. That rule lived in ASC 340-20 and is gone for entities on ASC 606. FASB’s basis for conclusions in ASU 2016-20 (paragraph BC38) states that ASU 2014-09 superseded much of Subtopic 340-20 “because it would have conflicted with the new cost capitalization guidance in Subtopic 340-40,” and that an entity that previously capitalized advertising costs “is required to apply the capitalization guidance in Subtopic 340-40.” ASU 2016-20 then moved the one surviving piece, the accrual rule for cooperative advertising, into ASC 720-35-25-1A. In practice, a marketing cost is capitalized now only if it is an incremental cost of obtaining a specific contract, which ordinary advertising never is.
Prepaid advertising, brochures and physical ad assets
- Prepaid media: pay for airtime, print space or booth space in advance, record a prepaid asset, and expense it when used (SOP 93-7 paragraph .44).
- Digital ads: Target’s 10-K describes the common practice: digital advertising costs are “expensed as incurred when the consumer engages with the advertisement through clicks or views.”
- Sales materials: brochures and catalogs “may be accounted for as prepaid supplies until they no longer are owned or expected to be used,” according to PwC’s US GAAP vs IFRS guide. Branded giveaways follow the same logic.
- Physical assets: tangible assets such as billboards that serve several campaigns are capitalized and depreciated, and the depreciation “may be a cost of advertising” (SOP 93-7 paragraph .30). A reusable trade show booth is the small-business version.
Sales commissions are not marketing: ASC 340-40
The one place GAAP requires capitalization is the incremental cost of obtaining a contract. ASC 340-40-25-1 and 25-2, quoted in the FASB/IASB revenue TRG paper on contract costs, require an asset for costs “that it would not have incurred if the contract had not been obtained (for example, a sales commission)” when you expect to recover them. Costs you would incur whether or not you win the contract, which covers every ad, event and agency fee, are expensed (25-3). The practical expedient in 25-4 lets you expense even qualifying commissions “if the amortization period of the asset that the entity otherwise would have recognized is one year or less.” Keep commissions in their own account so this test is easy to run.
Website costs: ASC 350-50 now, ASC 350-40 from 2028
Under the current website guidance, planning-stage and operating-stage costs (hosting, routine updates, training) are expensed, while application, infrastructure and initial graphics development follow the internal-use software capitalization rules, as summarized in Duke University’s capitalization policy. That is changing. Crowe’s summary of ASU 2025-06 (issued September 18, 2025) explains that Subtopic 350-50 is superseded and website costs move into 350-40, which drops the stage model. Capitalization begins when management authorizes and commits funding and it is probable the project will be completed, with no capitalization while “significant development uncertainty” exists. The ASU is effective for annual periods beginning after December 15, 2027, and early adoption is permitted. For a marketing site built on a standard CMS, expect little change; for a custom app or portal, document approvals and funding dates now.
Payments to customers reduce revenue
Rebates, coupons, referral credits applied to a client’s invoice, and cooperative advertising payments to resellers often get coded to marketing. Under ASC 606-10-32-25, consideration payable to a customer is “a reduction of the transaction price and, therefore, of revenue unless the payment to the customer is in exchange for a distinct good or service.” If you do receive a distinct service, any amount above its fair value still reduces revenue, and if you cannot estimate fair value, all of it does (32-26). Airbnb’s 2025 10-K shows the split clearly: of $662 million paid to customers in 2025, $484 million was recorded as a reduction of revenue and only $77 million as sales and marketing expense.
If you report under IFRS
IFRS is stricter. PwC notes there is no option to defer to the first showing, and brochures and catalogs are expensed when the entity has the right to access them, not when they are handed out.
Is marketing an operating expense? Where it goes on the income statement
Yes. Marketing and advertising are operating expenses: they sit below gross profit and above operating income. Many companies put them in selling expenses, or in a combined “selling, general and administrative” line; companies that present by function often show a separate “sales and marketing” line. Payments to customers move out of operating expenses into contra revenue (above), and vendor reimbursements, common in retail, are netted against advertising, as Target does. Shared roles, such as a marketing coordinator who also runs the front office, are commonly allocated between selling and G&A.
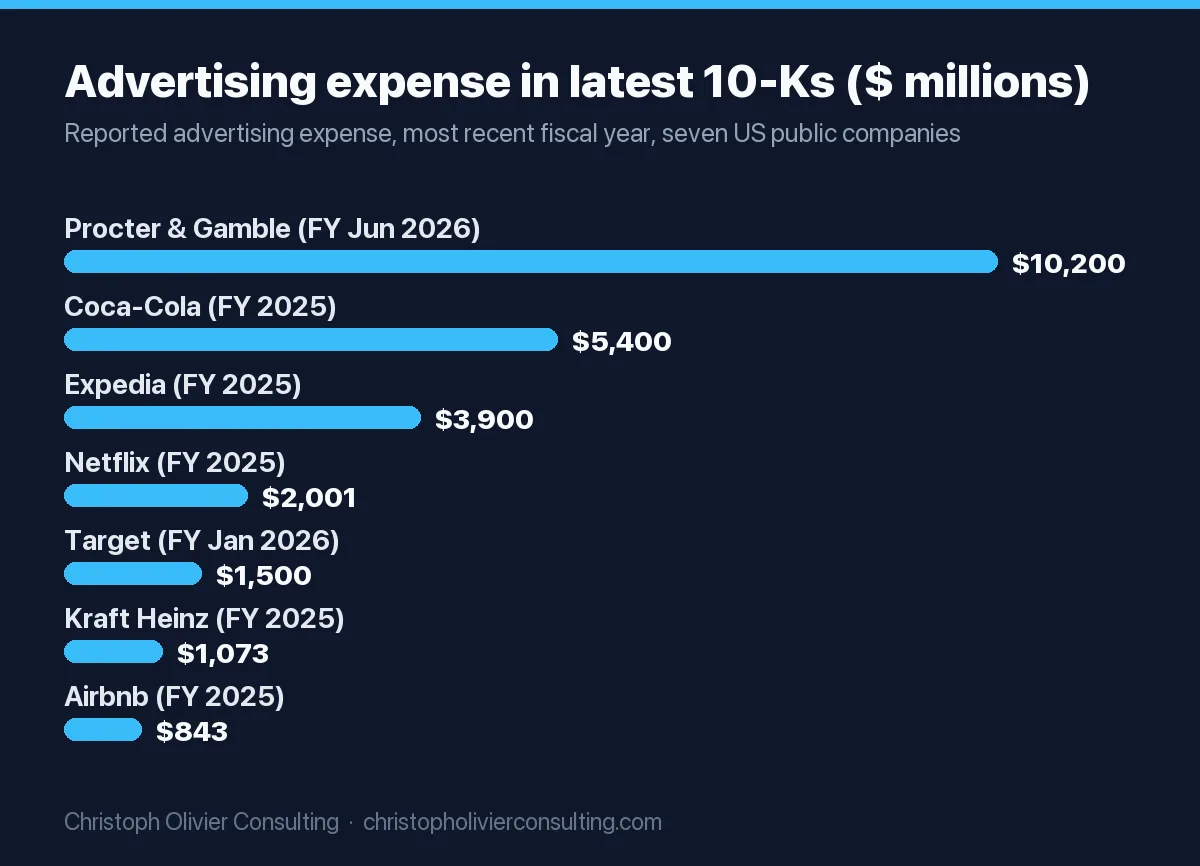
GAAP also requires a note. SOP 93-7 paragraph .49, now carried in ASC 720-35-50-1, requires you to disclose the policy you chose (as incurred or first showing) and the total advertising expense for each income statement presented. Here is how seven public companies do it in their latest 10-Ks:
| Company (fiscal year) | Advertising expense, reported | Income statement line | Policy as disclosed | Source |
|---|---|---|---|---|
| Procter & Gamble (FY ended June 30, 2026) | $10.2 billion | SG&A | Charged to expense as incurred | 10-K |
| Coca-Cola (2025) | $5.4 billion | SG&A | Production costs expensed the first date the ads take place | 10-K |
| Expedia (2025) | $3.9 billion | Selling and marketing | Production at first showing; airtime each time shown | 10-K |
| Netflix (2025) | $2.001 billion | Sales and marketing | Expensed as incurred | 10-K |
| Target (FY ended Jan. 31, 2026) | $1.5 billion, net of vendor reimbursements | SG&A | Digital on clicks or views; broadcast at first showing | 10-K |
| Kraft Heinz (2025) | $1,073 million | SG&A | Interim periods charged as a percentage of estimated full-year sales | 10-K |
| Airbnb (2025) | $843 million | Sales and marketing | Expensed as incurred | 10-K |
Two lessons for a private company’s books. First, “advertising expense” is narrower than the marketing line: Airbnb’s $843 million of advertising sits inside $2,588 million of total sales and marketing, and Netflix’s $2.0 billion sits inside $3.3 billion. Payroll, agencies and software are marketing expenses but not advertising. Second, the Kraft Heinz approach (charging advertising in interim periods as a percentage of estimated full-year sales activity and marketing costs) is a reasonable model for monthly management reporting when campaigns are lumpy, as long as the year-end books reflect actual costs. If you are building the budget that feeds these lines, the method in our guide to setting a marketing budget maps one-to-one onto the accounts below.
Marketing expense journal entries (copy-ready)
Account numbers refer to the chart of accounts in the next section. Amounts are illustrations. Swap in your own.
| # | Transaction | Date | Debit | Credit |
|---|---|---|---|---|
| 1 | LinkedIn Ads charge of $2,400 for October, paid by company card | Oct 31 | 6110 Digital Advertising 2,400 | 2110 Credit Card Payable 2,400 |
| 2a | Pay $12,000 in March for booth space at an October trade show | Mar 15 | 1420 Prepaid Trade Shows and Events 12,000 | 1000 Cash 12,000 |
| 2b | Show takes place | Oct 10 | 6150 Trade Shows and Events 12,000 | 1420 Prepaid Trade Shows and Events 12,000 |
| 3a | Agency retainer of $6,000 invoiced for the current month | Monthly | 6130 Agency and Contractor Fees 6,000 | 2000 Accounts Payable 6,000 |
| 3b | Same agency paid one quarter ($18,000) in advance | Jan 1 | 1410 Prepaid Advertising and Marketing 18,000 | 1000 Cash 18,000 |
| 3c | Month-end release of the prepaid retainer | Jan 31, Feb 28, Mar 31 | 6130 Agency and Contractor Fees 6,000 | 1410 Prepaid Advertising and Marketing 6,000 |
| 4a | Google Ads delivered $3,450 of clicks in October; invoice arrives in November | Oct 31 | 6110 Digital Advertising 3,450 | 2150 Accrued Advertising 3,450 |
| 4b | Auto-reverse the accrual, then post the invoice normally | Nov 1 | 2150 Accrued Advertising 3,450 | 6110 Digital Advertising 3,450 |
| 5a | Buy 2,000 logo pens at $1.80 each | Feb 1 | 1430 Promotional Supplies on Hand 3,600 | 2000 Accounts Payable 3,600 |
| 5b | Count shows 500 pens handed out (500 x $1.80) | Feb 28 | 6160 Promotional Items and Samples 900 | 1430 Promotional Supplies on Hand 900 |
| 6a | Video production of $30,000 finished; policy is “expense at first showing” | Nov 20 | 1410 Prepaid Advertising and Marketing 30,000 | 2000 Accounts Payable 30,000 |
| 6b | Commercial airs for the first time | Jan 15 | 6120 Advertising Production and Creative 30,000 | 1410 Prepaid Advertising and Marketing 30,000 |
| 7 | Buy a reusable booth for $15,000; 5-year life, straight line ($15,000 / 5 = $3,000 a year) | Purchase, then each Dec 31 | 1520 Marketing Equipment 15,000; then 6158 Depreciation, Marketing Assets 3,000 | 1000 Cash 15,000; then 1525 Accumulated Depreciation 3,000 |
| 8 | $1,500 of referral credits applied to clients’ invoices | Dec 31 | 4900 Customer Incentives (contra revenue) 1,500 | 1200 Accounts Receivable 1,500 |
| 9a | $9,000 commission owed on a signed 3-year client contract | Signing date | 1610 Deferred Contract Costs 9,000 | 2200 Commissions Payable 9,000 |
| 9b | Monthly amortization ($9,000 / 36) | Each month-end | 6210 Sales Commissions 250 | 1610 Deferred Contract Costs 250 |
Notes on the entries: in entry 6, a company whose policy is “expense as incurred” debits 6120 on November 20 and skips 6b. In entry 9, if the amortization period were one year or less, the practical expedient lets you debit 6210 directly. In entry 5, the pens cost less than $4 each and carry your name, which matters for tax (see gifts below).
Chart of accounts for marketing expenses
No accounting standard dictates account numbers. The numbering below follows the common pattern (1000s assets, 2000s liabilities, 4000s revenue, 6000s operating expenses). The value is in the split: each tax treatment gets its own account, so the book-to-tax adjustments at year end come straight off the trial balance instead of from a review of every receipt.
| No. | Account | What goes in it | Tax flag |
|---|---|---|---|
| 1410 | Prepaid Advertising and Marketing | Media bought ahead, deferred production, prepaid retainers | Check 12-month rule |
| 1420 | Prepaid Trade Shows and Events | Booth space, sponsorship fees for future events | Check 12-month rule |
| 1430 | Promotional Supplies on Hand | Brochures, catalogs, logo merchandise not yet distributed | None |
| 1520 / 1525 | Marketing Equipment / Accumulated Depreciation | Reusable booths, owned signage, displays | Depreciable property |
| 1530 | Capitalized Website Development | Development and initial graphics that meet ASC 350-50 / 350-40 | Separate tax analysis |
| 1610 | Deferred Contract Costs | Capitalized commissions under ASC 340-40 | Separate tax analysis |
| 2150 | Accrued Advertising | Ad spend delivered but not yet invoiced | Economic performance (accrual filers) |
| 4900 | Customer Incentives (contra revenue) | Rebates, referral credits, co-op payments to customers | Separate tax analysis |
| 6110 | Digital Advertising | Search, social, display, sponsored listings | 100% |
| 6115 | Print, Broadcast and Outdoor Media | Airtime, print space, billboard rental, direct mail postage | 100% |
| 6120 | Advertising Production and Creative | Shoots, design, copywriting, printing of ads | 100% |
| 6130 | Agency and Contractor Fees | Agency retainers, freelancers, fractional marketing leaders | 100% |
| 6135 | Marketing Software and Subscriptions | CRM, email platform, SEO tools, analytics | 100% |
| 6140 | Website Hosting and Maintenance | Hosting, plugins, routine content updates | 100% |
| 6150 | Trade Shows and Events | Booth space, event fees, shipping | 100%; food goes to 6170 or 6172 |
| 6155 | Sponsorships | Event and team sponsorships with ad placement | Business expense vs charitable test |
| 6158 | Depreciation, Marketing Assets | Depreciation on 1520 | Tax depreciation may differ |
| 6160 | Promotional Items and Samples | Logo merchandise, samples, displays given to customers | Items of $4 or less with your name are not gifts |
| 6165 | Business Gifts | Gifts to clients and referral partners (log recipient names) | $25 per recipient per year |
| 6170 | Client and Prospect Meals | Meals with a business contact present | 50% |
| 6172 | Public Promotional Food | Free food and drinks offered to the general public | 100% |
| 6175 | Entertainment | Tickets, golf, concerts, hospitality boxes | 0% |
| 6180 | Market Research | Surveys, panels, research reports | 100% |
| 6185 | Public Relations | PR retainers, press release distribution | 100% |
| 6190 | Marketing Salaries and Benefits | Marketing staff payroll (or keep in payroll and allocate) | 100% as wages |
| 6195 | Lobbying and Political | Political ads, ballot campaigns, lobbying portion of dues | 0% |
| 6210 | Sales Commissions | Expensed and amortized commissions | Separate tax analysis |
The same structure makes the management side easier. Customer acquisition cost starts from these accounts divided by new clients, as shown in our CAC guide, and the clean split lets you calculate marketing ROI by channel without a separate spreadsheet.
Are marketing expenses tax deductible?
Yes, in general. IRC 162(a) allows a deduction for “all the ordinary and necessary expenses paid or incurred during the taxable year in carrying on any trade or business,” and Treas. Reg. 1.162-1(a) names “advertising and other selling expenses” in its list of business expenses. IRS Publication 334 defines ordinary as “common and accepted in your field of business” and necessary as “helpful and appropriate.” Brand and goodwill advertising qualifies too: Reg. 1.162-20(a)(2) covers “institutional or ‘good will’ advertising which keeps the taxpayer’s name before the public,” and the IRS’s own Chief Counsel Advice 9939035 cites Rev. Rul. 92-80 for the point that advertising is “still generally deductible even though those costs may still have some future benefit.” One housekeeping note: Publication 535, which many older articles cite, was discontinued after its 2022 revision; Publications 334 and 463 now carry this guidance.
The exceptions are where the money is. This table is built from the Code and the 2025 editions of the IRS publications:
| Expense | Federal deduction | Rule |
|---|---|---|
| Advertising, agencies, digital ads, PR, marketing software | 100% | IRC 162(a) |
| Food and drinks given free to the general public to promote the business | 100% | IRC 274(e)(7) and (n)(2); Pub. 463, Exception 5 |
| Business meals with a client or prospect | 50% | IRC 274(n)(1) |
| Entertainment (tickets, golf, shows) | 0% | IRC 274(a) |
| Business gifts | Up to $25 per recipient per year | IRC 274(b)(1) |
| Logo items of $4 or less, widely distributed; signs and displays for the recipient’s premises | 100% (not “gifts”) | Pub. 463, Gifts: Exceptions |
| Political campaign ads, influencing the public on elections, legislation or referendums, lobbying | 0% | IRC 162(e)(1) |
| Marketing before the business opens | Up to $5,000 in year one, rest over 180 months | IRC 195(b)(1) |
| Payment to a charity for advertising with an expected business return | 100% as business expense | Reg. 1.162-15(a) |
Client meals, events and entertainment
Entertainment is fully disallowed under IRC 274(a), and business meals are limited to 50% under 274(n). The exception people miss is the public one. Publication 463 says you are not subject to the 50% limit “if you provide meals to the general public as a means of advertising or promoting goodwill in the community.” Free coffee and pastries at a tax-season open house that anyone can walk into is 100% deductible; dinner with three clients after the open house is 50%; their tickets to the game afterwards are 0%. Food served at an entertainment event is treated as a meal rather than entertainment only if it is bought separately or stated separately on the bill, per Pub. 463. Code accordingly, which is why the chart above has separate accounts 6170, 6172 and 6175.
Separately, starting with amounts paid after December 31, 2025, IRC 274(o) disallows employer costs for on-premises eating facilities and meals furnished for the employer’s convenience. That affects staff meal programs, not client marketing.
Client gifts: the $25 rule
Under IRC 274(b)(1) you can deduct no more than $25 of business gifts per recipient per year. Publication 463 adds the working details: incidental costs such as engraving, gift wrapping, insuring and mailing are not counted toward the $25 if they don’t add substantial value; a gift to a company “intended for the eventual personal use or benefit of a particular person” counts as a gift to that person; spouses are treated as one taxpayer; and an item that could be a gift or entertainment is generally treated as entertainment, except packaged food or drinks the client will use later, which is a gift. Worked example: a $60 wine-and-cheese basket to each of 40 referral partners costs $2,400 but deducts $1,000 (40 x $25), assuming the basket itself is not a substantial share of the value.
Sponsorships: business expense or donation?
Treas. Reg. 1.162-15(a) allows a payment to a charity as a business expense when it “bears a direct relationship to the taxpayer’s trade or business” and is made with a reasonable expectation of a commensurate financial return. The regulation’s own example: a $1,000 payment for a half-page ad in a church concert program that lists the seller’s website is a section 162 expense. The classification matters more from 2026 for C corporations: under IRC 170(b)(2)(A) as amended by Pub. L. 119-21, corporate charitable contributions count only to the extent they exceed 1% of taxable income (and up to 10%), for tax years beginning after December 31, 2025. A sponsorship that qualifies as advertising avoids that floor.
Political ads and lobbying
IRC 162(e)(1) denies any deduction for participating in a political campaign and for “any attempt to influence the general public, or segments thereof, with respect to elections, legislative matters, or referendums.” An issue ad urging voters to reject a local ballot measure is not deductible, even though it looks like advertising. The old exception for local legislation was struck in 2017. If a trade association tells you part of your dues went to lobbying, that portion is also nondeductible under 162(e)(2).
Marketing before you open: Section 195 start-up costs
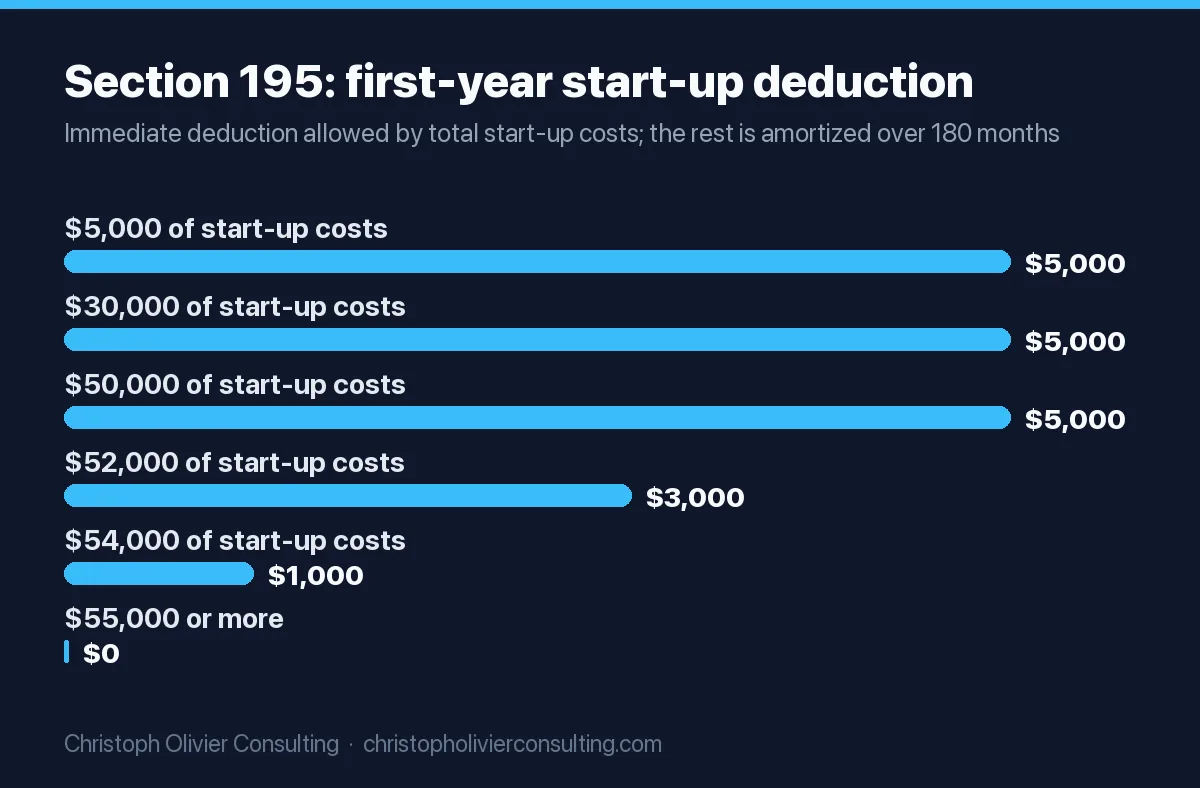
Advertising for a business that has not started yet is a start-up cost. IRS Publication 583 lists advertising among typical start-up costs, and IRC 195(b)(1) lets you elect to deduct up to $5,000 in the year the business begins, “reduced (but not below zero) by the amount by which such start-up expenditures exceed $50,000,” with the remainder deducted “ratably over the 180-month period” starting the month the business begins.
Worked example: a new practice spends $53,000 on start-up costs, including $18,000 of pre-launch ads, and opens October 1.
- Immediate deduction: $5,000 minus ($53,000 minus $50,000) = $2,000.
- Amortizable remainder: $53,000 minus $2,000 = $51,000.
- Monthly amortization: $51,000 / 180 = $283.33.
- Year one amortization (October to December): 3 x $283.33 = $850.
- Total first-year deduction: $2,000 + $850 = $2,850. At $55,000 or more of start-up costs, the immediate piece is zero.
On the books, the same $18,000 of ads is simply expensed under ASC 720-35. That gap is a temporary book-to-tax difference your preparer tracks.
Prepaid marketing for tax
For tax, a prepayment is not automatically deductible when paid. Publication 334 says you can’t deduct expenses paid “far enough in advance to, in effect, create an asset with a useful life extending substantially beyond the end of the current-tax year.” The 12-month rule in Treas. Reg. 1.263(a)-4(f) removes the capitalization requirement when the benefit does not extend beyond the earlier of 12 months after it starts or the end of the following tax year. Accrual-method taxpayers must also meet economic performance: the regulation’s Example 11 involves a company that prepays $40,000 in August for advertising services to be delivered the next calendar year, and concludes the expense is not incurred until the services are provided.
What the 2025 tax law changed
For marketing, very little. Checking the amendment notes on each section: Pub. L. 119-21 made only a conforming edit to the start-up cost definition in IRC 195(c)(1) (adding section 174A); the $5,000, $50,000 and 180-month figures are unchanged. In IRC 274, it added a 50%-limit exception for certain fishing vessels and adjusted 274(o); the gift, entertainment and meal rules above are unchanged. The change that does reach marketing budgets is the 1% floor on corporate charitable contributions described under sponsorships.
Month-end checklist for marketing spend
Use this as a pass/fail step in your monthly close.
- Accruals: each ad platform’s billing report for the month ties to posted bills plus 2150 Accrued Advertising. Pass = difference under your materiality threshold.
- Prepaids: 1410, 1420 and 1430 each have a schedule listing the item, the run or event date, and the release date. Pass = schedule total equals the GL balance.
- Deferred production: any production cost held in 1410 has a scheduled first airing. Pass = no item whose campaign was cancelled (ASC 720-35-25-1 requires immediate expense).
- Customer payments: rebates, referral credits and co-op payments are in 4900, not 6xxx. Pass = no customer names in the 6100 to 6195 vendor list without a documented distinct service.
- Meals vs entertainment vs public food: 6170, 6172 and 6175 are coded from the receipt, not the card feed category. Pass = spot-check of five receipts matches.
- Gifts log: 6165 has a recipient name for every line. Pass = no recipient above $25 for the year without a note.
- Commissions: new signed contracts with commissions are tested against the one-year practical expedient. Pass = memo on file.
For firms that sell accounting and tax services, the same discipline is a marketing asset: a CPA practice that can show clients a clean marketing ledger is credible when it advises on theirs. If you are planning your own firm’s spend, our playbook on marketing for CPA and accounting firms covers which channels to fund, and a strategy call is the fastest way to turn those budget lines into a plan.
Ready to scale your revenue?
Book a free 30-min consultation. We’ll diagnose your growth bottleneck and map out the 3 highest-leverage moves for your business.
Frequently asked questions
Are marketing expenses tax deductible?
Generally yes. Advertising and other selling expenses are deductible as ordinary and necessary business expenses under IRC 162 and Treas. Reg. 1.162-1(a). The exceptions: entertainment is 0% deductible, client meals 50%, business gifts are capped at $25 per recipient per year, political and lobbying ads are not deductible, and marketing before the business opens is a Section 195 start-up cost.
Is marketing an operating expense?
Yes. Marketing and advertising are operating expenses reported below gross profit, usually within selling expenses, a combined SG&A line, or a separate sales and marketing line. Payments to customers such as rebates and referral credits are the exception: under ASC 606 they reduce revenue unless you receive a distinct good or service at fair value.
What is the journal entry for marketing expenses?
For a paid ad invoice, debit Advertising Expense and credit Accounts Payable, Credit Card Payable or Cash. If you pay before the ad runs, debit Prepaid Advertising and credit Cash, then move the amount to Advertising Expense when the ad runs. Ads delivered but not yet billed at month end are accrued: debit Advertising Expense, credit Accrued Advertising.
Can marketing costs be capitalized under GAAP?
Rarely. ASC 720-35 requires advertising to be expensed as incurred or the first time the ad runs. Capitalized direct-response advertising under ASC 340-20 was superseded by ASU 2014-09. Assets arise only for prepaid amounts, reusable physical items such as booths or billboards, qualifying website development costs, and incremental contract costs such as sales commissions under ASC 340-40.
How do you account for prepaid advertising?
Record the payment as a prepaid asset, for example Prepaid Advertising, because costs of communicating advertising such as airtime or print space are not expensed before the space or time is used. Release the asset to advertising expense when the ad runs or the event occurs, and keep a schedule that ties the prepaid balance to the general ledger every month.
Is advertising a selling expense or general and administrative expense?
Advertising is normally a selling expense, or part of sales and marketing. Coca-Cola, Procter & Gamble, Target and Kraft Heinz report it inside SG&A; Netflix, Expedia and Airbnb report it in a sales and marketing line. General and administrative is for costs such as finance, legal and executive management, though shared roles may be allocated between the two.
Are startup marketing costs deductible?
Advertising paid before the business opens is a start-up cost under IRC 195. You can elect to deduct up to $5,000 in the year the business begins, reduced dollar for dollar by start-up costs above $50,000, and deduct the rest evenly over 180 months. With $53,000 of start-up costs, the immediate deduction is $2,000.