
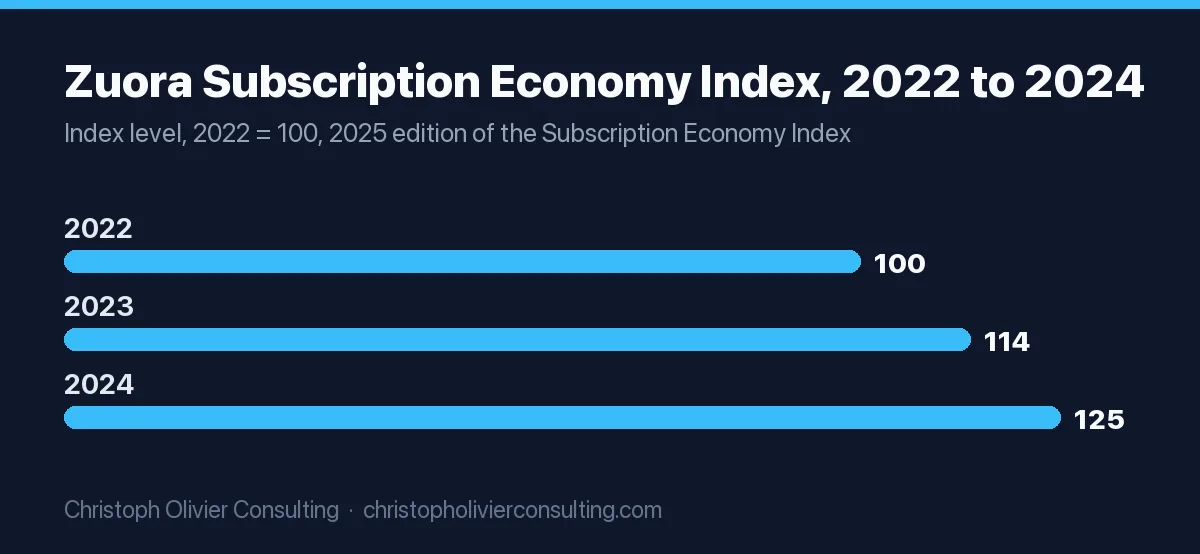
The latest Zuora Subscription Economy Index (SEI) is the 2025 edition, published in April 2025 on data for the 12 months ending December 31, 2024. Its headline: SEI companies posted an 11% faster revenue growth rate than the S&P 500 over the prior two years, unique subscribers rose 25%, and the index climbed from 100 in 2022 to 125.1 in 2024 (Zuora SEI 2025). As of November 1, 2026, Zuora’s press page lists no 2026 edition, so any “2026 SEI” figure you see quoted is either the 2025 report or not from Zuora.
Below: every headline figure from the 2025 report, how the index is built, how the “4.6x faster than the S&P 500” type claims changed edition by edition, four market-size estimates side by side, labeled vendor churn benchmarks, the current click-to-cancel and auto-renewal law status, a “which number to cite” table and a churn-to-LTV worked example.
Zuora Subscription Economy Index 2025: key findings
Every figure in this table is quoted from Zuora’s own 2025 Subscription Economy Index report page. The business metrics come from Zuora billing data plus public-company sources; the consumer figures come from a Harris Poll survey Zuora commissioned.
| Finding | Exact figure | Data type |
|---|---|---|
| Revenue growth vs S&P 500 | 11% faster revenue growth rate over the last two years | Company data |
| Unique subscribers | +25% over the past two years | Company data |
| Index level | 100 (2022), 113.8 (2023), 125.1 (2024) | Company data, 732 companies |
| ARPA growth, 4+ revenue models | 2.3% faster than 2 to 3 models, 4.5% faster than 1 model | Company data, 715 companies |
| ARPA growth by model count | 1 model: -2.3%; 2 to 3 models: -0.1%; 4+ models: 2.2% | Company data |
| Churn by model count | Single-model companies worsened 3.1%; 2 to 3 models improved 0.5%; 4+ improved 0.2% | Company data |
| Hybrid pricing | “Nearly half” of top-performing SEI companies use hybrid approaches | Company data |
| Product portfolio breadth (PPBS) | Scores up 118% over the last 4 years | Company data, 1,080 companies |
| Revenue growth, Media, Entertainment & Communications | 22.5% (2022 to 2023), 59.1% (2023 to 2024) | Company data |
| Revenue growth, High Tech/SaaS | 1.9% (2022 to 2023), 0.3% (2023 to 2024) | Company data |
| New subscriptions | 68% of U.S. adults subscribed to a new service for the first time in 2024 | Harris Poll, n=3,087 |
| Top cancellation reason | 47% of 2024 cancellers cited a price increase | Harris Poll |
| Perceived value | 84% got the same (50%) or greater (34%) value over the past year | Harris Poll |
| Long-term loyalty | 39% have kept a favorite subscription for 5+ years | Harris Poll |
| GenAI subscription use | 28% (May 2024) to 40% (January 2025) | Harris Poll |
| Paying extra for GenAI | 64% not ready to pay extra, down from 70% in Zuora’s previous study | Harris Poll |
| Most common new service | Streaming 37%, music 24% | Harris Poll |
| Password sharing | 51% have used someone else’s login (30% in the past year) | Harris Poll |
The finding with the most practical weight is the revenue-model one. Companies running four or more revenue models (for example subscription plus usage plus one-time plus add-ons) grew ARPA while single-model companies shrank it. If you are deciding how to add tiers or usage pricing, that is the number to bring to the meeting, and the mechanics of adding paid expansions are covered in our upselling and cross-selling guide.
What the Subscription Economy Index measures (methodology)
The SEI is not a market-size estimate. It is an index of growth in the “volume of business” of recurring-revenue companies, set to 100 in a base year. Per the 2025 methodology:
- Who is in it: the methodology says “more than 600 companies”; the headline index chart is labeled 732 companies. The pool combines billing data from 1,890 Zuora customers with public data on 16 named consumer brands (including Netflix, Spotify, Disney+, Duolingo, ChatGPT and YouTube) pulled from Business of Apps in early January 2025. Each table uses a different subset, from 62 manufacturing companies to 1,080 for the PPBS trend.
- Base year: 2022 = 100 in the 2025 edition. Earlier editions used other base years, so index levels are not comparable across editions.
- Benchmark: SEI revenue growth is compared with the S&P 500 “as a proxy for the broader economy.”
- Churn: churned customers divided by customers at the start of the period, times 100.
- ARPA: average revenue per account. The page gives two definitions (trailing 12 months of billed recurring revenue per active subscriber in the glossary; total annual revenue per active subscription in the methodology), so quote ARPA growth directions, not absolute values.
- Consumer survey: The Harris Poll, online, January 8 to 10, 2025, 3,087 U.S. adults, weighted, with a Bayesian credible interval of plus or minus 1.8 percentage points.
The built-in bias: most of the panel are Zuora customers, companies that chose a subscription billing platform. That makes the SEI a good read on how subscription-native businesses perform and a poor proxy for the whole economy.
Every SEI edition compared: from “300% growth” to “11% faster”
The multiples people quote (“4.6x faster”, “3.4x faster”) come from different editions with different time windows. Here is each one, taken from Zuora’s own releases.
| Edition (release date) | Headline claim | Single-year growth: SEI vs S&P 500 | Panel |
|---|---|---|---|
| March 21, 2019 | Sales grew more than 300% (321%) in seven years; about 5x faster than S&P 500 revenue and U.S. retail sales | 18.1% CAGR vs 3.6% (2012 to 2018) | Not stated |
| February 16, 2022 | Grew 4.6x faster than the S&P 500 over the past decade; 17.5% 10-year CAGR | 16.2% vs 12% (2021) | Not stated |
| March 29, 2023 | 3.7x faster than the S&P 500 over the past 11 years | 12% vs 10.6% (2022) | More than 500 businesses |
| April 9, 2024 | 3.4x faster than the S&P 500 over the past 12 years | 10.4% vs 6% (2023) | Over 600 businesses |
| April 2025 (latest) | 11% faster revenue growth rate over the last two years; subscribers +25% | Not published as a pair | More than 600 (index chart: 732) |
Two things fall out of this table. First, the long-run multiple shrank every year, from 4.6x to 3.7x to 3.4x, as the strong 2012 to 2018 years carried less weight and S&P 500 revenue growth caught up after 2020. Second, the 2025 edition dropped the multiple entirely. “11% faster” is a two-year comparison, not a decade-long one, so never write “grew 11x” or put it in a row with the 4.6x figure as if they were the same measure. Other headline numbers from the older releases: quarterly churn averaged 6.36% in 2022 versus 6.13% in 2018 (2023 edition), and churn “dropped” 14% in 2021 (2022 edition).
Subscription economy market size: four estimates, one table
Because the SEI is an index, “how big is the subscription economy” has to come from market-research firms. Their scope definitions differ, which is why the numbers do.
| Source (date) | 2025 value | Forecast | Growth assumption |
|---|---|---|---|
| Future Market Insights (updated Sep 23, 2025) | $557.8B | $1,028.6B by 2030; $1,944.4B by 2035 | 13.3% CAGR, 2025 to 2035 |
| market.us (updated Jul 9, 2026) | $557.7B | $2,516.5B by 2035 | 16.3% CAGR |
| Juniper Research, via Advanced Television (Oct 1, 2025) | $722B | $1.2T by 2030 | +67% over five years |
| Zuora SEI | Not a market size | None | Index: 125.1 in 2024 (2022 = 100) |
Useful splits inside those reports: FMI puts B2B models at 55.2% of the 2025 market; market.us puts B2B at 54.20%, SaaS subscriptions at 38.60% and North America at more than 42.10% (about $234.79B). Juniper expects digital video to hold over 33% of global subscription spend by 2030, with mobility as a service the fastest-growing class. The two firms that agree on 2025 (about $558B) still end $572B apart in 2035, purely on the growth rate they assume. Quote a range and the firm, never a lone “trillion-dollar” figure.
Subscription churn statistics (vendor benchmarks, labeled)
Churn benchmarks come from billing vendors measuring their own customers. They are useful and they are not neutral. Label them that way when you cite them.
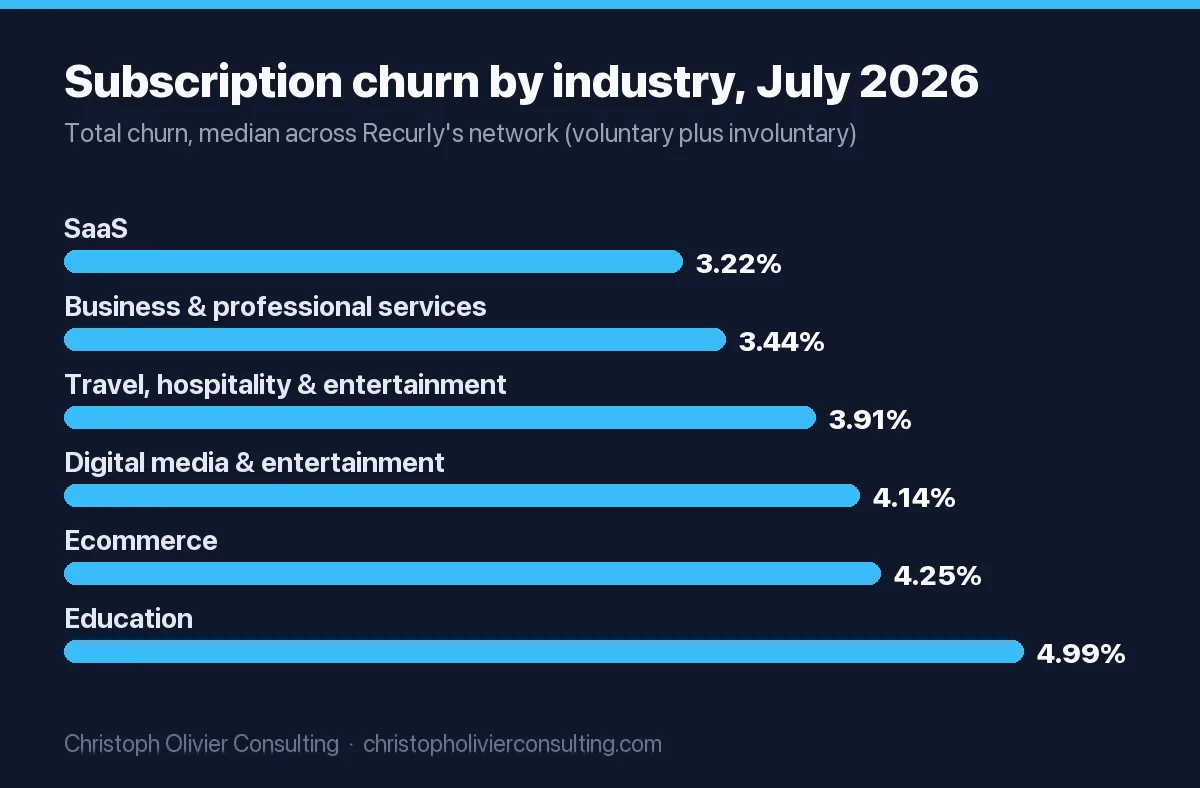
Recurly churn benchmarks, July 2026 data
Recurly’s benchmark page, “updated with July 2026 data,” shows 3.60% overall churn across its network: 2.34% voluntary (customers who cancel) and 1.25% involuntary (failed payments). Industry figures are medians from the Recurly network.
| Industry (Recurly network) | Total churn | Voluntary | Involuntary |
|---|---|---|---|
| SaaS | 3.22% | 2.16% | 1.06% |
| Business & professional services | 3.44% | 2.27% | 1.18% |
| Travel, hospitality & entertainment | 3.91% | 2.63% | 1.28% |
| Digital media & entertainment | 4.14% | 2.55% | 1.59% |
| Ecommerce | 4.25% | 2.87% | 1.38% |
| Education | 4.99% | 3.30% | 1.69% |
| All industries | 3.60% | 2.34% | 1.25% |
Two cautions before you quote it. Recurly’s chart calls the industry figures “median annual churn rates,” while its own definition says churn is “typically calculated monthly or annually depending on your billing model,” and the all-industry tiles carry no period at all. The page text also cites 3.04% for software and 3.21% for business services, which do not match its chart. Quote the chart values, name the month of data, and do not annualize them yourself.
Recurly 2026 State of Subscriptions
Recurly’s 2026 State of Subscriptions report draws on 76 million subscribers. Headline figures: acquisition rates “stabilizing around 3%,” overall subscription growth “slowing to 12.6%,” former subscribers driving “nearly 1 in 4 new sign-ups,” pause usage up 337% year over year among merchants offering pause before cancel, 3 of 4 subscribers who pause eventually returning, and annual plans generating 50% to 60% higher revenue per user. On the consumer side, 52% canceled at least one subscription in the past year due to lack of use.
Chargebee: why subscribers cancel and which save offers work
Chargebee Retention benchmarks (Q1 2024 cancellation data, outliers removed) rank cancellation reasons: pricing 31% (up from a usual 20%), not enough time 16%, missing features 15%, no longer needed 15%, integration issues 8%. Save offer acceptance: discounts 17% overall and 21% in B2C, pauses 15% in B2C, extensions 14% in SaaS, gifts and credits 13%. In its 2024 survey, 86% of subscription leaders ranked retention as an equal or higher priority than acquisition.
Paddle ProfitWell index: SaaS growth and churn in 2025
The Paddle Q2 2025 SaaS market report (published July 30, 2025) tracks MRR across a sample of 34,000+ companies on ProfitWell Metrics. B2B SaaS posted a 5.1% CAGR in Q2 against 1.4% in Q1, and the B2B churn index averaged -1.563, “the lowest we’ve seen since the end of 2022.” The authors “strongly suspect” AI features drove the rebound but say they cannot confirm it from index data. These are index readings, not churn percentages, so do not put them in a table next to Recurly’s rates.
Subscription fatigue statistics 2025 and 2026
Fatigue is real, but it shows up as switching and price pushback rather than people abandoning subscriptions. The best current data:
| Statistic | Figure | Source, fieldwork |
|---|---|---|
| Canceled a streaming video (SVOD) service in the last six months | 43% of U.S. consumers; Gen Z 57% (up 7 points from fall 2025) | Deloitte Digital Media Monitor, fall 2026 |
| Monthly SVOD spend per subscribing household | $76 (Gen Z $83) | Deloitte, fall 2026 |
| Frustrated that services keep raising prices | “Almost two-thirds” of consumers | Deloitte, fall 2026 |
| Canceled at least one subscription for lack of use | 52% | Recurly, 2026 |
| Price increase was the main reason for canceling | 47% of 2024 cancellers | Zuora/Harris Poll, Jan 2025 |
| Did not cancel any subscription in 2024 | 27% | Zuora/Harris Poll, Jan 2025 |
| Estimated vs actual monthly subscription spend | $86 estimated, $219 actual ($133 gap, about 2.5x) | C+R Research, Apr 22 to May 2, 2022, n=1,000 |
| Find recurring charges easy to forget | 74% | C+R Research, 2022 |
| Kept paying for a service they stopped using | 42% | C+R Research, 2022 |
| Feel overwhelmed by how many subscriptions they have | 22% | C+R Research, 2022 |
The pattern across three independent sources: price is the trigger. Zuora’s 47% price-driven cancellations, Chargebee’s pricing share jumping to 31% and Deloitte’s two-thirds who are frustrated by price rises all point at the renewal and price-change moment. The C+R spending gap is the most quoted fatigue stat on the web, but it is from 2022; label the year every time. For how loyalty holds up against those price pressures outside subscriptions, see our customer loyalty statistics.
What changed in 2025 and 2026: subscription economy news timeline
| Date | Event | Why it matters |
|---|---|---|
| April 2025 | Zuora publishes the 2025 SEI (latest edition) | Source of the “11% faster” and “+25% subscribers” figures |
| July 1, 2025 | California’s amended Automatic Renewal Law (AB 2863) takes effect | Tighter state consent, reminder and cancellation rules |
| July 8, 2025 | Eighth Circuit vacates the FTC “click-to-cancel” rule | Federal rule gone six days before its July 14 compliance date |
| July 30, 2025 | Paddle Q2 2025 report: B2B SaaS CAGR 5.1% vs 1.4% in Q1 | SaaS subscription growth rebound |
| September 25, 2025 | FTC and Amazon settle Prime case for $2.5B | ROSCA enforcement continues without the rule |
| October 1, 2025 | Juniper: $722B in 2025 to $1.2T by 2030 | Most-cited 2025 market forecast |
| February 12, 2026 | FTC conforms the Negative Option Rule to the court decision | Rule text reflects the vacatur |
| March 11 to 13, 2026 | FTC announces and publishes an ANPRM on negative option plans; comments closed April 13, 2026 | A new federal rule is possible but not proposed yet |
| Fall 2026 | Deloitte: 43% canceled an SVOD service in six months | Latest consumer churn reading |
Click-to-cancel and auto-renewal laws: status in 2026
Federal: the FTC click-to-cancel rule is vacated, ROSCA still applies
On July 8, 2025, in Custom Communications, Inc. v. FTC (No. 24-3137), the Eighth Circuit vacated the FTC’s amended Negative Option Rule because the agency skipped a required preliminary regulatory analysis; the court did not rule on the merits (WilmerHale summary). The rule had been due to take effect July 14, 2025. The FTC’s Negative Option Rule page lists a February 12, 2026 notice conforming the rule to the court decision, and on March 11, 2026 the agency sought comment on an advance notice of proposed rulemaking. Per Gibson Dunn and Jones Day, comments closed April 13, 2026, and the notice asks whether to amend the 1973 rule, revive parts of the vacated 2024 rule, or take another approach. No proposed rule appears on the FTC page yet.
Enforcement did not stop. The FTC’s September 25, 2025 Amazon settlement under the FTC Act and the Restore Online Shoppers’ Confidence Act (ROSCA) carried a $1 billion civil penalty and $1.5 billion in redress for an estimated 35 million consumers, and requires that Prime cancellation use the same method as sign-up. More enforcement examples sit in our roundup of false advertising examples.
California Automatic Renewal Law: AB 2863, effective July 1, 2025
California’s amendments, signed September 24, 2024, apply to contracts entered into, amended or extended on or after July 1, 2025 (Fenwick; Barnes & Thornburg). If you sell subscriptions to California residents, this is the checklist:
| Requirement | Pass if |
|---|---|
| Express affirmative consent | Renewal terms get a separate consent step, not bundled with other terms |
| Proof of consent | Kept for 3 years or 1 year after the contract ends, whichever is longer |
| Annual reminder | Sent yearly, in the medium the customer signed up with, stating the service, charges and how to cancel |
| Price change notice | Sent 7 to 30 days before the new price takes effect, with cancellation information |
| Same-channel cancellation | Online sign-ups can cancel online |
| Save offers | Any discount or retention offer shown at cancel sits next to a continuously displayed “click to cancel” button |
| Free trials | Free-to-paid conversions are treated as automatic renewals |
My practical read: with the federal rule gone, California’s ARL is the most demanding standard many U.S. subscription businesses face, which makes it a sensible baseline for your sign-up and cancel flows. Check other states where you sell before assuming it covers them.
Which subscription economy number to cite
Use this table when a slide, pitch or article needs one number. It matches the claim you want to make to the figure that actually supports it.
| You want to say | Cite this | Do not cite | Caveat to include |
|---|---|---|---|
| Subscription companies outgrow the market | Zuora SEI 2025: 11% faster revenue growth rate than the S&P 500 over two years | “4.6x faster” as a current figure (it is the 2022 edition, decade window) | Panel is mostly Zuora customers |
| Long-run outperformance | Zuora SEI 2024: 3.4x faster over 12 years | Mixing 3.4x and 11% in one sentence | Name the edition year |
| Size of the subscription economy | About $558B in 2025 (FMI, market.us) to $722B (Juniper) | The SEI index level; old trillion-dollar projections | Scope definitions differ by firm |
| Typical churn | Recurly July 2026: 3.60% total, 2.34% voluntary, 1.25% involuntary | Annualized figures you computed yourself | Vendor network median; period labeling is ambiguous |
| Why people cancel | Zuora/Harris: 47% cite price increases | Unsourced “70% fatigue” roundup stats | U.S. adults, January 2025 |
| Streaming churn right now | Deloitte fall 2026: 43% canceled an SVOD in six months | Six-month and three-month churn figures side by side | Streaming only |
| Consumers underestimate spend | C+R: $86 guessed vs $219 actual | The figure without its year | 2022 survey, n=1,000 |
| Federal cancel rules | Click-to-cancel vacated July 8, 2025; ANPRM March 2026; ROSCA in force | “The FTC requires click-to-cancel” | Check the FTC rule page for a newer step |
Worked example: what churn does to subscriber lifetime value
Benchmarks only matter once you turn them into dollars. Take a hypothetical subscription business: 1,000 subscribers, $50 a month, 70% gross margin, $300 to acquire each customer, and 3.6% monthly churn (the size of Recurly’s all-industry total, used here as a monthly input for illustration).
- Annual retention: 0.964 to the 12th power = 0.644. You keep 64.4% of a cohort after a year and lose 35.6%.
- Average lifetime: 1 divided by 0.036 = 27.8 months.
- Gross-margin LTV: $50 x 70% x 27.8 = $972. LTV to CAC: $972 / $300 = 3.2.
- Recover half the involuntary churn (1.25 points of failed-payment churn, so 0.625 points back through card updaters, retries and dunning): churn falls to 2.975%. Lifetime becomes 33.6 months and LTV $1,176, up $204 per subscriber, or about $204,000 across 1,000 subscribers. LTV to CAC rises to 3.9.
- Sanity check the basis: plug the same 3.6% in as an annual rate and the lifetime becomes 27.8 years. That is why you confirm whether a benchmark is monthly or annual before it goes into a model.
Payment recovery moved LTV by 21% without a single new customer or price change. The full LTV formulas, including cohort and discounted versions, are in our customer lifetime value guide, and the ratio targets are in the LTV to CAC ratio guide. If you want this model run on your own billing data, you can book a consultation.
Subscription statistics that are hard to verify
Several numbers circulate on statistics roundups without a traceable primary source: “average consumer holds 5.6 subscriptions,” “41% report subscription fatigue,” and B2B SaaS churn figures attributed to “Zuora’s latest” 2026 index. I could not match any of them to a publisher’s own page, so they are left out here. My rule of thumb: if a subscription stat does not name the vendor, the fieldwork date and the sample, it is not ready to put in front of a board.
Frequently asked questions
What is the Zuora Subscription Economy Index?
The Subscription Economy Index (SEI) is Zuora's annual benchmark of how fast recurring-revenue companies grow, built mostly from anonymized Zuora billing data plus public data on brands like Netflix and Spotify. It is an index (2022 = 100 in the 2025 edition), compared against S&P 500 revenue growth. It is not a market-size estimate, and its panel leans toward subscription-native companies.
What are the Zuora Subscription Economy Index 2025 key findings?
The April 2025 edition, on data through December 31, 2024, found SEI companies had an 11% faster revenue growth rate than the S&P 500 over two years, unique subscribers grew 25%, and the index rose from 100 in 2022 to 125.1 in 2024. Companies with four or more revenue models grew ARPA fastest. Its Harris Poll found 47% of 2024 cancellers cited price increases.
Is there a 2026 Zuora Subscription Economy Index?
Not as of November 1, 2026. Zuora's press page lists 2026 releases on products and appointments but no 2026 SEI, so the April 2025 edition remains the latest. Figures labeled as the 2026 SEI on statistics roundups could not be traced to Zuora and should be treated as unverified until Zuora publishes a new report.
How much faster do subscription businesses grow than the S&P 500?
It depends on the edition. Zuora reported 4.6x faster over a decade (February 2022), 3.7x over 11 years (2023), 3.4x over 12 years (2024), and an 11% faster revenue growth rate over two years in the 2025 edition. These use different windows, so cite the edition and period rather than mixing the multiples.
How big is the subscription economy in 2025?
Estimates for 2025 range from about $557.7 billion (market.us) and $557.8 billion (Future Market Insights) to $722 billion (Juniper Research). Forecasts diverge further out: FMI projects $1,944.4 billion by 2035, market.us $2,516.5 billion by 2035, and Juniper $1.2 trillion by 2030. Scope definitions differ, so quote the firm with the figure.
What is the average subscription churn rate in 2026?
Recurly's benchmark page, updated with July 2026 data, shows 3.60% total churn across its network: 2.34% voluntary and 1.25% involuntary from failed payments. SaaS is lowest at 3.22% and education highest at 4.99%. These are vendor network medians, and the page's period labeling is ambiguous, so do not annualize them without checking.
Is the FTC click-to-cancel rule in effect in 2026?
No. The Eighth Circuit vacated it on July 8, 2025, before its July 14 compliance date. In March 2026 the FTC opened an advance notice of proposed rulemaking, with comments closed April 13, 2026, but no new rule has been proposed. ROSCA still applies, as the $2.5 billion Amazon Prime settlement shows, and California's amended auto-renewal law took effect July 1, 2025.